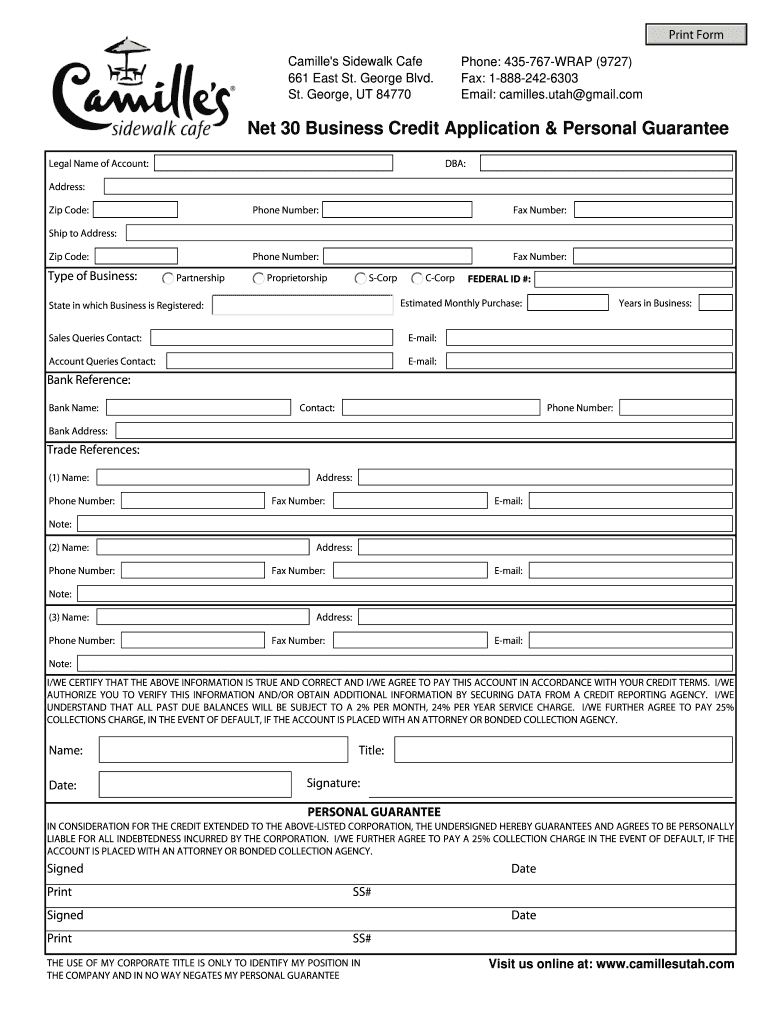
Business Credit Application With Personal Guarantee Form
Use a Business Credit Application With Personal Guarantee template to make your document workflow more streamlined.
What this credit application does
A Business Credit Application With Personal Guarantee Form lets a company request credit while an individual agrees to personal responsibility under the guarantee terms. The applicant supplies business identity, ownership, contact, financial, trade-reference, and requested-credit information, then identifies the authorized business signer and guarantor. In signNow, upload the document, review automatically detected fillable fields, assign each field to the correct signer, send the application, and retain the completed PDF with its Audit Trail. Electronic execution may be recognized under ESIGN and applicable state law, including UETA or New York ESRA, when intent, consent, attribution, and record reproduction are established.
Business types that use this form
This form fits businesses seeking supplier, equipment, or trade credit where an individual agrees to support the company’s payment obligations.
Solo professional services firms use the application to request trade credit while documenting the owner’s personal guarantee, business address, financial information, and authorization in one signed record. Growing construction companies use it for supplier or equipment credit applications, routing the company representative and guarantor through separate fields before storing the approved credit package. Multi-location enterprises use reusable templates and controlled roles to collect consistent credit applications, guarantees, and approvals while keeping signer identity and completion evidence attached.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the application workflow works
Prepare the exact business credit application, identify the guarantor, and preserve the signed record through a controlled signNow workflow.
Upload: Upload the blank application Prepare: Review detected fillable fields Route: Assign signer and guarantor fields Archive: Store the signed package and audit trail
What the Audit Trail records
The signNow Audit Trail documents the technical events that connect the business credit application and personal guarantee to the identified signing parties.
Authenticate signers:
Record timestamps:
Hash document:
Seal record:
Export evidence:
Archive package:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Choose the right signing method
- Use the web app when a credit manager needs to upload the application, place fields, assign the business signer and guarantor, and monitor completion from a desktop workflow.
- Use the mobile app when an owner or guarantor reviews and signs the application away from the office, while preserving the completed document and audit evidence.
- Use kiosk mode when staff assist an applicant at a controlled location; configure the session so each signer completes only the fields assigned to that person.
- Use a shareable signing link when the guarantor should open the application from a controlled distribution channel without requiring a separate email invitation.



Retention practices for signed credit applications
Preserve the signed application, guarantee, supporting records, and audit evidence according to the record’s actual regulatory purpose.
Apply the correct retention period
Export the audit trail
Protect personal financial information
Document signer capacity and purpose
Retention periods for related records
Retention depends on the record’s actual purpose; apply these periods only when the signed credit package contains the identified regulated records.
Three years: federal tax records
Six years: substantial understatement
Six years: HIPAA-related records
Three years: payroll records
Five years: injury records
Risks of an incomplete credit application
Missing guarantee terms
Inaccurate financial data
Unverified signer identity
Absent electronic consent
Signer authentication and digital evidence
PKI authentication:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Signing evidence:
Privacy and disclosure pitfalls
The personal guarantee may expose a guarantor’s address, financial details, and signature to recipients who do not need full access. A missing electronic-record consent disclosure can weaken evidence when a consumer-facing guarantor must receive and retain records electronically. Unrestricted template permissions can let a sender change guarantee language or financial fields without documented approval before signature. Email forwarding can expose the completed application and guarantor information outside the intended credit-review group.
Troubleshooting the credit application workflow
Resolve field assignment, consent, authentication, plan, and evidence questions before relying on a completed Business Credit Application With Personal Guarantee Form.
Confirm that the business applicant and individual guarantor have separate assigned fields. In signNow, assign each signature, date, and initials field to the correct recipient before sending; this preserves attribution and supports the ESIGN and UETA intent-and-record requirements.
The signNow Business plan includes templates and audit trails, while Business Premium adds bulk send. If several applications must be sent with individualized guarantor information, verify the plan’s workflow limits before selecting bulk send.
A typed or drawn signature can evidence an electronic signature when intent and attribution are established. For higher assurance, configure available signer authentication, such as SMS OTP or advanced authentication, and retain the resulting Audit Trail.
For a consumer-facing guarantor, provide the ESIGN consumer disclosure required by 15 U.S.C. §7001(c), including paper-record rights, electronic-access capability, and withdrawal procedures. signNow can preserve the signed record, but the business must provide the disclosure.
Use signNow’s Audit Trail and completed-document history to review timestamps, recipient actions, and delivery events. Export both records after completion and store them with the application so the business can reproduce the signed transaction.
A personal guarantee is not automatically enforceable merely because it was signed electronically. Review the guarantee language, signer authority, consideration, applicable state contract law, and any creditor requirements before relying on it.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.