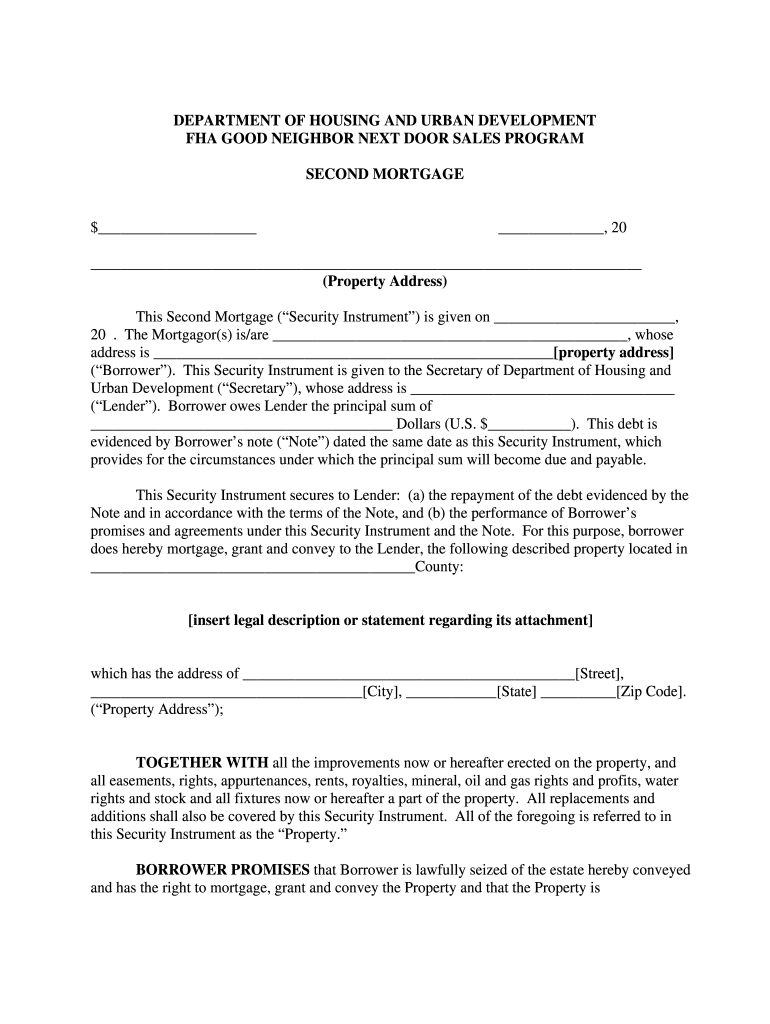
Second Mortgage Form
Use the Second Mortgage Form 0 template to simplify high-volume document management.
What a Second Mortgage Form does
A Second Mortgage Form records the terms and signatures for a loan secured by an existing property lien. It identifies the borrower, lender, property, principal amount, interest terms, payment obligations, and lien position required by the transaction documents. The form supports review and execution; it does not itself replace state-required recording, notarization, title work, or lender underwriting. With signNow, a prepared PDF can be uploaded, fillable fields can be detected and assigned, and completed signatures, timestamps, and audit evidence can be retained with the final document.
Business types using second mortgage forms
Second Mortgage Form workflows serve professionals who coordinate borrower, lender, and settlement-party signatures across separate transactions.
Solo real-estate attorneys can prepare second-lien documents for individual borrowers, organize required signatures, and preserve a complete signed record without coordinating repeated office visits. Mortgage brokerage teams can route borrower, lender, and settlement-party signatures on the same Second Mortgage Form while keeping each signer’s assigned fields and signing order clear. Regional lending enterprises can standardize second-lien document templates, delegate sending to approved staff, and retain audit evidence across multiple branches and borrower transactions.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features that support second-lien execution
Second Mortgage Form workflows benefit from structured fields, controlled routing, audit evidence, and organized storage for borrower and lender records.
Assigned fields
Place borrower, lender, date, amount, interest, and signature fields directly on the Second Mortgage Form so each participant sees the information requiring completion.
Signing order
Route the form to borrowers, lenders, and other transaction participants in a defined order, reducing uncertainty about whose signature is still outstanding.
Audit trail
Capture signer actions, timestamps, and document history alongside the completed second-lien record for later transaction review or dispute analysis.
Record access
Keep the signed form and completion evidence together, helping teams retrieve the executed document when servicing, refinancing, or title questions arise.
Reusable template
Use signNow templates to preserve recurring second-lien field placement and routing rules without rebuilding the same document structure for every borrower.
Electronic execution
Support remote execution under ESIGN and applicable state electronic-transaction law when the parties provide intent, consent, attribution, and reproducible records.
How Second Mortgage Form moves online
The signNow workflow converts a prepared Second Mortgage Form into an assigned, traceable signing package without changing the underlying transaction terms.
Upload form: Upload the prepared Second Mortgage Form PDF. Assign fields: Detect and place fields for each signer. Send document: Send the form through signNow routing. Store evidence: Review signatures and preserve the final record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the audit trail records
The audit trail separates signer identity evidence from the Second Mortgage Form itself, creating a traceable record of execution events.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Track events:
Retrieve evidence:
Recommended second-lien workflow setup
Configure the Second Mortgage Form workflow around signer identity, document integrity, transaction evidence, and the retention rules applicable to the lender and property.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Retain completion certificate and event log |
| Document retention | Follow applicable state and loan-record rules |
| Encryption | AES-256 at rest and TLS 1.2/1.3 |
Security for second-lien records
AES-256 encryption:
TLS 1.2/1.3:
SOC 2 Type II:
ISO 27001:
ESIGN and UETA:
HIPAA with BAA:
Challenges when completing second mortgage forms
Borrower, lender, and settlement-party fields may be assigned to the wrong signer, leaving required terms unsigned or attributed incorrectly. A second-lien document may require notarization or county recording that an electronic signature workflow alone does not satisfy. Property descriptions, lien priority, principal amounts, and interest terms can conflict with the title commitment or loan agreement. A completed PDF may be stored without its audit trail, weakening the transaction record available for later review.
Best practices for second mortgage records
Accurate lien information, deliberate signer assignment, complete audit evidence, and state-specific review reduce avoidable execution problems.
Reconcile property and lien information
Assign fields to the correct parties
Preserve completion evidence
Verify state recording requirements
Why teams look for DocuSign alternatives
Organizations seek alternatives when they need different pricing models, stronger native automation, simpler bulk affidavit workflows, or more flexible identity-verification options than those available in a legacy envelope-based vendor.

Second Mortgage Form troubleshooting
These answers address field assignment, signer identity, electronic consent, plan limits, and state-law issues that can affect a second-lien signing workflow.
Upload the PDF, then verify detected fields against the Second Mortgage Form before sending. signNow supports templates and assigned fields, but the sender remains responsible for confirming that borrower, lender, amount, property, and signature fields are positioned correctly.
The Business plan includes legally binding eSignatures, templates, audit trails, and mobile apps at $8/user/month with annual billing. It includes 100 signature invites per user per year; overage fees may apply, so review plan usage before sending volume increases.
Use SMS OTP or another available authentication control when the transaction requires stronger signer attribution. Advanced signer authentication is listed with Enterprise at $30/user/month annually; the appropriate control depends on lender policy and applicable law.
ESIGN and UETA support electronic signatures when intent, consent, attribution, and record reproduction are established. They do not decide whether a county requires notarization or recording for a second-lien instrument, so confirm the applicable state and county rules separately.
For a consumer-facing electronic record, 15 U.S.C. §7001(c) requires disclosure of paper-record rights, electronic-access capability, and withdrawal procedures. Capture and retain that consent evidence with the Second Mortgage Form when the transaction falls within the provision.
Export the completed Second Mortgage Form together with its audit trail and completion certificate. signNow provides audit trails on the Business plan; the lender or settlement team must still apply its own legal, servicing, and state-specific retention schedule.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.