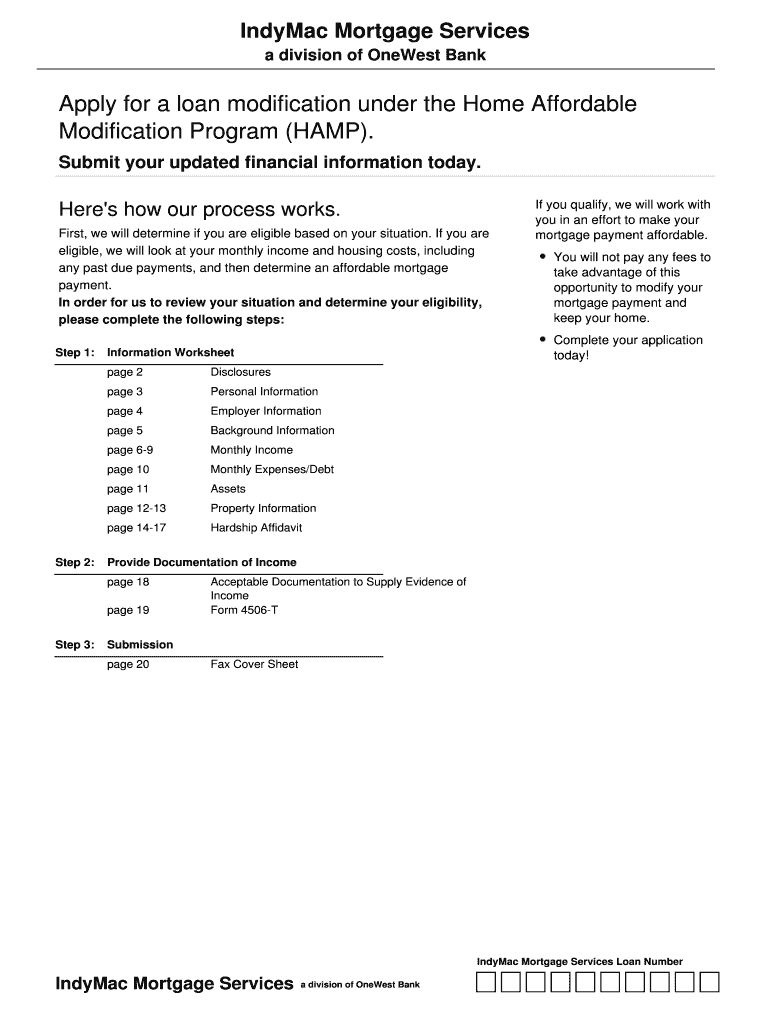
Indymac Loan Modification Application Form
Use a Indymac Loan Modification Fillable Application Pdf Form template to make your document workflow more streamlined.
What the Indymac application does
The Indymac Loan Modification Application Form is a borrower request for review of changes to an existing mortgage obligation. It gathers the borrower’s identity, property and loan information, financial circumstances, hardship explanation, requested relief, and supporting attestations for lender or servicer evaluation. With signNow, a sender uploads the approved PDF, reviews detected fillable fields, assigns borrower and co-borrower roles, sends invitations, collects electronic signatures, and stores the completed file with an audit trail. The application itself does not guarantee approval or change loan terms.
Who uses the Indymac application
Mortgage servicers
Mortgage servicers and loss-mitigation departments use the Indymac application to collect borrower hardship details, income information, property data, requested payment changes, and supporting signatures. A signNow template can standardize lender-specific fields while role-based access limits sensitive financial information to authorized reviewers and assigned signers.
Borrower representatives
Borrowers, housing counselors, and authorized representatives use the form to present a modification request and supporting facts to the servicing team. signNow’s mobile apps and signing links can reduce in-person exchanges, while the completed PDF and audit trail preserve the submitted version for review.
Key features for the Indymac form
signNow combines field preparation, signer routing, electronic consent, audit evidence, and document storage for a controlled Indymac application workflow.
Field preparation
Upload the approved Indymac PDF and review detected fields before assigning borrower, co-borrower, and lender responsibilities.
Signer routing
Route the modification request to each required participant without exchanging multiple paper copies or email attachments.
Electronic signing
Collect typed or drawn electronic signatures while preserving signer actions, timestamps, and completion history.
Audit evidence
Keep the completed application associated with its audit evidence for lender review and later retrieval.
Reusable templates
Use reusable templates to maintain consistent borrower and lender fields across repeated modification requests.
Mobile access
Work from desktop or mobile devices when borrowers or servicing staff cannot meet in person.
Recommended application workflow setup
Configure the Indymac application around borrower identity, lender review, electronic consent, audit evidence, and the retention policy governing the underlying mortgage record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Export certificate with completed PDF |
| Document retention | Follow lender and state-law policy |
| Encryption | TLS 1.2/1.3 and AES-256 encryption |
Complete the Indymac application online
Prepare the lender-approved application in signNow, verify every borrower-specific field, route it to the required parties, and preserve the completed document with its audit evidence.
Upload form:
Upload the lender-approved Indymac application PDF. Check fields:
Review detected fields and add missing borrower fields. Assign roles:
Assign borrower, co-borrower, and lender roles. Send request:
Send the prepared application through signNow. Archive record:
Collect signatures and download the completed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How signNow records the signing event
The audit trail separates technical signing evidence from the application’s borrower information and shows how the completed Indymac record was handled.
Authenticate signer:
Capture timestamp:
Hash document:
Seal document:
Log activity:
Retrieve evidence:



Security for application records
Encryption:
Security report:
Information security:
Electronic records:
Health information:
Privacy controls:
Indymac application processing stages
The application has no universal processing deadline in the supplied record; lenders should assign dates based on loss-mitigation policy, borrower communications, and applicable state requirements.
Document preparation
Delivery to signers
Signer turnaround
Completion and archival
Application preparation challenges
Borrower income, expenses, and hardship explanations may conflict across the application and supporting financial documents. Missing co-borrower signatures can delay lender review even when the primary borrower completes every assigned field. An outdated lender template may omit requested fields or contain instructions that do not match current servicing procedures. Unclear signing order can leave the application incomplete when borrower, co-borrower, and lender approvals require separate actions.
Best practices for this application
Accurate field assignment, informed consent, controlled access, and complete evidence handling reduce avoidable delays in the Indymac modification review process.
Verify every lender-specific field
Assign parties before sending
Capture consumer consent properly
Preserve the completed evidence
Legal standing of the application
A completed Indymac Loan Modification Application Form may support a U.S. business transaction when the signer demonstrates intent, consents to electronic records, can be identified, and the record remains accurate and reproducible under ESIGN and applicable UETA provisions. Wills, codicils, testamentary trusts, court orders, official court filings, and specified family-law documents are excluded by 15 U.S.C. §7003.

Legal and process risks
Excluded notice
Consent failure
Authority dispute
Evidence gap
Indymac loan modification troubleshooting
Use these answers to resolve field, signer, authentication, enforceability, document-integrity, and audit-trail questions for the Indymac application.
Why does signNow not detect every field automatically? Upload a clear PDF, then review auto-detected fields manually. The Business plan supports templates and audit trails, but field recognition does not determine legal completeness. Confirm borrower income, hardship, property, and authorization sections before sending.
Why did the signer miss the invitation? Check the recipient email, spam filtering, and signing status in signNow. Business and Business Premium plans support email invitations; Business Premium also includes quick invite links. Resend only after confirming the borrower’s correct address and consent.
Can a borrower sign this form by SMS? signNow can add stronger authentication options, including SMS OTP where configured. Business Premium supports quick invite links, while Enterprise adds advanced signer authentication. Select controls based on lender policy and document sensitivity, then preserve the audit trail.
Does signNow make a loan modification automatically enforceable? No. ESIGN and UETA support electronic records when intent, consent, attribution, and accurate reproduction are established. The lender’s approval, state law, loan documents, and foreclosure rules still control the modification’s legal effect.
Why is the completed PDF different from the draft? signNow seals the completed document with signing history and an audit trail. Compare the final PDF with the approved Indymac application before signing, because later edits can require a new signing cycle and fresh borrower consent.
How can a lender export proof of signing? Open the completed transaction in signNow and export the signed document with its audit trail or certificate of completion. Store both together under the lender’s approved retention policy; signNow provides evidence, but the lender determines the governing retention period.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.