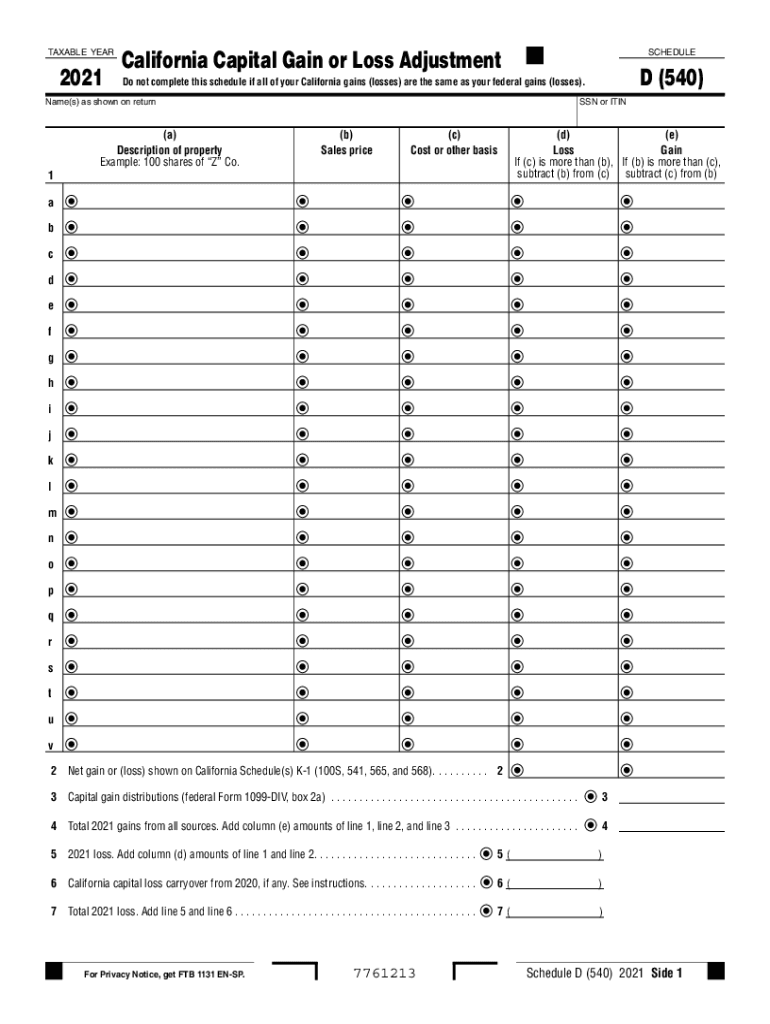
Schedule D 540 California Capital Gain Or Loss Adjustment Schedule D 540 California Capital Gain Or Loss Adjustment Form
Use a Schedule D 540 California Capital Gain Or Loss Adjustment Schedule D 540 California Capital Gain Or Loss Adjustment template to make your document workflow more streamlined.
What Schedule D 540 does
Schedule D 540 is California’s schedule for reporting capital gain or loss adjustments that affect an individual Form 540 return. It helps a filer reconcile California treatment with amounts reported from federal tax records, using transaction proceeds, basis, dates, and adjustment details where applicable. The completed schedule supports the California return rather than replacing Form 540 or federal reporting forms. A taxpayer or preparer reviews the calculations, signs the applicable return package, and retains the schedule with supporting records. California filing instructions control the required lines and attachments.
Who benefits from Schedule D 540
Schedule D 540 is most useful when California adjustments must be documented, reviewed, and retained with Form 540 filing records.
California individual taxpayers use Schedule D 540 to reconcile capital gains and losses reported on federal returns with California-specific adjustments when preparing Form 540 and supporting schedules electronically or on paper. Tax preparation firms use repeatable Schedule D 540 workflows to collect client transaction details, review California adjustments, and preserve signed preparation records alongside federal return documentation. Corporate and partnership tax departments use controlled document workflows when employees or authorized representatives review California capital gain or loss adjustments before filing the individual Form 540 package.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses Schedule D 540
Taxpayers and preparers
Individual California taxpayers and authorized preparers use Schedule D 540 to document capital gain or loss adjustments supporting Form 540. The schedule should be reviewed against federal transaction records and California instructions before the return package is finalized.
Tax and finance teams
Tax firms and finance teams use signNow to route the completed schedule for review, capture signatures where required, and preserve the signed PDF with its audit trail and supporting basis documentation.
How Schedule D 540 workflows work
A controlled digital workflow keeps the California schedule, review actions, and completed record connected from preparation through retention.
Upload form: Upload the Schedule D 540 PDF. Complete fields: Review detected fields and add California adjustment details. Send securely: Send the prepared schedule for authorized review or signature. Archive record: Store the completed file with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Complete Schedule D 540 online
Use these steps to prepare the California adjustment schedule while preserving the related review and signing record.
Upload form:
Upload the current Schedule D 540 PDF. Review fields:
Check fields against California instructions. Add adjustments:
Enter capital gain or loss adjustments. Send package:
Send for review and signature. Store records:
Download the completed schedule and audit trail.


Protect Schedule D 540 records
Data at rest:
Data in transit:
Security reporting:
Information security:
Electronic signatures:
California privacy:
Schedule D 540 filing challenges
Transcribing federal transaction totals without identifying California-specific adjustments can produce an inconsistent Schedule D 540 and Form 540 package. Missing basis statements, transaction dates, or sale proceeds makes capital gain and loss calculations difficult to substantiate during review. Using a prior-year schedule without checking the current California instructions can leave required lines or adjustment categories incomplete. Separating the signed schedule from the return and source records weakens the file’s audit-ready documentation.
Retain Schedule D 540 records
Keep the completed schedule, source statements, and signing evidence together for the applicable federal and California tax record period.
Keep supporting tax records
Apply extended IRS retention
Export audit evidence
Use secure archival storage
Schedule D 540 retention periods
Retention depends on the federal tax limitation period and the facts supporting the California capital gain or loss adjustment.
Three years after filing
Six years after filing
Indefinite for fraud cases
California period may differ
Supporting records retained
Schedule D 540 signing plan comparison
Pricing and feature information is shown only where verified for the listed vendors; unavailable competitor details are marked Not verified.
| Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|
| Business annual price | $8/user/month billed annually | Not verified | Not verified | Not verified | Not verified |
| Free trial | 7 days, no card required | Not verified | Not verified | Not verified | Not verified |
| Bulk send | Business Premium includes bulk send | Not verified | Not verified | Not verified | Not verified |
| Audit trail | Included with Business plan | Not verified | Not verified | Not verified | Not verified |
Schedule D 540 troubleshooting questions
These answers address field completion, electronic signing, plan selection, audit evidence, and retention for California Schedule D 540 workflows.
Upload the current Schedule D 540 PDF and inspect detected fields before entering transaction amounts. Auto-detection does not replace checking line labels against California filing instructions. Confirm that proceeds, basis, dates, and California adjustments appear in the intended fields before sending the document for review.
Business includes templates and audit trails, while Business Premium adds bulk send. For a single California schedule, Business may provide the relevant workflow; multiple similar client packages may justify bulk send. Plan limits and annual billing should be checked before deployment.
A signNow audit trail records signing activity, timestamps, and document history. Under ESIGN and UETA, enforceability also depends on intent, consent, attribution, and retaining a reproducible record. Preserve the completed Schedule D 540 and audit evidence with the tax file.
Consumer-facing electronic records require an ESIGN disclosure explaining the right to paper records, access to electronic records, and withdrawal procedures under 15 U.S.C. §7001(c). Apply that requirement when the signer is a consumer and the workflow falls within the statute.
The schedule supports Form 540 preparation but does not itself establish the correct tax result. Compare the completed amounts with federal source records and California instructions, then have the taxpayer or authorized preparer review the package before filing.
SignNow can store a completed PDF and its audit trail, but IRS retention depends on the tax facts. IRC §6501(a) generally uses three years from filing, six years for a 25% understatement, and indefinite retention for fraud or no return.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.