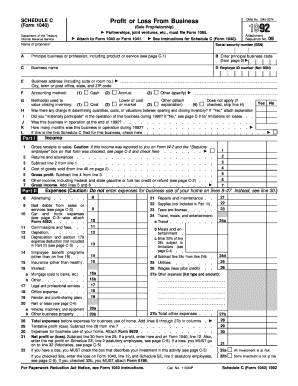
1992 Form 1040 Schedule C
Use a Form 1040 Schedule C template to make your document workflow more streamlined.
What the 1992 Form 1040 Schedule C reports
The 1992 Form 1040 Schedule C reports profit or loss from a sole proprietorship on an individual federal income tax return. It organizes business gross receipts, returns and allowances, cost of goods sold, business expenses, and net profit or loss. The filer totals the schedule and carries the resulting amount to Form 1040. Because this is a historical edition, compare each printed line and instruction with the records and filing year involved. IRS rules govern the tax treatment; signNow can help complete, sign, and retain the document electronically.
Key features of the 1992 Schedule C
The historical Schedule C combines business-income reporting with organized supporting evidence and a controlled electronic signing workflow.
Business income
Enter gross receipts, returns, allowances, and cost of goods sold using the line structure printed on the 1992 Schedule C. This keeps historical business revenue calculations connected to their supporting records.
Expense categories
Record deductible business expenses by the categories shown on the historical form, then retain invoices, receipts, and ledgers supporting each reported amount.
Historical layout
Upload the Schedule C to signNow and place fields over the historical form without changing its printed tax structure or line references.
Electronic signing
Send the completed document to the required signer, capture intent, and preserve the signed PDF with its completion certificate and audit trail.
Reusable template
Reuse a controlled template for recurring historical-record requests, while checking each taxpayer’s dates, business activity, and supporting documentation before sending.
Record retention
Export the completed form and signing evidence into the organization’s approved tax-record repository with access limited to authorized personnel.
Who uses the 1992 Schedule C
Tax preparation
Tax preparers and sole proprietors use the historical form for business-income and expense reporting, then preserve receipts, ledgers, and signed copies with restricted access.
Business records
Small-business administrators use signNow to route completed Schedule C records, collect signatures, and retain audit trails alongside supporting business documentation.
Who benefits from Schedule C workflows
The 1992 Form 1040 Schedule C serves historical sole-proprietor reporting, so workflows should separate taxpayer data, preparer review, and retained evidence.
Solo practitioners can upload a historical 1992 Schedule C, complete business-income and expense fields, and keep the signed PDF with supporting records for tax preparation and review. Tax and accounting firms can reuse a controlled Schedule C template, assign client fields, and preserve completion certificates while reviewing each taxpayer’s historical business activity separately. Small-business finance teams can route Schedule C approvals through signNow, connect storage or accounting systems, and limit access to personnel responsible for tax records.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Complete and sign the historical Schedule C
Follow the printed 1992 line structure first, then use signNow to route the completed document and preserve signing evidence.
Identify the form:
Confirm the filing year and business identity. Complete Schedule C:
Enter receipts, cost of goods, and expenses. Upload the document:
Upload the completed PDF to signNow. Finish the workflow:
Place fields, send, sign, and save evidence.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Platform requirements for Schedule C
Open the 1992 Form 1040 Schedule C workflow in Chrome or Edge on Windows, or Safari on macOS and iOS. The signNow mobile app supports Android, while secure TLS connections protect data in transit.
Desktop browsers Chrome and Edge on Windows Apple devices Safari on macOS and iOS Mobile app signNow mobile app for Android
Organizations should manage access through approved Windows, macOS, iOS, or Android devices and retain downloaded Schedule C records under the applicable IRS period. API, SSO, certificate, and long-term validation choices should follow the organization’s signNow plan and records policy.



Recommended Schedule C workflow setup
Use a controlled signing workflow that preserves the historical form, identifies the signer, and retains evidence under the applicable IRS period.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn eSignature |
| Audit trail | Enabled with completion certificate |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 |
Audit trail for a signed Schedule C
A signNow audit trail records the events surrounding completion of the 1992 Schedule C, creating a separate evidence record for review and retention.
Authenticate signer:
Record timestamps:
Seal document:
Store audit trail:
Export records:
Control access:
Retention schedule for Schedule C records
Keep the completed 1992 Schedule C with its supporting records for the applicable federal tax period. IRC §6501(a) supplies the baseline, with longer periods for substantial understatement, fraud, or an unfiled return.
3 years from filing
6 years for understatement
Indefinitely for fraud
Indefinitely without return
During applicable retention period
Best practices for Schedule C records
Accurate historical tax records depend on edition control, supporting evidence, and a retention process tied to IRS authority.
Verify the historical edition
Preserve supporting evidence
Apply IRS retention rules
Secure the archived record
Security for signed Schedule C records
Transport encryption:
Storage encryption:
Security certification:
Information security:
Electronic signatures:
Privacy controls:
Legal standing of the signed Schedule C
A completed 1992 Form 1040 Schedule C can support a business tax record when signer intent, attribution, consent, and reproducible retention are documented under ESIGN and applicable UETA rules. Those laws do not authorize electronic wills, court filings, or family-law decrees; tax filing requirements remain governed by the IRS.

Risks of incorrect Schedule C use
Incorrect business classification
Unsupported expense entries
Insufficient substantiation
Missed filing deadline
Resolve 1992 Schedule C workflow issues
These answers address historical Schedule C preparation, signer authentication, retention, and signNow plan limits without replacing IRS tax advice.
Upload the 1992 Schedule C PDF again and confirm it is readable. signNow Business supports document uploads, templates, and audit trails, but the IRS form’s historical layout may require manually placing fields after upload.
Review every imported line against the original 1992 form before sending. signNow can place fillable fields, but it does not determine whether historical business-income or expense amounts satisfy IRS substantiation rules.
Business includes legally binding eSignatures and audit trails. ESIGN and UETA establish electronic-signature validity when intent, consent, attribution, and record retention requirements are satisfied; they do not replace IRS filing rules.
Use signNow SMS authentication or stronger signer controls where available, and retain the completion certificate. The authentication record supports attribution, while IRC requirements still govern the underlying tax record.
Business is priced at $8 per user monthly with annual billing and includes 100 signature invites per user annually. Select Business Premium for bulk send when distributing repeated Schedule C workflows.
Export the completed PDF and audit trail, then retain them with supporting books. Federal tax records generally follow IRC §6501(a): three years from filing, six years for substantial understatement, or longer for fraud or no return.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.