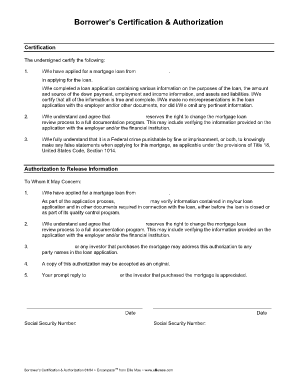
Borrower's Certification And Authorization Ellie Mae Form
Use a Borrower's Certification And Authorization Ellie Mae template to make your document workflow more streamlined.
What the borrower authorization form does
Borrower's Certification And Authorization Ellie Mae Form is a mortgage-borrower statement that confirms the applicant's information and authorizes the lender or designated parties to verify it. The borrower typically reviews identifying, employment, income, asset, debt, and property details, then certifies that the information is accurate and gives permission for verification. A lender may use the signed form during underwriting and loan processing. The exact fields and required signatures depend on the lender's version, so borrowers should follow the instructions attached to their loan application.
Who uses this borrower authorization form
Mortgage lenders
Mortgage lenders and loan processors use this form to document a borrower's certification and permission to verify application information. Their workflow may include the completed authorization, loan disclosures, income documentation, asset records, and underwriting correspondence. Before sending, staff should confirm that the lender's version contains every required field and signer.
Borrowers and representatives
Borrowers and authorized representatives review the form before signing, checking names, addresses, employment details, and other statements against the loan application. The completed record can accompany supporting documents such as pay records, bank statements, consent forms, and property-related paperwork, subject to the lender's instructions and applicable privacy controls.
Features that support mortgage processing
signNow organizes the lender’s borrower authorization from field preparation through signature collection and auditable record storage.
Field detection
Upload the lender-provided PDF and place borrower names, signatures, initials, and dates without rebuilding the document from scratch.
Signer routing
Route the authorization to each required borrower in a defined signing order, reducing missed assignments during loan processing.
Audit trail
Capture signer activity, timestamps, IP information, and completion history to support the lender’s record of execution.
Mobile signing
Let borrowers review and sign from a desktop or mobile device when the lender permits electronic execution.
Reusable template
Reuse an approved borrower authorization template while preserving the lender’s wording and required fields across loan files.
Secure records
Store the signed authorization with completion evidence so processors can retrieve the exact executed record during underwriting.
How this borrower form works
signNow turns the lender’s PDF into a controlled signing workflow while preserving the document and its execution history.
Upload form: Upload the lender-provided borrower authorization. Detect fields: Auto-detect and verify fillable fields. Send request: Assign borrowers and send securely. Complete record: Collect signatures and store the audit trail.
How to complete the borrower form
Use the lender-provided document, verify every borrower field, and preserve the signed record with its completion evidence.
Upload form:
Upload the lender’s version and let signNow detect fillable fields. Check fields:
Review borrower names, dates, and authorization language. Assign signers:
Assign signature and date fields to each borrower. Send request:
Send the form through signNow’s secure signing workflow. Save records:
Download the completed form and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.



Recommended setup for borrower authorizations
Configure the workflow around signer identity, lender recordkeeping, encryption, and controlled access to mortgage application information.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Retain completion certificate and action history |
| Document retention | Follow lender policy and applicable state law |
| Encryption | TLS 1.2/1.3 in transit and AES-256 at rest |
Security for borrower records
Encryption at rest:
Transport encryption:
Independent controls:
Security management:
Protected health data:
U.S. eSignatures:
Mobile access for borrower forms
Borrowers can use signNow mobile apps for iOS and Android to review and sign the lender’s authorization. The workflow uses encrypted connections, and the lender should confirm device access, app availability, and offline-signing requirements before sending sensitive loan records.
Mobile apps iOS and Android apps Offline signing Offline signing supported Document capture Camera document capture
A regulated lending operation should manage mobile access through its device, identity, and retention policies. Enterprise deployments can evaluate API access, SSO provisioning, and advanced signer authentication when the borrower authorization must connect with controlled loan-processing systems.
Best practices for this mortgage form
Accuracy, controlled signer assignment, and complete execution evidence help prevent delays when processing a borrower authorization.
Use the lender-approved document version
Reconcile fields before sending
Assign every required signer
Preserve execution evidence
Privacy and execution pitfalls
Sending the wrong lender version can omit required certifications, disclosures, or borrower fields and force the processor to restart the signing request. Unassigned signatures or dates leave the Borrower's Certification And Authorization Ellie Mae Form incomplete even when one borrower has already signed. Including unnecessary financial or identity information in shared copies increases exposure when access permissions are broader than the loan team requires. Failing to preserve the completed PDF and audit trail makes it harder to show who signed, when they signed, and which version they executed.
Limits and state-law issues
State rules may require separate acknowledgment
Excluded from ESIGN coverage
Certain decrees remain excluded
State recording rules still apply
What the audit trail records
The audit trail connects the borrower’s identity, signing events, document integrity, and completion evidence for the executed authorization.
Authenticate signer:
Record timestamp:
Hash document:
Seal history:
Track actions:
Export audit trail:
Processing stages for borrower authorization
The workflow has four operational stages; actual turnaround depends on document accuracy, signer availability, and lender review requirements.
Prepare document
Deliver to signers
Collect signatures
Archive completion
Troubleshooting borrower authorization workflows
Resolve field, consent, authentication, plan, and compliance questions before the signed authorization enters the loan file.
On the Business plan, signNow provides templates, audit trails, mobile apps, and legally binding eSignatures. If the lender needs bulk sending for repeated borrower packets, Business Premium adds that capability at $15/user/month when billed annually.
signNow supports ESIGN and UETA requirements, including signer intent, electronic consent, attribution, and record retention. For consumer-facing records, provide the required ESIGN disclosure and confirm that the borrower can access and retain the electronic record.
If a borrower cannot access the assigned field, check the recipient assignment and field type, then reopen the document in the editor. A signature field assigned to another borrower will not be available to the current signer.
The Business plan costs $8/user/month with annual billing and includes 100 signature invites per user per year. Additional invite charges may apply, so lenders should review expected volume before selecting a plan.
signNow offers SMS OTP and advanced signer authentication options. If the lender requires stronger identity proofing, confirm the selected plan and authentication configuration before sending the authorization to a borrower.
For loan files containing protected health information, signNow identifies HIPAA compliance as requiring a business associate agreement. The lender should execute the BAA and confirm that the workflow meets its privacy obligations before using the form.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.