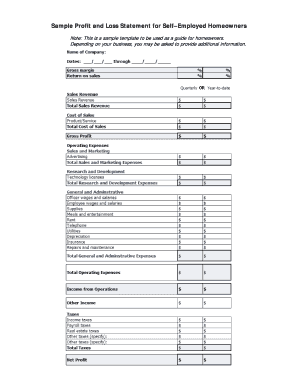
Profit And Loss Statement For Selfemployed Borrowers Form
Use a Sample Profit And Loss Statement For SelfEmployed Borrowers template to make your document workflow more streamlined.
What this borrower profit and loss form shows
A Profit And Loss Statement For Selfemployed Borrowers Form summarizes a self-employed applicant’s business income, expenses, and resulting profit or loss for a stated period. Borrowers complete the revenue and expense sections using business records, then provide the signed statement to a lender or other authorized reviewer. The form helps assess repayment capacity when traditional payroll records do not describe the applicant’s income. signNow can convert an uploaded form into a fillable workflow, route it to the borrower, capture an electronic signature, and preserve the completed document with an audit trail.
Business types that use borrower statements
Self-employed applicants use this statement to present business performance clearly when income comes from contracts, projects, commissions, or other non-payroll sources.
A solo consultant can list contract revenue, operating costs, and net profit to document self-employment income for a mortgage, personal loan, or business credit review. A real estate investor can separate rental-related revenue and expenses from other self-employed activity, giving a lender a clearer basis for evaluating recurring cash flow. A growing construction business can reuse an approved statement template, assign preparation and review permissions, and send completed borrower packages through a controlled signNow workflow.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features for completing borrower statements
The workflow focuses on accurate financial entries, clear signer attribution, and a retrievable record for the lender’s income review.
Income detail
Enter gross receipts and other business income for the reporting period, creating a structured view of revenue that a lender can review alongside supporting records.
Expense categories
Record operating expenses by category, helping separate business costs from personal spending and showing how reported revenue becomes net profit or loss.
Net result
Calculate the resulting profit or loss from the entered figures, giving reviewers a direct measure of the self-employed borrower’s reported business performance.
Fillable workflow
Upload the borrower statement to signNow and use detected or placed fields for names, dates, amounts, initials, and signatures without recreating the document.
Signature routing
Route the completed statement to the borrower or reviewer by email, signing link, or configured workflow, with each action recorded for later review.
Audit history
Keep the signed statement and completion history together so the borrower, lender, or authorized administrator can retrieve the executed record when needed.
Technical requirements for completing the form
The form can be prepared in a current Chrome, Firefox, Safari, or Edge browser on Windows or macOS. signNow mobile apps support iOS and Android, while encrypted connections use TLS for data in transit.
Browser support Chrome, Firefox, Safari, and Edge Operating systems Windows, macOS, iOS, and Android Supported devices Desktop, tablet, and mobile signing
Organizations handling borrower financial information should use managed Windows, macOS, iOS, or Android devices, current browser versions, and controlled user access. Teams connecting signNow to a loan, accounting, or document system should separately configure API access, SSO provisioning, and retention controls.
Legal standing of the signed statement
A completed borrower profit and loss statement can document the signer’s reported business income and expenses when the lender accepts it. Under ESIGN and applicable UETA rules, an electronic signature generally cannot be denied legal effect solely because it is electronic, provided intent, consent, attribution, and record retention requirements are met.

 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How this statement workflow works
The signNow process turns the borrower’s existing financial statement into a controlled sequence from upload through signed-record storage.
Upload document: Upload the borrower’s original profit and loss statement to signNow. Check detected fields: Auto-detect fillable fields, then verify income, expense, date, and signature placement. Send for signature: Send the prepared statement to the borrower for review and electronic signature. Store completed record: Store the executed statement with its completion certificate and audit trail.
Recommended setup for this borrower form
Use a controlled workflow that separates preparation, borrower review, signature, audit evidence, and record retention.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture IP, timestamps, and action history |
| Document retention | Apply lender policy and IRC §6501(a) |
| Encryption | TLS in transit and AES-256 at rest |



What the audit trail records
For this borrower statement, the audit trail connects the financial document, signer activity, and completed signature record without replacing lender verification.
Authenticate signer:
Timestamp actions:
Hash document:
Seal evidence:
Control access:
Export history:
Processing stages for borrower statements
No universal filing deadline applies to this lender-specific statement; timing depends on the requesting institution and the borrower’s review cycle.
Prepare the statement
Deliver to signers
Review and sign
Archive the record
Retention rules for signed statements
Retention depends on whether the statement supports tax records, lending records, or another regulated file; confirm the controlling purpose before deletion.
3 years from filing
6 years for omission
Indefinitely for fraud
Lender policy period
Longer applicable period
Best practices for accurate statements
Accuracy, signer attribution, controlled access, and retention decisions should be handled together when preparing this self-employed borrower document.
Reconcile each financial entry
Separate preparation and signing fields
Archive the signed package
Restrict financial information access
Privacy pitfalls in borrower statements
Including a full Social Security number or unnecessary bank-account details can expose sensitive borrower information beyond what the lender needs. Sending the statement before obtaining electronic consent can weaken the record of the borrower’s agreement to receive and sign electronically. Giving every team member edit access can allow unreviewed changes to revenue, expenses, or net profit figures. Using an unrestricted signing link can disclose a borrower’s financial information to an unintended recipient.
Security controls for financial documents
Transport encryption:
Stored encryption:
Security reporting:
Information security:
Electronic signatures:
Protected information:
Troubleshooting borrower statement workflows
Resolve field, delivery, authentication, plan, evidentiary, and electronic-consent questions before relying on a signed borrower statement.
Upload the original PDF again and confirm that required fields are placed on the correct income, expense, and signature lines. signNow Business includes templates and audit trails, but the sender remains responsible for checking field placement before delivery.
Confirm that the borrower’s email address is correct, then resend the invitation or provide a signNow signing link. The signer may not need a signNow account, depending on the workflow, but must complete every required field before signing.
Use SMS OTP or another configured authentication method when the lender requires stronger attribution. signNow supports signer authentication options, while ESIGN and UETA focus on intent, consent, attribution, and record retention rather than prescribing one universal method.
The Business plan is listed at $8 per user per month with annual billing and includes 100 signature invites per user per year. Business Premium adds bulk send at $15 per user per month annually; confirm current overage terms before deployment.
A signed statement is not automatically an IRS filing or proof of income. The borrower and lender should verify entries against source records and follow the requesting institution’s requirements; IRS record rules apply only when the document supports a tax record.
For consumer-facing electronic records, review the ESIGN consumer-disclosure requirements in 15 U.S.C. §7001(c), including access to electronic records and paper-record rights. Configure signNow consent and retention procedures before asking a consumer borrower to sign.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.