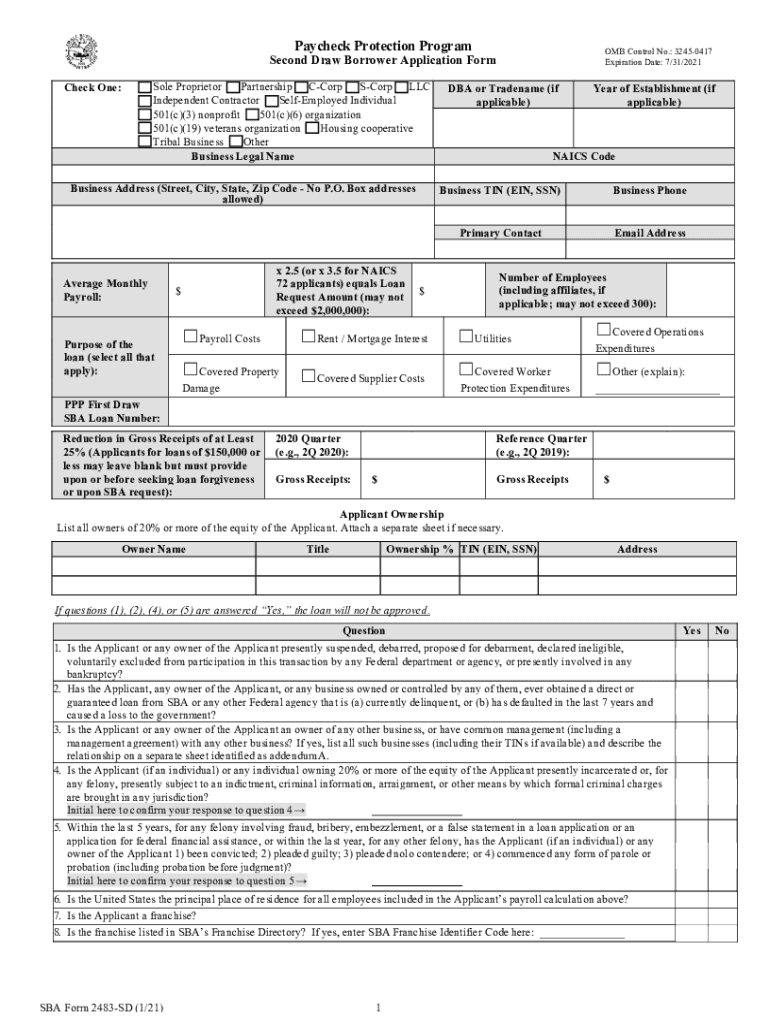
Second Draw Borrower Application Form
Use a Second Draw Borrower Application Form template to make your document workflow more streamlined.
What this borrower application does
The Second Draw Borrower Application Form is a lender-facing document used to collect a business borrower’s identifying, financial, ownership, and certification information for a second-draw financing request. The applicant reviews the lender’s questions, completes required fields, and signs the borrower certifications. With signNow, a sender uploads the form, reviews auto-detected fields, assigns signers, and sends it electronically. The completed PDF and audit trail can then be stored together for lender review and controlled record access.
Who uses this borrower application
Small businesses
Small-business borrowers use the application to provide lender-requested ownership, revenue, payroll, and certification information in one controlled record.
Lender teams
Lenders and financial-services teams use the form to collect authorized signatures, preserve borrower statements, and organize completed applications for review.
Business types using the application
The Second Draw Borrower Application Form fits borrower, lender, and finance workflows that require signed business information and traceable records.
A small business owner can complete borrower certifications and sign the application remotely, keeping lender-requested information in one structured document instead of exchanging disconnected attachments. A financial-services team can use a controlled template to collect multiple borrower applications, route each document to its authorized signer, and preserve audit evidence for review. An enterprise finance department can connect signNow with NetSuite or Microsoft Dynamics 365 to coordinate application records with existing financial workflows and access controls.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features that support borrower applications
signNow organizes the Second Draw Borrower Application Form around field accuracy, signer attribution, audit evidence, and controlled storage.
Field detection
Auto-detected fields help convert the uploaded borrower application into a structured signing workflow, reducing manual placement of signature, date, and certification fields before delivery.
Signer routing
Role-based routing sends borrower certifications to the authorized applicant and prevents unrelated recipients from signing fields assigned to another party.
Reusable template
A reusable template keeps lender instructions and recurring application fields consistent while allowing each borrower’s financial information to remain record-specific.
Audit trail
Audit trails record signing events, timestamps, and signer activity, giving lender teams evidence connected to the completed Second Draw Borrower Application Form.
Mobile signing
Mobile apps let borrowers review and sign the application from a supported device when desktop access is unavailable, without changing the underlying document.
Record storage
Completed files and signing evidence can be retained together, supporting controlled retrieval when a lender, borrower, or records administrator needs the executed application.
Recommended application setup
Prepare the Second Draw Borrower Application Form with clear signer identity, attributable signatures, audit evidence, and restricted record access.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Enable complete event history |
| Document retention | Retain with related tax records |
| Encryption | TLS 1.2/1.3 and AES-256 protection |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How the application workflow works
The signNow workflow moves the Second Draw Borrower Application Form from document preparation through verified signing and organized record storage.
Upload form: Upload the lender’s application template to signNow. Review fields: Auto-detect fillable fields and review borrower data. Send application: Send certifications and signature fields to authorized signers. Archive record: Store the completed PDF with its audit trail.
Complete the application in signNow
Use this sequence to prepare, route, sign, and retain the Second Draw Borrower Application Form.
Upload form:
Upload the completed lender template. Check fields:
Review detected borrower fields. Assign signers:
Assign each signer’s fields. Send request:
Send the application securely. Store copy:
Download the signed record.
What the audit trail records
The audit trail separates signing evidence from the borrower’s application answers and helps show how the executed record was created.
Authenticate signer:
Timestamp action:
Hash document:
Seal record:
Log activity:
Export trail:
Security for borrower applications
Transport encryption:
Stored encryption:
Control assurance:
Security management:
Signature compliance:
Healthcare safeguards:
Privacy and disclosure pitfalls
Borrower tax and payroll information can appear in signed files; restrict access and avoid sending completed applications through unsecured channels. Consumer-facing signing requires clear electronic-record consent, paper-access disclosure, and withdrawal procedures under 15 U.S.C. §7001(c). A shared application template can expose one borrower’s financial details to another recipient when signer roles or permissions are configured incorrectly. Delegated sending without review can leave borrower certifications, ownership details, or lender-required fields incomplete before signature.
Best practices for completing the application
Accuracy, signer attribution, consent, and controlled retention matter when preparing a Second Draw Borrower Application Form for lender review.
Verify borrower information before sending
Separate fixed fields from borrower data
Document electronic-record consent clearly
Archive the signed record with evidence
Legal standing for borrower records
A completed Second Draw Borrower Application Form can support a U.S. business transaction when the signer demonstrates intent, consents to electronic records, can be identified, and the record remains reproducible. ESIGN and applicable UETA rules recognize qualifying electronic signatures, but they exclude wills, certain court orders, and specified family-law records.

Risks from improper completion
Missing borrower attestations
Signer attribution gap
Unavailable audit evidence
Unauthorized application access



Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting the borrower application
Resolve field, signer, compliance, plan, and record-handling issues without changing the borrower’s executed information outside the documented workflow.
Upload the lender-provided Second Draw Borrower Application Form again, then confirm the file opens correctly before placing fields. signNow’s Business plan includes templates and audit trails, but field detection still requires a sender review before delivery.
Open the recipient settings and confirm the email address, signer order, and assigned fields. A borrower can often sign as a guest through the invitation, while SMS authentication can add an identity check when the workflow requires it.
Use the signNow Business plan for standard electronic signatures and audit trails at $8/user/month when billed annually. Business Premium is $15/user/month annually and adds bulk send for repeated application workflows.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record reproducibility are established. For consumer-facing records, provide the electronic-record disclosure and paper-access procedures required by 15 U.S.C. §7001(c).
Review the signer assignments before resending. If a borrower completed the wrong field, void or correct the transaction according to the lender’s process rather than editing the executed PDF without an explanatory record.
Download the completed application and its audit trail together from signNow, then apply the organization’s restricted-record policy. Tax-related records may require three years from filing under IRC §6501(a), with longer periods in specified circumstances.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.