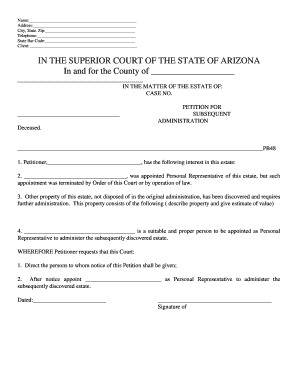
Petitioner, Has The Following Interest In This Estate Form
Use a Petitioner,, Has The Following Interest In This Estate template to make your document workflow more streamlined.
What this estate-interest form does
The Petitioner, Has The Following Interest In This Estate Form records a petitioner’s stated interest in a particular estate for review by the people or authority handling that matter. The form is not, by itself, a will, codicil, court order, deed, or probate decision. A petitioner enters the requested matter and interest information, signs where required, and provides supporting records under applicable state procedure. signNow can upload the form, identify fillable fields, route it to signers, capture an audit trail, and preserve the completed record. State law controls admissibility and execution requirements.
Who benefits from this estate form
The form is most useful where a petitioner’s claimed estate interest must be collected, signed, and preserved alongside supporting probate records.
Solo probate attorneys and fiduciary administrators can use the form to collect a petitioner’s stated estate interest, supporting details, and signature before assembling a review-ready matter file. The workflow separates the petitioner’s declaration from the legal determination made under applicable state probate procedure. Probate departments and estate-services teams can use reusable signNow templates to route identical estate-interest forms to petitioners, reviewers, or witnesses. Administrators can control access, preserve completion evidence, and connect the signed record to the matter’s document repository. Enterprise legal operations teams can standardize estate-interest intake across offices while assigning sending and review permissions. Shared templates reduce retyping, delegated sending supports workload distribution, and audit trails help reviewers verify the form’s signing history.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the estate form workflow works
The signNow workflow moves this petitioner’s estate-interest form from upload through field preparation, signing, and evidence preservation.
Upload form: Upload the estate-interest form into signNow. Prepare fields: Auto-detect fillable fields and place signature fields. Route for signing: Add the petitioner and other required signers. Archive record: Store the completed form with its audit trail.
Review the estate form audit trail
The audit trail records who handled the petitioner’s estate-interest form, what happened, and when each signing event occurred.
Authenticate signer:
Capture timestamp:
Hash document:
Seal completion:
Track activity:
Export audit trail:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Preserve estate-interest records carefully
A clear retention and archival process helps preserve the petitioner’s stated interest, supporting evidence, and signing history for later review.
Confirm the governing retention rule
Save the audit trail
Limit estate-file access
Preserve the original record
Retention rules for related records
This form has no supplied universal retention period. Apply the rule governing the estate matter and any supporting records attached to it.
Court or state schedule
Three years for tax records
Six years for understatement
Six years for HIPAA
Three years or termination
Check state-specific estate rules
Missing notarization
Will or codicil
Court order
Real-estate deed
Avoid privacy and disclosure mistakes
Personal addresses, beneficiary references, and estate details may be exposed when the completed form is emailed without access restrictions or a controlled recipient list. A petitioner may sign without receiving the electronic-record disclosure required for a consumer-facing transaction under 15 U.S.C. §7001(c). Sending the form to the wrong reviewer can disclose estate information and undermine the matter’s confidentiality controls. Replacing the signed PDF without preserving the audit trail can make it harder to demonstrate who signed, when, and what record was completed.
Protect estate-interest information
Encryption:
Security report:
Information security:
Electronic signatures:
Protected health information:
Transport and storage:



Troubleshoot estate-interest form signing
These answers address execution, scope, authentication, consent, and recordkeeping questions that can arise when completing this estate-interest form.
An estate-interest form may involve wills, codicils, court filings, or other excluded records. ESIGN and UETA do not override those exclusions. Confirm the document’s legal category and state requirements before sending it through signNow; obtain attorney or court guidance when the form affects probate rights.
The form’s title identifies a petitioner’s claimed interest, but it does not establish that interest by itself. Attach or reference the supporting probate, trust, property, or court records required by the relevant jurisdiction. signNow can preserve the completed form and audit trail, not determine legal entitlement.
If a notary, witnesses, or in-person appearance is required, configure the process accordingly and do not treat an ordinary electronic signature as a substitute. State law controls execution formalities. signNow’s audit trail can document a signing event, but it cannot waive a statutory notarization requirement.
Use signNow’s Business plan for templates, legally binding eSignatures, and audit trails. Business Premium adds bulk send and kiosk mode, while Enterprise adds advanced signer authentication. Select the plan based on the number of petitioners and the authentication level required by the matter.
For a consumer-facing estate transaction, provide the electronic-record disclosure required by 15 U.S.C. §7001(c), confirm the signer can access the record, and explain how consent may be withdrawn. The audit trail supports evidence, but it does not replace the required disclosure process.
Export the completed PDF and audit trail from signNow, then store them with the estate file under access controls. No universal retention period applies to this unnamed estate-interest form; follow the probate court, state law, fiduciary duty, or organizational schedule governing the matter.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.