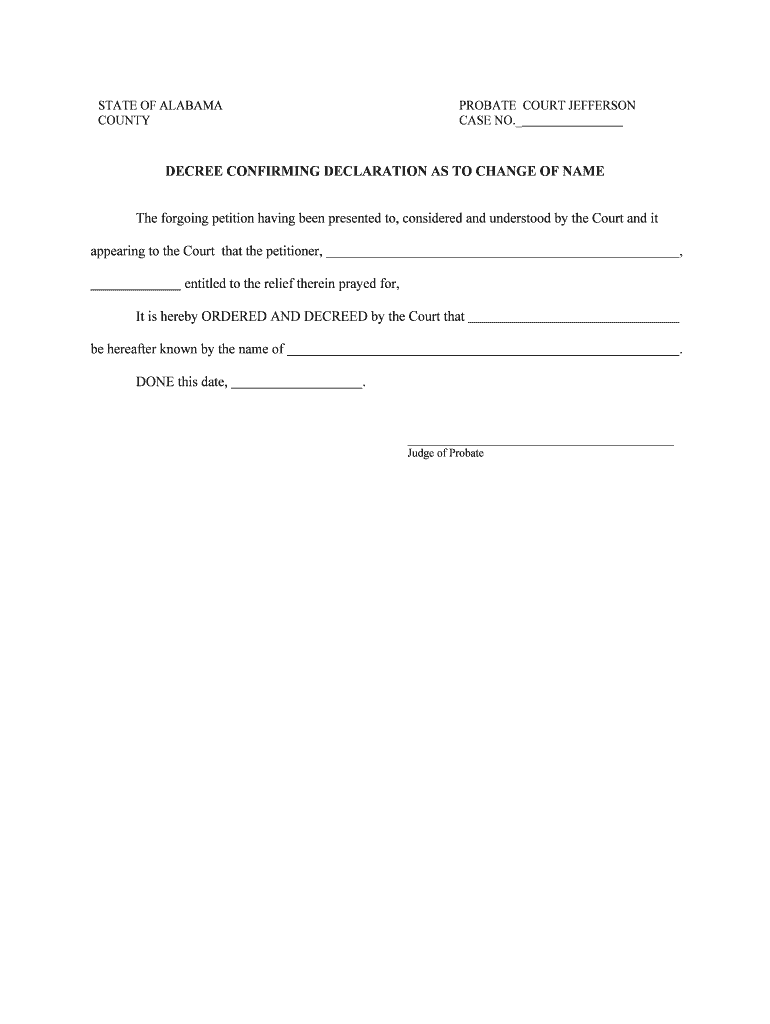
In Re Alan L King, In His Official Capacity As Judge Of Probate Form
Use a In Re Alan L King, In His Official Capacity As Judge Of Probate template to make your document workflow more streamlined.
What this probate form does
The In Re Alan L King, In His Official Capacity As Judge Of Probate Form is a probate-related court document concerning Alan L. King in his official capacity as judge of probate. Its purpose, required fields, signature method, filing destination, and deadline depend on the issuing probate court and the specific proceeding. Review the court’s instructions before completing it. Electronic signatures may be recognized under the federal ESIGN Act, 15 U.S.C. chapter 96, and applicable state law, but those rules do not override exclusions for wills, court orders, or official court filings.
Who works with this probate form
Probate attorneys
Probate attorneys can prepare the form, route it to authorized parties, and preserve completion evidence while following the issuing court’s filing instructions.
Court administrators
Court administrators can coordinate document routing and access controls, but must confirm whether the clerk requires an original, notarization, or court portal submission.
How the probate workflow works
Use this sequence to prepare the named probate form while keeping court acceptance separate from electronic signing.
Upload form: Upload the court-provided probate form. Check fields: Review detected fields and add only required recipients. Route signatures: Send the prepared document to authorized signers. Preserve record: Store the signed form with its audit trail.
Prepare and route this probate form
Follow the document-specific workflow below, then verify whether the probate court requires separate paper filing, notarization, or personal submission.
Upload form:
Upload the court-provided form to signNow. Review fields:
Check auto-detected fields against court instructions. Assign signers:
Assign each required signer and signing order. Complete record:
Send, monitor, and preserve the audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Review the audit trail for this form
The audit trail preserves who handled this probate form, what occurred, and when each signing event was recorded.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Log actions:
Export evidence:
Check exclusions before signing
Notarization requirement
Wills excluded
Court filing
Real-estate deeds
Legal standing and court acceptance
Electronic signing can support intent, attribution, record integrity, and reproducibility under ESIGN and applicable state law. Those frameworks do not make wills, codicils, testamentary trusts, court orders, or official court filings automatically e-signable. For this probate form, the issuing court’s rules determine whether an electronic record is accepted.

Keep probate records complete and controlled
Accurate version control, court-specific retention, and a preserved audit trail help distinguish a completed electronic workflow from an accepted probate filing.
Verify the court’s current form version
Export the completed record and audit trail
Match retention to the underlying record
Limit access before sending
Retention periods for related records
Retention depends on the probate court’s instructions and the record’s actual legal or business category; do not apply an unrelated schedule automatically.
Court-directed period
Three years tax records
Six years understated income
Six years HIPAA records
Seven years SOX records
Avoid probate privacy and filing mistakes
The form may contain names, case information, addresses, or other personal data that should not be shared beyond authorized probate participants. A signer may consent to electronic delivery without understanding that the court separately requires paper, notarization, or a designated filing portal. Broad workspace permissions can expose a probate record to staff who do not need access for preparation, review, or filing. Sending an outdated court version can create mismatched captions, missing instructions, or rejection when the clerk reviews the submission.
Troubleshoot probate form workflows
Use these answers to separate signNow workflow issues from requirements imposed by the probate court, state law, or the document’s legal classification.
Business includes legally binding eSignatures, templates, audit trails, and mobile apps. If the probate court requires an original, notarization, or an official filing method, signNow cannot replace that court-specific requirement; confirm acceptance with the clerk before sending.
signNow records intent, signer attribution, timestamps, and the completed document’s history. ESIGN and UETA generally recognize qualifying electronic signatures, but court rules and exclusions for official court filings can control whether this particular probate document is accepted.
Business Premium adds bulk send and kiosk mode, while Enterprise adds advanced signer authentication and conditional or formula fields. A single probate form usually needs neither unless an organization manages repeated, structured filings.
Use signNow’s audit trail to review invitations, signer actions, timestamps, and completion evidence. Export the completed form and audit record together, then retain them under the probate court’s instructions and applicable records policy.
Consumer-facing electronic records may require an ESIGN disclosure explaining paper access and withdrawal procedures under 15 U.S.C. §7001(c). Capture consent before signing when the signer is a consumer rather than a represented organization.
HIPAA compliance applies when the workflow contains protected health information and requires a business associate agreement. A probate filing does not automatically create HIPAA obligations; classify the information and parties before selecting that control.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.