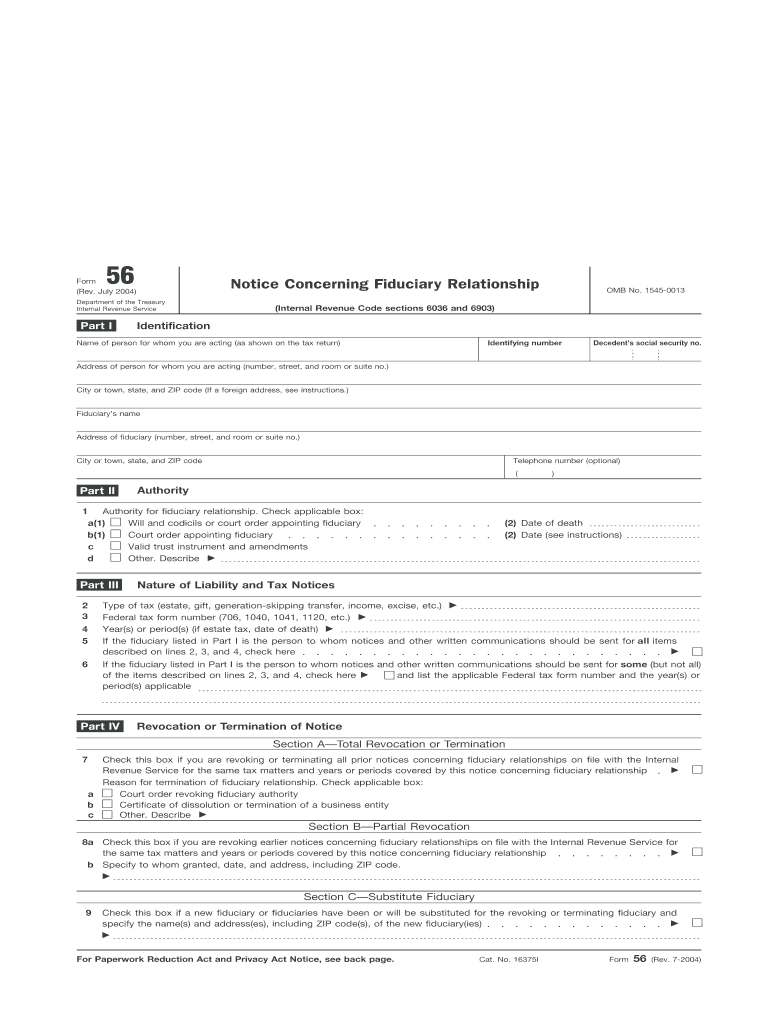
Form 56 Rev 7 2004 Notice Concerning Fiduciary Relationship IRS
Use a Irs Form 56 template to make your document workflow more streamlined.
What Form 56 does
Form 56 Rev 7 2004 Notice Concerning Fiduciary Relationship is an IRS notice used to identify a fiduciary relationship and the person authorized to act for a taxpayer, estate, trust, or other person or entity. It records the fiduciary’s authority, the taxpayer’s identifying information, and relevant dates so IRS correspondence can be directed appropriately. The form does not itself create fiduciary authority; that authority comes from the underlying appointment, trust, court order, power of attorney, or applicable law. Complete it accurately, sign it, retain evidence, and follow current IRS submission instructions.
Who benefits from Form 56 workflows
Form 56 is most useful when a fiduciary relationship requires clear authority, accurate IRS correspondence, and a reproducible signed record.
Solo tax practitioners can prepare a fiduciary notice for an estate, trust, or individual taxpayer, route it to the authorized fiduciary, and keep the signed PDF with the client’s tax records. Estate and trust administrators can standardize Form 56 templates, assign role-based signing fields, and preserve evidence when responsibility changes or IRS correspondence must be handled by a fiduciary. Accounting and legal departments can coordinate Form 56 preparation across offices, use controlled templates, and connect signed records to existing tax files without treating signNow as the IRS filing channel.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How Form 56 works in signNow
Use signNow to prepare the IRS notice, route it to the person authorized to sign, and preserve evidence of the completed document without treating the platform as an IRS filing service.
Upload form: Upload the IRS Form 56 Rev 7 2004 PDF to signNow. Check fields: Review detected fields and add missing fiduciary or taxpayer fields. Assign roles: Assign signature and date fields to each authorized signer. Complete record: Send, sign, and retain the completed record with its audit trail.
Complete Form 56 online
Prepare Form 56 in signNow, verify the fiduciary relationship, obtain the required signature, and preserve the completed record before following IRS submission instructions.
Upload form:
Upload the official IRS Form 56 PDF. Review details:
Check taxpayer and fiduciary information carefully. Assign fields:
Add authorized signer and date fields. Send document:
Send the notice for signature. Save evidence:
Export the signed record and audit trail.
What the Form 56 audit trail records
A signNow audit trail documents the electronic signing event around Form 56 without replacing the IRS authority that governs the fiduciary notice.
Authenticate signer:
Capture timestamp:
Preserve document:
Record actions:
Export evidence:
Archive record:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended Form 56 workflow setup
Configure Form 56 Rev 7 2004 workflows around signer attribution, IRS recordkeeping, and a separately controlled submission process.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS verification |
| Signature type | Electronic signature with signer intent |
| Audit trail | Export completion certificate and action log |
| Document retention | Retain under IRS record policy |
| Encryption | TLS 1.2/1.3 and AES-256 |
Technical requirements for Form 56
Complete Form 56 Rev 7 2004 in signNow through Chrome, Firefox, Safari, or Edge on Windows or macOS; iOS and Android mobile apps are also available. signNow encrypts data in transit with TLS 1.2/1.3 and at rest with AES-256.
Desktop browsers Chrome, Firefox, Safari, Edge Operating systems Windows, macOS, iOS, Android Secure connection TLS 1.2/1.3 and AES-256
A fiduciary office can use managed Windows or macOS devices, mobile access on iOS or Android, and organization-controlled signNow accounts. Enterprise deployments may connect API access, SSO provisioning, and retention controls to existing compliance procedures; confirm the IRS filing method separately because signNow does not submit Form 56 to the IRS.



Legal standing of Form 56 records
Form 56 identifies a fiduciary relationship for IRS administration; its evidentiary value depends on accurate information, signer intent, attribution, and retained records. ESIGN and UETA generally recognize qualifying electronic signatures, but they do not replace IRS filing rules or authorize electronic execution of excluded documents such as wills, codicils, and certain court filings.

Form 56 completion and filing stages
Form 56 has no universal signNow turnaround deadline; review the IRS instructions and any event-driven filing requirement before submission.
Prepare the notice
Deliver to signer
Complete signature
Archive and submit
Form 56 record retention schedule
Form 56 should be retained with the related tax records and fiduciary-authority evidence; the applicable period depends on the underlying IRS matter.
Three years from filing
Six years for major understatement
Indefinite for fraudulent returns
Indefinite without a return
Longer period when required
Recordkeeping practices for Form 56
Form 56 records should remain linked to the fiduciary authority and the tax account they describe, with an exportable signing history.
Match retention to the underlying tax record
Export the audit trail with Form 56
Restrict access and secure archived records
Document changes to fiduciary authority
Risks of inaccurate Form 56 filing
IRS correspondence misdirected
Relationship timing unclear
Account matching delayed
Signer attribution weakened
Authentication for Form 56 signers
Signer access:
Second factor:
Action history:
Signing evidence:
Identity review:
Digital signature:
Avoidable Form 56 preparation errors
Entering an outdated fiduciary appointment date can make the IRS notice inconsistent with the underlying court order, trust instrument, or authorization. Failing to identify the taxpayer, fiduciary, or fiduciary relationship precisely can delay IRS correspondence and create uncertainty about who may act. Submitting Form 56 without supporting authority may leave the IRS unable to connect the fiduciary relationship to the taxpayer account. Using an unreviewed scan can hide missing signatures, incomplete addresses, or incorrect account details before the notice reaches the IRS.
Form 56 troubleshooting questions
Resolve Form 56 preparation issues by separating signNow workflow questions from IRS filing and fiduciary-authority requirements.
Upload the official Form 56 Rev 7 2004 PDF again, then inspect detected fields manually. signNow’s Business plan includes templates and audit trails, but field detection does not determine whether the IRS form is legally complete.
Use the signer’s individual email, assign every signature and date field, and require review before sending. signNow records signer actions and timestamps, supporting attribution under ESIGN and UETA when intent and consent are established.
Business provides legally binding eSignatures and audit trails. Business Premium adds bulk send, while Enterprise adds advanced signer authentication. Select the plan based on volume and authentication requirements, not on IRS approval.
signNow can create the completed electronic record, but Form 56 filing instructions come from the IRS. Download the signed PDF and audit trail, then use the IRS-directed submission method for the fiduciary notice.
For consumer-facing electronic records, obtain the disclosure and consent required by ESIGN, including access to the electronic format and withdrawal procedures under 15 U.S.C. §7001(c). Business workflows should document that consent before signing.
Keep Form 56, supporting fiduciary authority, the completion certificate, and the audit trail together. IRS record rules vary by record type; tax records generally follow IRC §6501(a), including three years from filing or longer stated exceptions.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.