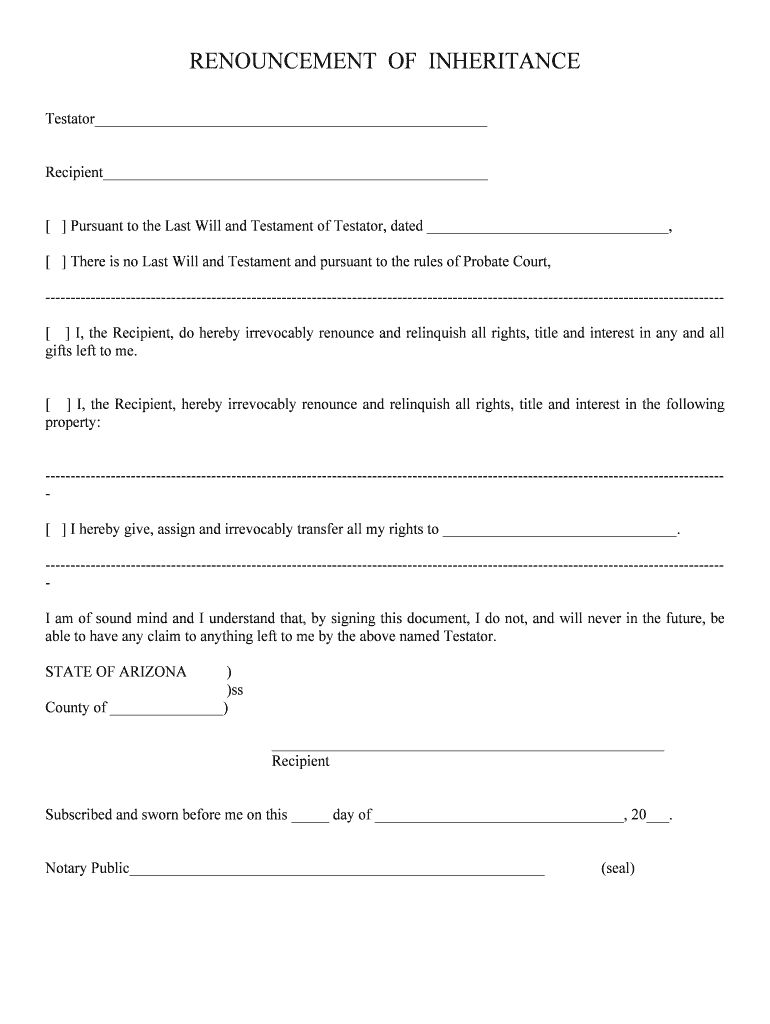
Handling A Predeceased Beneficiary's Share Of An Estate Form
Use a Handling A Predeceased Beneficiary's Share Of An Estate template to make your document workflow more streamlined.
What this estate share form does
Handling A Predeceased Beneficiary's Share Of An Estate Form records how an estate should address a beneficiary who died before receiving or taking an expected share. It can identify the deceased beneficiary, successor or surviving beneficiaries, estate representative, governing instrument, calculated distribution, and required acknowledgments. The form organizes evidence for review and signatures; it does not itself amend a will, create a testamentary trust, or replace a probate court order. State succession law, the will or trust, and court instructions determine whether the proposed allocation is authorized.
Who uses this estate share form
Probate administration
Personal representatives and probate attorneys use the form to document the deceased beneficiary, successor interest, calculated share, and acknowledgments before distributing estate assets.
Trust and accounting
Trust administrators and estate accountants use the form alongside the governing instrument and accounting records to coordinate beneficiary review without replacing required court or notary procedures.
How this estate share form works
The signNow workflow moves the estate-share document from preparation through field review, signer completion, and evidence preservation.
Upload form: Upload the completed estate-share form. Check fields: Auto-detect fields and review placement. Send for signing: Send assigned fields to beneficiaries. Archive evidence: Store the signed record and audit trail.
Steps to complete the estate share form
Prepare the estate facts first, then use signNow to place fields, route signatures, and preserve the completed evidence.
Upload:
Upload the estate-share form PDF. Review fields:
Review auto-detected beneficiary fields. Assign signers:
Assign each signer’s required fields. Send:
Send and track completion. Store records:
Download the signed PDF and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How the audit trail records estate actions
The audit trail connects each beneficiary-share form action to signer identity, timing, document integrity, and retrievable completion evidence.
Signer authentication:
Timestamp capture:
Document hashing:
Tamper-evident sealing:
Activity history:
Audit export:
Legal standing of the estate share form
This form can document a beneficiary-share instruction or acknowledgment when the parties show intent, consent to electronic records, signer attribution, and reliable retention under ESIGN and applicable state law, including UETA or New York ESRA. It does not replace a will, codicil, testamentary trust, court order, or official court filing, which remain subject to specialized probate requirements.

State rules and excluded documents
Notarization
Wills
Court orders
Real-estate deeds
Best practices for completing the estate form
Accuracy depends on matching the beneficiary record, succession authority, share calculation, signer sequence, and retained evidence.
Verify the succession facts before completing
Assign each required signer explicitly
Review share calculations against estate records
Preserve the signed record with evidence
Retention periods for related estate records
Retention depends on the record’s legal purpose, not merely its use in an estate-share workflow. Apply the authority that actually governs the record.
Three years: tax records
Six years: HIPAA records
Six years: broker records
Three years: payroll records
Five years: injury records
Recommended setup for the estate form
Configure the estate-share workflow around signer identity, attribution, audit evidence, encryption, and the retention rule governing the underlying record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS verification |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps, IP, and actions |
| Document retention | Apply the governing record schedule |
| Encryption | Use TLS 1.2/1.3 and AES-256 |
Security controls for estate share forms
Stored data:
Data in transit:
Security certification:
Information security:
Privacy compliance:
Electronic signatures:
Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting estate-share form completion
Resolve field assignment, signer identity, electronic consent, plan selection, and record-preservation questions before relying on the completed estate document.
Upload the estate-share PDF to signNow, then review auto-detected fillable fields before sending. The Business plan includes templates and audit trails, helping preserve the document structure and signing evidence for later estate-file review.
Use separate signNow roles for the personal representative, successor beneficiary, and any required acknowledgment signer. Confirm that each field is assigned before sending; unassigned fields can prevent completion or leave attribution unclear.
Business is listed at $8/user/month when billed annually and includes legally binding eSignatures and audit trails. Business Premium is $15/user/month annually and adds bulk send and kiosk mode.
signNow states ESIGN and UETA compliance, but those laws do not cover wills, codicils, testamentary trusts, or official court filings. Obtain probate counsel’s direction when the form is part of those documents.
For consumer-facing records, ESIGN requires disclosure of the right to paper, electronic-access capability, and withdrawal procedures under 15 U.S.C. §7001(c). Configure the disclosure before sending when the beneficiary acts as a consumer.
Export the completed PDF and audit trail from signNow after all assigned fields are complete. Store both with the estate file; the legal retention period depends on the record’s purpose and applicable state or federal authority.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.