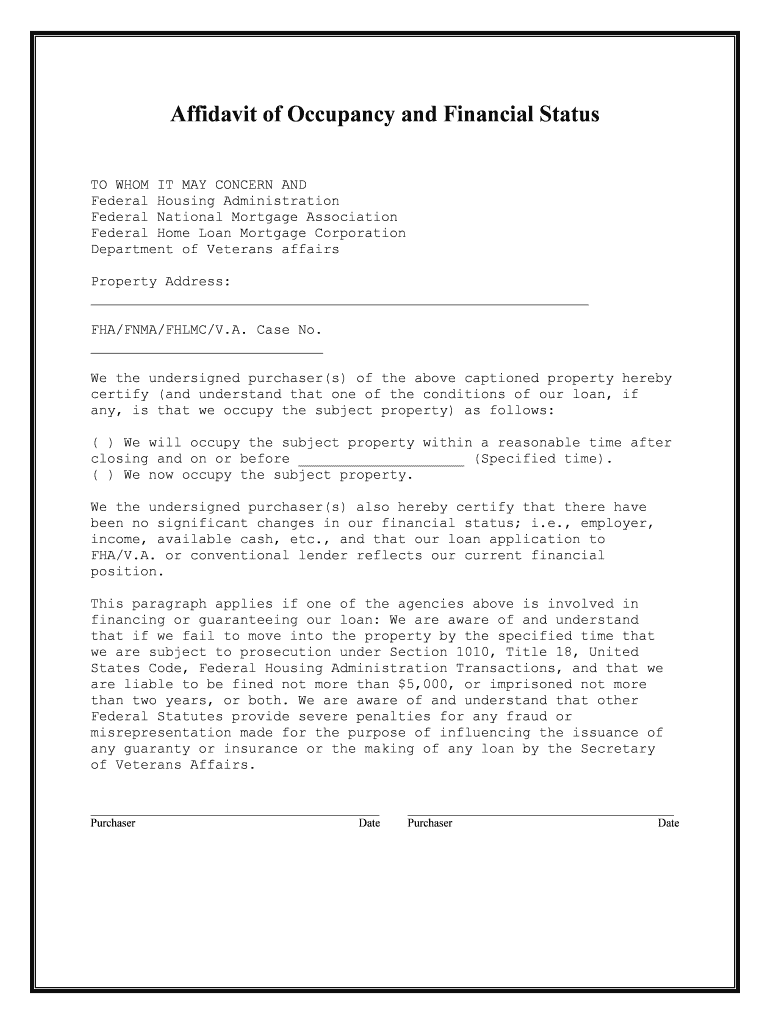
What Is The Difference Between A Conventional, Fha, And VA Form
Use a What Is The Difference Between A Conventional, FHA, And VA template to make your document workflow more streamlined.
Understanding the three loan form types
The difference is that conventional loans follow lender and investor requirements, FHA loans follow Federal Housing Administration requirements, and VA loans follow Department of Veterans Affairs eligibility and guaranty rules. This comparison is not one universal government form: the applicable document depends on the lender, borrower, property, and selected program. A borrower should identify the program first, then complete the lender-approved form. With signNow, the sender can upload that document, review detected fields, route it to authorized signers, and preserve the completed file with an audit trail when electronic signing is accepted.
Who uses these loan form comparisons
Mortgage lenders
Mortgage lenders and loan processors use a comparison document to explain which conventional, FHA, or VA pathway may fit the borrower’s stated circumstances. They must still apply current underwriting rules, lender overlays, agency instructions, and state requirements before approving or submitting any official loan document.
Borrowers and advisers
Borrowers, real estate professionals, and housing counselors may use the document to organize questions about down payment, occupancy, eligibility, and required signatures. It is an educational comparison, not a substitute for the originating lender’s official application, disclosures, or underwriting decision.
How the loan form process works
The process begins with the lender’s selected loan program and ends with a signed, auditable record retained under the applicable policy.
Classify: Identify the applicable loan program. Upload: Upload the lender-approved document. Review: Review detected fields and terms. Complete: Send, sign, and archive the record.
Complete the loan form workflow
Use the lender-approved version, identify the applicable loan program, and preserve the completed document with its signing evidence.
Upload document:
Upload the lender-approved comparison or loan document. Check fields:
Review auto-detected fields and correct labels. Add signer:
Add the authorized signer and signing order. Send document:
Send the reviewed document through signNow. Sign document:
Review and complete the required signature fields. Store records:
Store the signed file with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How the audit trail records signing
The signNow audit trail records the technical history of the selected conventional, FHA, or VA document after it is sent for signature.
Signer authentication:
Timestamp capture:
Document hashing:
Tamper-evident sealing:
Action history:
Audit export:
Best practices for comparing loan forms
Accurate comparisons begin by identifying the loan program and preserving the lender’s supporting instructions alongside the completed document.
Confirm the loan program before completing forms
Match every field to verified borrower information
Obtain lender review before relying on comparisons
Keep supporting records with the signed document
Privacy and disclosure pitfalls
Including military-service information in a shared comparison can expose sensitive personal data to unauthorized recipients. Sending a borrower document before obtaining electronic-record consent can create a consumer-disclosure problem under ESIGN. Using one signing link for several borrowers can weaken attribution and make the audit record harder to interpret. Storing loan-program comparisons without access controls can expose financial, property, and identity information.
Risks of comparing loan forms incorrectly
Misclassified loan
Wrong eligibility
Processing delay
Disclosure dispute
Recommended setup for loan documents
Use lender-approved content, controlled signer access, and an exportable audit record for each completed loan-program document.
| Setting | Recommendation |
|---|---|
| Authentication and signature method | Email link with SMS verification |
| Audit trail | Export with the completed document |
| Document retention | Follow lender and state policy |
| Encryption | TLS 1.2/1.3 and AES-256 |
| User provisioning | Admin-managed access and roles |
Legal standing of signed loan documents
A signed conventional, FHA, or VA loan document may be admissible when the parties show intent, consent, attribution, and reliable record retention under ESIGN and applicable state law, including UETA or New York ESRA. Wills, codicils, testamentary trusts, court orders, and family-law decrees remain excluded from ESIGN’s ordinary electronic-signature framework.

Security controls for signed documents
Data in transit:
Data at rest:
Security certification:
Information security:
Electronic signatures:
Protected health information:
Loan document processing stages
Processing depends on lender instructions and signer availability; the workflow separates preparation, delivery, signing, and controlled archival.
Document preparation
Delivery to signers
Signer turnaround
Completion and archival
Questions about conventional, FHA, and VA forms
These answers distinguish loan-program comparisons from official lender documents and explain how signNow handles preparation, signing evidence, and document control.
signNow Business includes legally binding eSignatures, templates, and audit trails at $8 per user monthly when billed annually. Confirm the lender accepts electronic records before sending this loan-program comparison for signature.
The signNow Business plan includes 100 signature invites per user per year, with overage fees. Business Premium adds bulk send, but neither plan changes FHA, VA, or conventional lender eligibility rules.
Use signNow’s audit trail to document authentication, timestamps, actions, and completion history. The audit trail supports evidence of the signing event, but it does not prove that a borrower qualifies for a specific loan program.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record reproducibility are established. Consumer transactions may require disclosures under 15 U.S.C. §7001(c), and lender policy still controls acceptance.
For a borrower comparison, identify the selected program before placing fields. Upload the source PDF, review signNow’s detected fields, correct labels manually, then send only the lender-approved version for signature.
A VA comparison should not be treated as a VA loan application, and an FHA comparison should not substitute for HUD or lender documentation. Ask the originating lender which official form and submission channel applies.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.