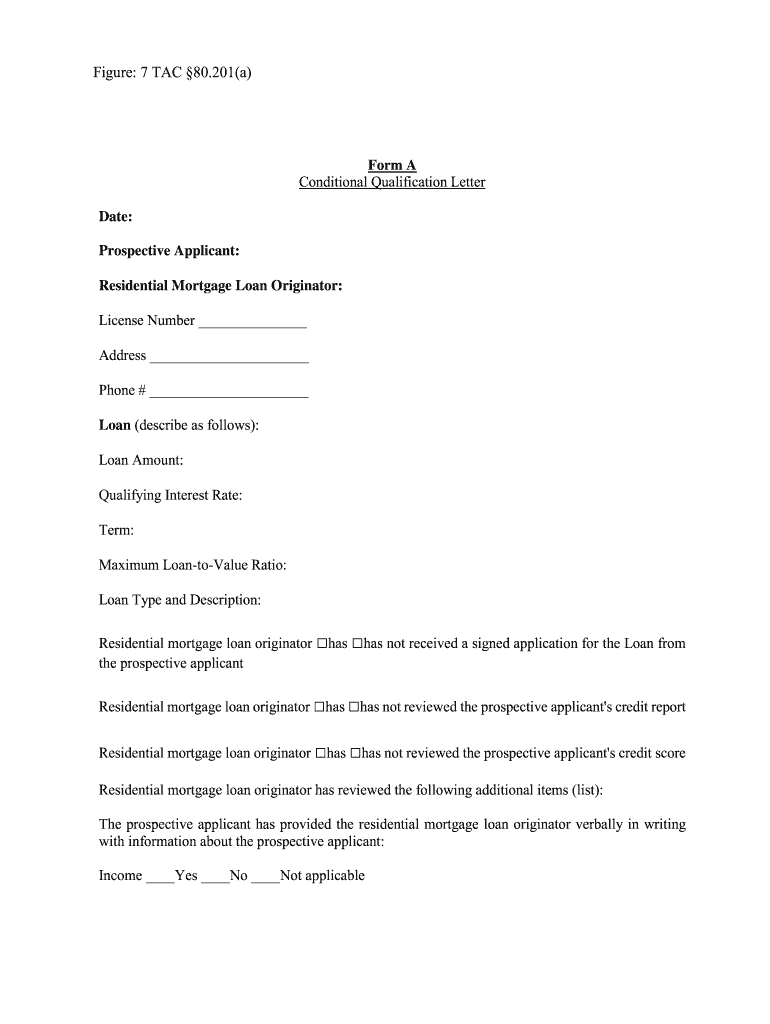
Texas Conditional Qualification Letter For Mortgage Form
Use a Texas Conditional Qualification Letter For Mortgage 0 template to make your document workflow more streamlined.
What this Texas mortgage letter does
A Texas Conditional Qualification Letter For Mortgage Form is a lender’s preliminary written indication that a borrower may qualify for mortgage financing subject to stated conditions and further verification. It is not the same as final loan approval, a commitment to lend, or proof that every underwriting requirement has been satisfied. The letter generally identifies the borrower, proposed financing context, conditions, and authorized lender representative. With signNow, the team uploads the letter, detects or places fillable fields, routes it to the required signers, and preserves the completed document with an audit trail.
Who benefits from this workflow
The workflow is useful wherever Texas mortgage professionals issue conditional qualification letters that require review, signatures, and controlled record handling.
Texas mortgage brokers and loan officers can prepare conditional qualification letters for borrowers, route required signatures, and preserve completion evidence before underwriting advances the file. Regional lending teams can standardize borrower and lender fields through shared templates while retaining role-based review for each qualification letter and its stated conditions. Mortgage enterprises can connect qualification-letter workflows with approved systems, controlled access, and audit trails so distributed branches use consistent signing and record-handling procedures.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features that support mortgage qualification letters
signNow combines document preparation, signer routing, mobile access, audit evidence, and controlled storage for this Texas mortgage qualification workflow.
Form preparation
Upload the Texas Conditional Qualification Letter For Mortgage Form, then use signNow’s field tools to prepare borrower, lender, date, and signature areas without recreating the document.
Signer routing
Send the completed letter to each designated signer in sequence, helping mortgage teams track outstanding signatures instead of relying on separate email follow-ups.
Audit trail
Capture signer actions, timestamps, and document history in an audit trail that supports later review of the qualification letter’s completion process.
Mobile access
Use mobile apps to let loan officers and borrowers review the Texas letter away from a desk while preserving the same signing record.
Team controls
Apply role-based access and shared templates so mortgage organizations can control who prepares, sends, reviews, and stores qualification letters.
Record storage
Store the signed qualification letter with its completion evidence, giving authorized staff a consistent record for underwriting and internal file review.
How the qualification letter moves forward
The workflow follows the letter from lender preparation through conditional review, signature collection, and documented storage.
Review the letter: Identify parties and conditions Add fields: Prepare required fields Send securely: Route for signatures Archive records: Store completion evidence
Complete the letter in signNow
Prepare the lender’s exact Texas qualification letter, route it to authorized parties, and preserve the signed record with completion evidence.
Upload letter:
Upload the lender-provided letter. Add fields:
Place borrower and lender fields. Route document:
Send to designated signers. Complete signing:
Review and sign electronically. Store copy:
Save the signed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Choose the right signing method
- Use the signNow web app when preparing the mortgage qualification letter on a desktop, placing fields, checking values, and sending it to borrowers or lending staff.
- Use the signNow mobile app when a loan officer or borrower needs to review and sign the qualification letter from an iOS or Android device.
- Use kiosk mode for an in-office signing appointment where borrowers complete the qualification letter on a managed device without receiving an individual invitation.
- Use a shareable signing link when the same qualification letter must reach borrowers through a controlled email, text message, portal, or mortgage workflow.
What the audit trail records
The audit trail documents how this qualification letter was authenticated, completed, protected, and retrieved after signing.
Authenticate signer:
Timestamp actions:
Hash document:
Seal document:
Retain history:
Export trail:
Recommended workflow configuration
Use a controlled signing configuration that matches the lender’s authentication, access, audit, encryption, and loan-record requirements.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Enabled for every completed letter |
| Document retention | Follow the lender’s loan-record policy |
| Encryption | TLS in transit and AES-256 at rest |
Signer authentication options
Digital certificates:
Certificate standard:
Two-factor access:
SMS verification:
Identity checks:
Signing evidence:
Best practices for this Texas letter
Accurate preparation matters because a conditional qualification letter communicates preliminary lending information rather than a final approval decision.
Verify every qualification condition
Assign fields to the correct signer
Preserve conditional language
Protect the completed loan record
Privacy and disclosure pitfalls
Borrower income, property, or loan details may be exposed when the qualification letter is sent to an unintended email address or shared through an uncontrolled link. A borrower may sign without understanding that conditional qualification is not final loan approval, making clear wording and documented consent important for the mortgage file. Overbroad staff permissions can expose personally identifiable information and lender conditions to employees who do not need access to this qualification letter. A corrected qualification letter can create conflicting records if the original signed version and replacement are not clearly labeled, linked, and retained.
Legal standing of the signed letter
A properly executed electronic qualification letter can generally be recognized under the federal ESIGN Act, 15 U.S.C. ch. 96, and applicable Texas electronic-transactions law when intent, consent, attribution, and record retention are established. It remains conditional and does not itself create final loan approval. ESIGN exceptions include wills, certain family-law decrees, and court orders.

Platform requirements for signing
Prepare the Texas Conditional Qualification Letter For Mortgage Form in Chrome, Firefox, Safari, or Edge on Windows or macOS. signNow also provides mobile apps for iOS and Android, allowing authorized participants to review and sign from supported mobile devices.
Browsers Chrome, Firefox, Safari, Edge Desktop systems Windows and macOS computers Mobile systems iOS and Android mobile apps
Mortgage organizations should confirm that managed Windows, macOS, iOS, and Android devices permit document access, signer authentication, and secure browser sessions. Teams using Salesforce, Microsoft Dynamics 365, NetSuite, Google Drive, Box, or another connected system should also verify administrator permissions and the organization’s signNow integration configuration before routing qualification letters.



Troubleshooting the Texas qualification letter
These answers address document preparation, signer routing, electronic execution, plan capabilities, and record handling for this mortgage letter.
Upload the original lender PDF again and confirm that the document is not password-protected or corrupted. If automatic field detection misses a borrower or lender field, place it manually, assign the signer, and test the routing before sending.
The Business plan includes templates and audit trails, while Business Premium adds bulk send and quick invite links. For one qualification letter, prepare the document individually unless the lender has approved a reusable template.
A signNow electronic signature can support a qualifying transaction when the parties demonstrate intent, consent, attribution, and record retention under ESIGN and applicable state law. Confirm lender policy before using electronic execution for this letter.
Use signNow’s signer assignment and routing controls to distinguish borrower, co-borrower, loan officer, and lender reviewer roles. Do not substitute an employee’s signature for a borrower’s required signature.
The letter should state that qualification is conditional and subject to underwriting conditions. Ask the lender to correct inaccurate income, property, loan, or condition information before sending a new version.
Retain the signed letter together with its completion evidence and follow the lender’s documented loan-record policy. signNow provides audit trails and storage features, but the lender determines the applicable retention period.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.