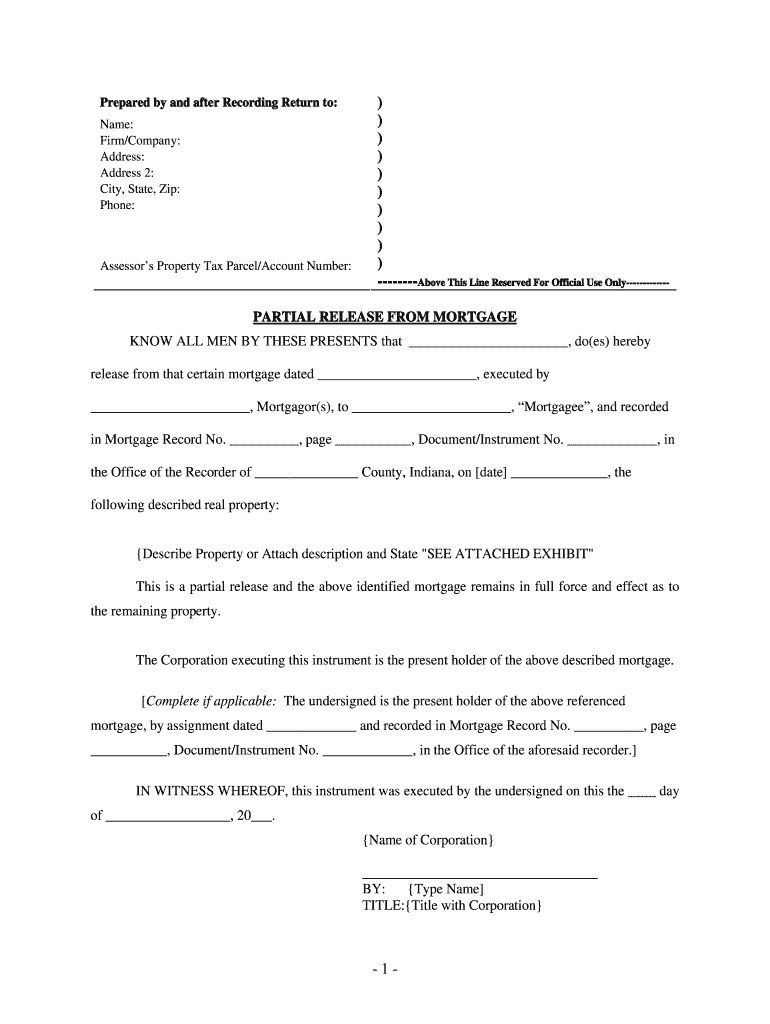
In Mortgage Record No Form
Use a In Mortgage Record No template to make your document workflow more streamlined.
What In Mortgage Record No Form is
In Mortgage Record No Form is an unspecified mortgage-record document that can be prepared and signed electronically only when its lender, transaction, state-law, and recording requirements allow it. The available form name does not identify an issuing agency, official field set, filing deadline, loan type, notarization rule, or retention period. In signNow, upload the source document, review or place fillable fields, assign each signer, send the record, and preserve the completed PDF with its audit trail. Confirm mortgage-specific requirements with the responsible lender, recorder, or counsel before execution.
Who uses mortgage record forms
Lenders and servicers
Mortgage lenders and servicers can route borrower acknowledgments, approvals, and related record documents through signNow when their policies permit electronic signatures and the document does not require excluded execution steps.
Transaction participants
Borrowers, brokers, and closing professionals can review assigned fields and sign the uploaded mortgage record, subject to lender instructions, state law, notarization, and recording requirements.
Key features for mortgage record completion
In Mortgage Record No Form can be prepared, routed, signed, and retained in signNow when its transaction-specific requirements permit electronic execution.
Document upload
Upload the mortgage record document and preserve its original wording while preparing fields for completion, review, and signature. This keeps the source document identifiable throughout the signNow workflow.
Field review
Auto-detect fillable areas when available, then review every field manually. Because no official field list is supplied for this form, confirm required names, dates, property details, and signatures against the source.
Role assignment
Assign each mortgage record field to the correct participant before sending. Separate borrower, lender, witness, and notary responsibilities only when the underlying document expressly requires them.
Signature routing
Send the prepared mortgage record through signNow for electronic signing when the transaction and governing state law permit it. Record signer consent before execution.
Audit evidence
Capture signer actions, timestamps, and document history in the audit trail. Retain the completed record with its audit evidence according to the applicable mortgage, lender, and state policies.
Connected records
Use signNow integrations such as Salesforce, NetSuite, Google Drive, Box, or Procore only when the connected system matches the mortgage workflow and approved record-storage policy.
Recommended mortgage record setup
Configure the mortgage record workflow around signer identity, document evidence, access control, and the responsible lender’s retention policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS verification |
| Signature type | Electronic signature with signer consent |
| Audit trail | Preserve completed record history |
| Document retention | Apply lender and state policy |
| Encryption and provisioning | AES-256 storage with role-based access |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Steps to complete the mortgage record
Use the source mortgage record as the controlling document while preparing, routing, signing, and storing its electronic version in signNow.
Upload document:
Upload the original mortgage record document. Prepare fields:
Review detected fields and add missing fields. Assign roles:
Assign each field to the correct signer. Complete record:
Send, complete, and store the audit trail.
How the mortgage audit trail works
The audit trail documents who interacted with In Mortgage Record No Form, when actions occurred, and how the completed record was preserved.
Authenticate signer:
Record timestamp:
Protect document:
Compare versions:
Export evidence:
Control access:



Security controls for mortgage records
Transport encryption:
Storage encryption:
Security reporting:
Information security:
Electronic signatures:
Signer authentication:
Legal standing of mortgage records
An electronically signed mortgage record may receive legal recognition under the federal ESIGN Act, 15 U.S.C. ch. 96, and applicable state law such as UETA when intent, consent, attribution, and reproducible records are established. Wills, court orders, family law decrees, and other statutory exclusions are not covered automatically; state recording and notarization rules may also apply.

Record-keeping practices for mortgage documents
Protect the completed mortgage record by validating fields, preserving audit evidence, and applying the retention rule established by the responsible lender or authority.
Set retention from governing policy
Verify every source field
Match authentication to risk
Archive evidence securely
Risks in mortgage record execution
Incomplete fields
Missing audit trail
Unmet notarization
Incorrect execution
Privacy and disclosure pitfalls
Mortgage records may expose borrower names, addresses, loan details, and property information when access permissions or shared links are configured incorrectly. A signer may complete the document without a documented electronic-record disclosure when consumer-facing ESIGN requirements under 15 U.S.C. §7001(c) apply. Sending the wrong mortgage-record version can create conflicting terms, incomplete approvals, or an audit trail that does not match the lender’s source document. Electronic signing does not replace state-specific notarization, witness, recording, or lender requirements that may apply to a mortgage-related instrument.
Troubleshooting mortgage record signing
Resolve document, authentication, plan, and legal-execution questions before circulating In Mortgage Record No Form to borrowers or lenders.
Upload the source PDF again and check whether its fields are flattened, protected, or image-based. signNow can prepare editable fields, but every detected field must be reviewed against the original mortgage record before sending.
The Business plan includes legally binding eSignatures, templates, mobile apps, and audit trails at $8/user/month when billed annually. If bulk sending is required for multiple mortgage records, Business Premium adds that capability at $15/user/month annually.
signNow states that its ESIGN and UETA compliance supports electronic transactions, but the form’s enforceability still depends on transaction facts, consent, record access, and applicable state law. Review mortgage-specific notarization or recording rules separately.
Use signNow’s audit trail to preserve signer actions, timestamps, and document history. For a mortgage record, compare the completed PDF and audit evidence with lender procedures, state recording requirements, and the original source document.
If a signer cannot open the invitation, verify the email address, resend the request, or provide a signNow signing link. SMS authentication may add identity assurance, but it does not resolve an incorrect recipient address.
The Business plan includes 100 signature invites per user annually, with overage fees. Business Premium includes bulk send, while Site License pricing is $1.50 per signature invite for usage-based deployments.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.