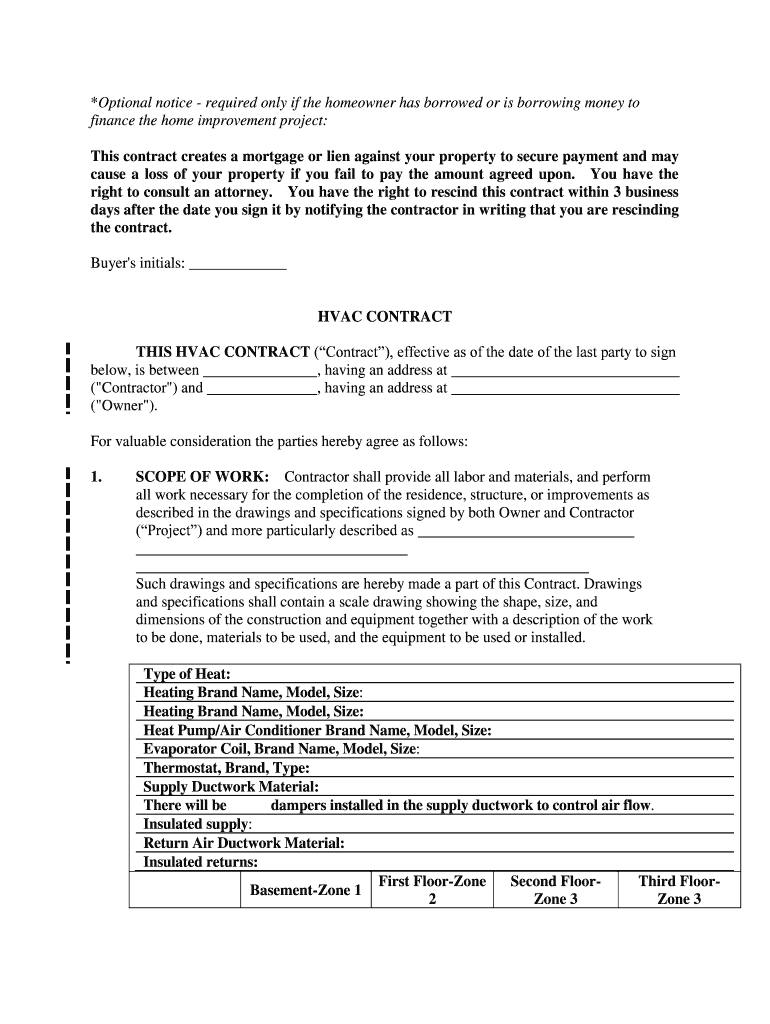
Notice Required Only If The Homeowner Has Borrowed Or Is Borrowing Money To Form
Use a *Optional Notice Required Only If The Homeowner Has Borrowed Or Is Borrowing Money To template to make your document workflow more streamlined.
What this homeowner notice does
This notice records whether a homeowner has borrowed, or is borrowing, money relevant to a transaction. It gives the homeowner a focused place to disclose that condition, identify supporting transaction information, and sign the statement. With signNow, a sender uploads the notice, reviews detected fillable fields, assigns the homeowner, and sends it electronically. The completed document and audit trail preserve the signer’s intent, activity, and timestamps. ESIGN and applicable UETA rules generally recognize qualifying electronic records, subject to consumer disclosures and statutory exceptions.
Who uses this homeowner notice
Homeowners
Homeowners use this notice to document whether borrowed money affects the transaction and to preserve a clear record for lenders, title professionals, or other authorized parties reviewing the homeowner’s disclosure.
Transaction professionals
Lenders, title professionals, and attorneys use the notice to collect the homeowner’s statement, confirm the relevant borrowing condition, and retain a signed record with transaction documents.
How the homeowner notice works
The notice moves from document preparation to homeowner disclosure, signature, and secure recordkeeping in four traceable steps.
Upload the form: Upload the homeowner notice and review detected fields. Add recipients: Add the homeowner and any authorized recipient. Send the notice: Send the borrowing disclosure for electronic completion. Archive evidence: Store the signed record and audit trail.
Complete the homeowner notice online
Use this sequence to prepare, route, sign, and retain the homeowner notice without losing the disclosure record.
Upload document:
Upload the completed homeowner notice. Review fields:
Check fields for borrowing details and signatures. Assign signer:
Assign the homeowner as signer. Send for signature:
Send the notice through signNow. Save records:
Download the signed notice and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended setup for the notice
Configure the workflow around homeowner identity, electronic consent, transaction evidence, and controlled access to the completed notice.
| Setting | Recommended configuration |
|---|---|
| Authentication method | Email link with SMS verification |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture signer actions and timestamps |
| Document retention | Retain under transaction policy |
| Encryption and access | TLS 1.2/1.3 and AES-256 |
Security for signed notices
Data encryption:
Transport security:
Service assurance:
Information security:
U.S. eSignature:
Protected health data:
Best practices for this notice
Accuracy, consent, and evidence preservation matter when a homeowner’s borrowing statement becomes part of a transaction record.
Confirm the borrowing condition before sending
Match transaction details across records
Capture consent before electronic signing
Preserve the notice and audit trail
Challenges when completing the notice
The homeowner’s answer does not match lender, title, or transaction records, creating an avoidable discrepancy during review. The notice omits the borrowing condition or leaves the relevant disclosure field blank before signature. Electronic consent is not documented before signing, weakening proof that the homeowner agreed to receive the notice electronically. The signed notice is saved without its audit trail, making signer identity, timestamps, and document history harder to establish.
Risks requiring review
Electronic record challenge
Attribution dispute
Evidence challenge
ESIGN exception
What the audit trail records
The audit trail adds evidence around the homeowner’s specific disclosure, signature event, document integrity, and completed-record retrieval.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Record activity:
Export evidence:
Troubleshooting the homeowner notice
Resolve field, consent, signing, and recordkeeping issues by checking the document setup and the applicable U.S. electronic-signature rules.
If the homeowner cannot open the signing request, confirm the email address, resend the invitation, and check whether the message was filtered. signNow Business includes email-based eSignature workflows; SMS authentication can add a separate verification step.
Upload the original PDF again and inspect the detected fields before sending. signNow can identify fillable areas, but the sender remains responsible for confirming that borrowing details, dates, and signature fields are positioned correctly.
For a consumer transaction, provide the ESIGN electronic-record disclosure and confirm access to the electronic format before signing. Section 101(c) of ESIGN, 15 U.S.C. §7001(c), also requires a withdrawal procedure.
A completed notice can be supported by signNow’s audit trail, which records signing activity and timestamps. Under ESIGN and applicable UETA rules, retain a reproducible record and evidence of intent and attribution.
Do not use this workflow for a will, court filing, family-law decree, or another ESIGN exception. Those records may require a different signing or filing process under applicable law.
Business pricing is $8/user/month when billed annually, while Business Premium is $15/user/month and adds bulk send. Both plans include audit trails; exact plan limits should be checked before high-volume use.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.