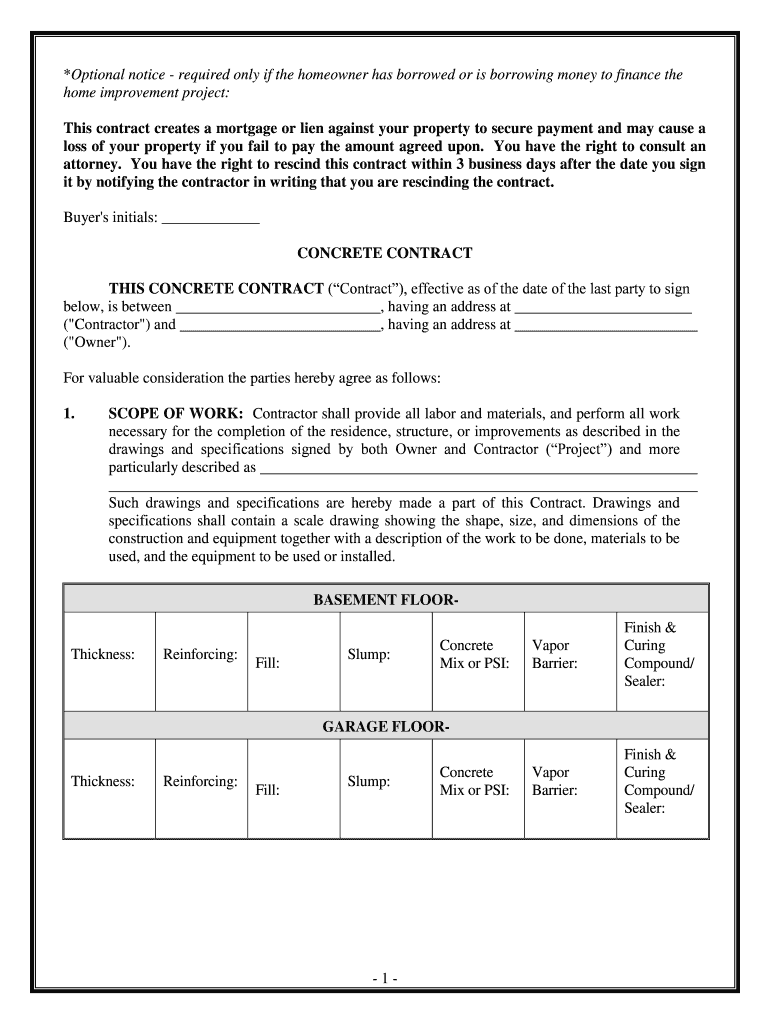
Homeowner borrowing notice form
Use a *Optional Notice Required Only If The Homeowner Has Borrowed Or Is Borrowing Money To Finance The template to make your document workflow more streamlined.
What the homeowner borrowing notice does
The homeowner borrowing notice records that borrowed money is being used to finance a homeowner-related transaction or obligation. Its purpose is to make the financing circumstance visible to the parties reviewing the transaction, including the homeowner, lender, settlement professionals, or counsel. The completed notice should identify the relevant homeowner and transaction details, state the applicable financing disclosure, and capture the required signature and date. signNow can prepare the document, route it to the signer, and preserve the completed PDF with an audit trail. Requirements for the underlying transaction remain governed by applicable contract and state law.
Who uses the homeowner borrowing notice
Homeowners
Homeowners use this notice to disclose financing details when borrowed funds support the transaction or property-related obligation.
Transaction teams
Lenders, settlement teams, and legal professionals review the signed notice alongside financing and closing records.
Why teams look for DocuSign alternatives
Organizations seek alternatives when they need different pricing models, stronger native automation, simpler bulk affidavit workflows, or more flexible identity-verification options than those available in a legacy envelope-based vendor.

 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Features for this financing notice
signNow connects form preparation, signer routing, authentication, and audit evidence for a homeowner borrowing notice workflow.
Field placement
Upload the notice and use signNow’s field tools to place names, dates, disclosures, and signature fields accurately before sending.
Signer routing
Send the financing notice to the homeowner or other signer by email, with signing order and required fields configured.
Intent capture
Capture signer intent through an electronic signature workflow that records each completed action and document event.
Signer verification
Use SMS authentication when the transaction requires an additional signer verification step beyond the email invitation.
Record storage
Keep the completed notice and certificate of completion together for transaction review, subject to your retention policy.
Audit evidence
Export the audit trail with the signed notice when lenders, counsel, or settlement personnel need transaction evidence.
How the notice workflow works
A focused signNow workflow moves the homeowner borrowing notice from an uploaded document to a signed, traceable transaction record.
Upload notice: Upload the homeowner borrowing notice PDF. Review fields: Auto-detect fields, then review required entries. Send notice: Send the notice to the designated signer. Archive record: Store the signed PDF and audit trail.
Complete the notice in signNow
Prepare the homeowner borrowing notice carefully, then route it through signNow for signature and documented completion.
Upload document:
Upload the notice PDF to signNow. Prepare fields:
Confirm detected fields and add missing fields. Assign signer:
Assign the homeowner as signer. Complete workflow:
Send, monitor, and download the completed record.
What the audit trail records
The audit trail documents signer access, authentication, document activity, completion, and retrieval for the homeowner borrowing notice.
Authenticate signer:
Capture timestamp:
Link activity:
Seal history:
Confirm completion:
Retrieve evidence:
Recommended notice workflow setup
Use a controlled configuration for identity, signing, evidence, retention, and document protection when preparing this homeowner borrowing notice.
| Setting | Recommendation |
|---|---|
| Authentication method | Email invitation with SMS verification |
| Signature type | Electronic signature with signer intent |
| Audit trail | Export certificate with completed notice |
| Document retention | Retain under transaction policy |
| Encryption | TLS 1.2/1.3 and AES-256 |
Rules that may limit electronic use
Notarization
Wills
Real-estate deeds
Family law
Troubleshooting the homeowner borrowing notice
Resolve field, consent, authentication, plan, legal-validity, and privacy questions before relying on the completed notice in a transaction.
On the Business plan, upload the notice, place signature and date fields, and send it through signNow’s standard invitation workflow. If the document uses repeated signer fields, Business Premium adds bulk send for multiple prepared notices.
signNow’s Business plan supports legally binding eSignatures and audit trails. For consumer-facing electronic records, provide the ESIGN disclosure, demonstrate electronic access, and explain withdrawal procedures under 15 U.S.C. §7001(c).
Use signNow SMS authentication when an added verification step is appropriate. Advanced signer authentication is available in Enterprise, while the transaction owner remains responsible for choosing controls required by applicable law.
Business includes audit trails, templates, and mobile apps at $8/user/month with annual billing. Business Premium costs $15/user/month annually and adds bulk send, kiosk mode, payments, and quick invite links.
A completed notice may be electronically enforceable when intent, consent, attribution, and record retention are established under ESIGN and applicable UETA or New York ESRA rules. Those frameworks do not replace transaction-specific state requirements.
If the notice contains sensitive financial information, restrict document access and export the signed PDF with its audit trail. signNow encrypts data in transit with TLS 1.2/1.3 and at rest with AES-256.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.