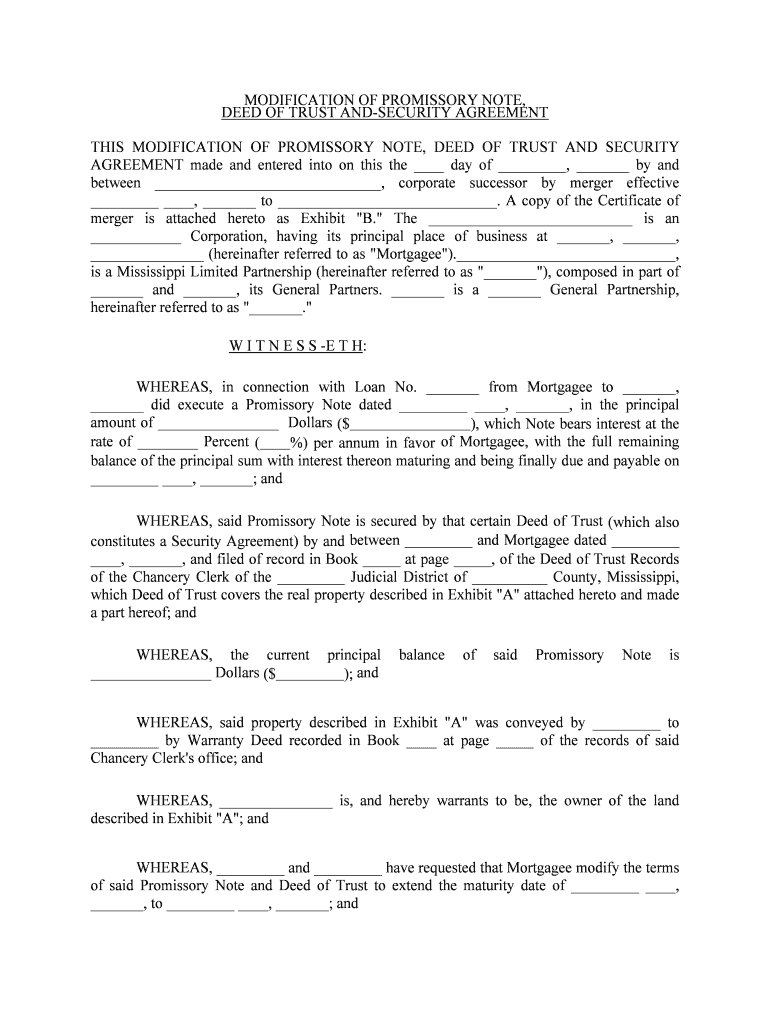
Modification Of Promissory Note, Deed Of Trust, Security Form
Use a Modification Of Promissory Note, Deed Of Trust, Security template to make your document workflow more streamlined.
What this loan modification form does
A Modification Of Promissory Note, Deed Of Trust, Security Form records agreed changes to an existing secured loan, such as its interest rate, payment schedule, maturity date, or other terms. The borrower and lender identify the original note and deed of trust, state the revised provisions, and sign the amendment. Because the deed of trust secures repayment against real property, state recording, acknowledgment, and notarization rules may apply. Review the property state’s requirements before signing, and confirm whether the modification must be recorded to preserve priority or notice.
Who uses this modification form
Borrowers and lenders
Borrowers and lenders complete the modification to document revised payment, interest, maturity, or collateral terms connected to an existing secured obligation.
Loan administration
Mortgage servicers, real-estate counsel, and title teams use the signed record to coordinate approvals, recording review, and retention.
Businesses that use secured loan modifications
The form is most useful where revised loan terms must remain tied to an existing real-estate security instrument.
Small real-estate investment companies use the form to document amended repayment terms with borrowers while preserving a clear connection to the original promissory note and deed of trust. Mortgage-servicing departments use it to formalize approved rate, payment, or maturity changes, route signatures in order, and retain the completed modification with its audit record. Commercial lenders and property finance enterprises use standardized templates to coordinate borrower, lender, trustee, and notary requirements across multiple secured loan modifications.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How this loan modification works
The process links the revised loan terms to identified parties, signatures, and a retained completion record.
Upload: Upload the existing loan modification PDF. Prepare: Auto-detect fillable fields and review them. Assign: Assign borrower, lender, and witness fields. Complete: Send, sign, and store the completed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Steps to complete this form
Prepare the existing loan modification carefully, then use signNow to route signatures and preserve evidence of completion.
Upload form:
Upload the existing modification form. Review fields:
Review auto-detected fields and loan terms. Assign parties:
Assign borrower, lender, and notary fields. Send for signature:
Send the document for ordered signatures. Store records:
Store the signed PDF and audit trail.
Recommended signing workflow setup
Use signer verification, an electronic audit trail, and controlled retention when processing this secured loan modification.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification plus SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Capture timestamps, IP addresses, and actions |
| Document retention | Retain under the loan record policy |
| Encryption | TLS 1.2/1.3 and AES-256 encryption |
Signer authentication and certificates
PKI:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Signer attribution:
How the audit trail records signing
The audit trail documents who handled the loan modification, when each action occurred, and how the completed record can be reviewed.
Signer authentication:
Timestamp capture:
Document hashing:
Tamper-evident sealing:
Action history:
Audit export:
Privacy and disclosure pitfalls
Borrower and lender may sign different versions when the original note and revised exhibits are not locked before sending. Personal addresses, loan balances, and property details can be exposed when access permissions are broader than the transaction team requires. A missing electronic-consent disclosure can create evidence problems for consumer-facing transactions under ESIGN requirements. Unclear recording instructions can delay acceptance when the property state requires acknowledgment, witnesses, or additional deed formalities.
Record-keeping practices for loan modifications
A reliable record should connect the revised terms, signatures, property details, and evidence of completion.
Keep the modification with original loan records
Export the audit trail after completion
Restrict access to borrower information
Verify state recording requirements before signing
Troubleshooting this loan modification workflow
These answers address signing, consent, plan, audit-trail, and state-formality questions for this secured loan modification.
Business includes legally binding eSignatures, templates, audit trails, mobile apps, ISO 27001, SOC 2, and GDPR features. Confirm that the lender’s internal policy permits electronic execution for the transaction and that state recording requirements are separately satisfied.
Business Premium includes bulk send, but a single modification can be sent from Business. The annual Business price is $8 per user per month, while month-to-month pricing is $20 per user per month.
Consumer-facing electronic records require disclosure of the right to receive paper, access to the electronic format, and procedures for withdrawing consent under 15 U.S.C. §7001(c). Capture that consent before electronic signing.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record retention are established. They do not eliminate state requirements for notarization, witnesses, or recording of real-estate instruments.
Use ordered roles for borrower, lender, trustee, or other required parties, then review the audit trail for timestamps, IP information, and action history. Re-send only the current controlled version to avoid conflicting copies.
A signNow audit trail supports evidence of the signing event, but it does not decide whether the modification is enforceable under property law. Ask qualified counsel or the recording office about state-specific deed requirements.



Why teams look for DocuSign alternatives
Organizations seek alternatives when they need different pricing models, stronger native automation, simpler bulk affidavit workflows, or more flexible identity-verification options than those available in a legacy envelope-based vendor.

Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.