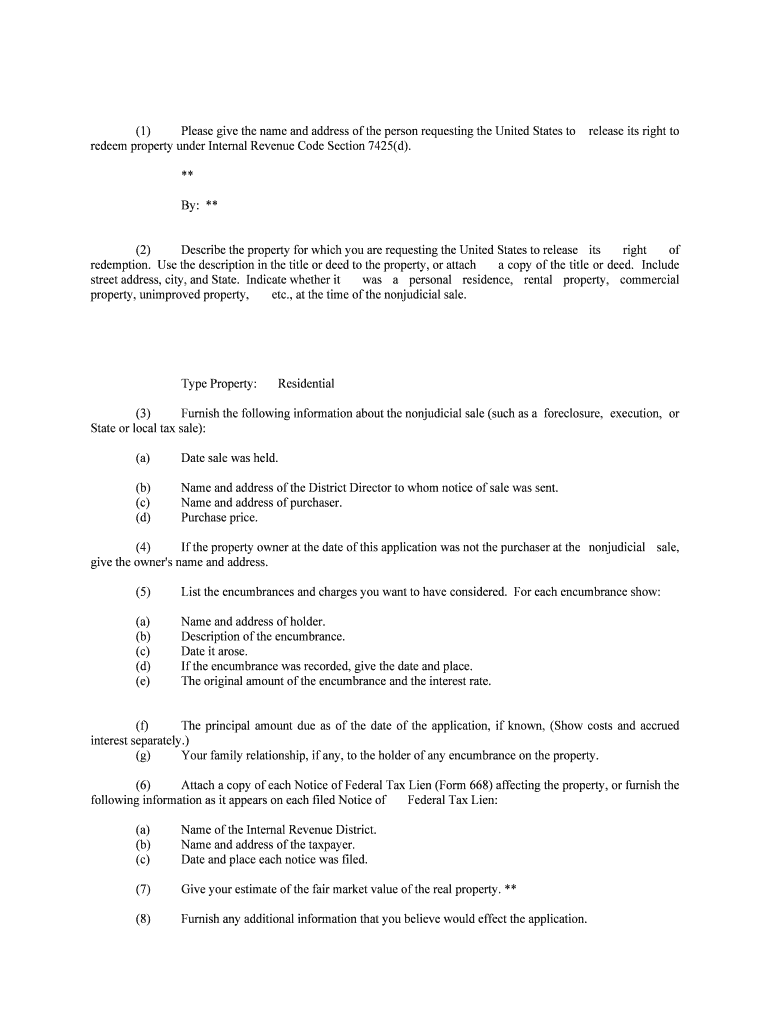
Publication 487 Rev 1 Internal Revenue Service Form
Use a Publication 487 Rev 1 Internal Revenue Service template to make your document workflow more streamlined.
What Publication 487 Rev 1 means
Publication 487 Rev 1 is an IRS publication reference, not a tax return or payment form. It explains the subject identified by its specific revision and should be read with the underlying IRS instructions and current law before a business relies on it. signNow can upload the publication, detect fillable areas when present, route a prepared copy for review or signature, and preserve the completed PDF with an audit trail. Publication 487 Rev 1 itself does not establish a filing deadline, payment amount, or universal signature requirement.
Business types using Publication 487 Rev 1
Publication 487 Rev 1 supports organized handling of IRS-related reference and documentation workflows across business sizes.
Solo tax practitioners use Publication 487 Rev 1 to organize client correspondence, capture required acknowledgments, and preserve signed records alongside engagement documentation. Regional accounting firms use the publication as a controlled reference when preparing standardized IRS-related communications, routing documents for approval, and retaining completed files for client audits. Enterprise finance departments use signNow workflows to distribute Publication 487 Rev 1 materials consistently, assign authorized reviewers, and maintain searchable completion records across multiple business units.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the workflow works
Publication 487 Rev 1 moves from source-document review to controlled signing and evidence preservation through four defined signNow stages.
Upload document: Upload the Publication 487 Rev 1 file. Prepare fields: Review detected fields and add required inputs. Route document: Send to authorized recipients through signNow. Complete record: Collect signatures and preserve the audit trail.
Inside the signNow audit trail
The audit trail documents who handled the Publication 487 Rev 1 record, when each event occurred, and how completed evidence can be retrieved.
Authenticate signer:
Capture timestamp:
Identify document:
Seal record:
Log activity:
Retrieve evidence:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended workflow configuration
Configure Publication 487 Rev 1 workflows around authorized access, documented intent, audit evidence, and the retention rule applicable to the underlying IRS record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email delivery with SMS authentication |
| Signature type | Electronic signature with recorded intent |
| Audit trail | Export completion certificate and event history |
| Document retention | Apply IRC §6501(a) where tax records apply |
| Encryption | TLS 1.2/1.3 and AES-256 protection |
Best practices for completing the form
Accuracy, controlled routing, documented consent, and complete evidence make Publication 487 Rev 1 workflows easier to review and reproduce.
Verify every field against the source
Assign authorized reviewers and signer roles
Document electronic consent before signing
Keep the signed file with evidence
Publication 487 Rev 1 processing stages
Processing depends on document readiness and recipient response; the workflow itself separates preparation, delivery, signing, and archival.
Document preparation
Delivery to signers
Signer turnaround
Completion and archival
Privacy and disclosure pitfalls
Uploading a scan with low contrast can obscure taxpayer names, dates, or reference text when fields are detected and prepared for signing. Sending a completed record to an unauthorized recipient can expose taxpayer information and create an access-control failure during later review. Failing to capture consumer electronic consent may weaken the record’s evidentiary foundation under the ESIGN Act’s disclosure requirements. Separating the signed PDF from its audit trail makes it harder to establish signer identity, intent, timestamps, and document history.
Risks of mishandling IRS records
Incomplete signer record
Misapplied publication guidance
Weak audit evidence
Taxpayer data exposure
Mobile options for Publication 487 Rev 1
signNow mobile apps for iOS and Android support completing Publication 487 Rev 1 workflows away from a desk, while camera-based capture can digitize paper pages before field review. Use a current supported operating system and a secure connection when uploading taxpayer-related records.
Mobile apps iOS and Android apps Offline workflow Offline signing support Document capture Camera-based capture
Organizations handling Publication 487 Rev 1 should manage mobile devices through approved access policies, require screen protection, and restrict downloaded copies. signNow supports mobile apps, offline signing, and camera-based document capture, but the organization remains responsible for validating source accuracy, signer authorization, retention, and any IRS or state requirements.
Security for IRS-related records
Transport encryption:
Storage encryption:
Security certification:
Management certification:
Electronic signing:
Health information:
Pricing and feature comparison
signNow pricing and capabilities are shown first; competitor figures and features are marked Not verified when unavailable in the supplied vendor data.
| Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|
| Starting price | $8/user/month, annual billing | Not verified | Not verified | Not verified | Not verified |
| Free trial | 7 days, no card required | Not verified | Not verified | Not verified | Not verified |
| Bulk sending | Business Premium, $15/user/month | Not verified | Not verified | Not verified | Not verified |
| Audit trail | Included with Business plan | Not verified | Not verified | Not verified | Not verified |
| HIPAA compliance | Available with BAA requirement | Not verified | Not verified | Not verified | Not verified |
Questions about Publication 487 Rev 1 workflows
These answers address field preparation, electronic consent, signNow plan capabilities, audit evidence, and retention considerations for Publication 487 Rev 1 records.
Upload the clearest available PDF or image, then compare signNow’s detected fields with the original Publication 487 Rev 1 pages. Correct field placement manually before sending; detection assists preparation but does not validate IRS content or taxpayer data.
The signNow Business plan includes templates and audit trails at $8 per user monthly when billed annually. If the workflow requires bulk sending, Business Premium adds that capability at $15 per user monthly billed annually.
Use signNow’s audit trail and completion certificate to preserve signer actions, timestamps, and delivery history. Legal effect still depends on intent, consent, attribution, and record reproducibility under ESIGN, 15 U.S.C. ch. 96, and applicable state law.
For consumer-facing electronic records, provide the ESIGN disclosure, explain the right to receive paper records, demonstrate electronic access, and describe withdrawal procedures under 15 U.S.C. §7001(c) before requesting a signature.
Use signNow roles and permissions to limit who can prepare, review, and send Publication 487 Rev 1. Export the audit trail after completion, then retain the underlying tax record under IRC §6501(a) or a longer applicable rule.
signNow’s Enterprise plan adds advanced signer authentication, while Site License supports SSO and full API access as listed add-ons. Select the control required by your policy, and verify any IRS-specific submission requirement separately.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.