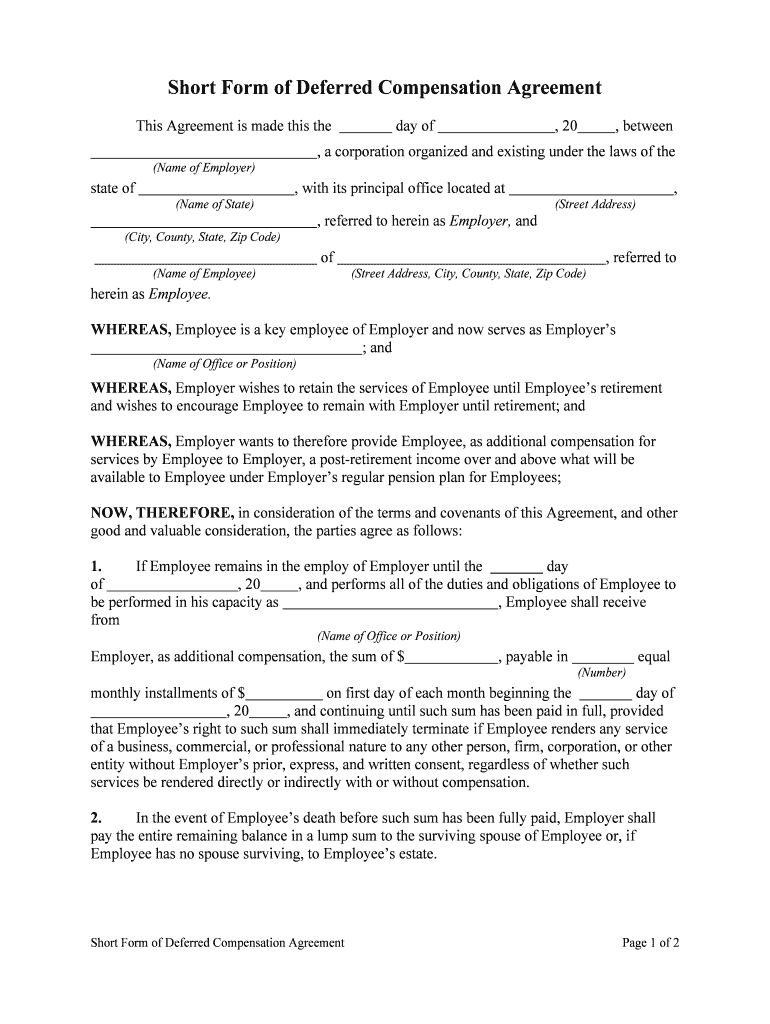
Section 457 Deferred Compensation Internal Revenue Service Form
Use a Section 457 Deferred Compensation Internal Revenue Service template to make your document workflow more streamlined.
What this Section 457 form does
The Section 457 Deferred Compensation Internal Revenue Service Form is used to document a participant’s deferred-compensation election or related plan information for an eligible governmental or tax-exempt employer. The title alone does not identify an official IRS form number, so the employer or plan administrator should verify the approved document and whether it supports a Section 457(b) or 457(f) arrangement. With signNow, an administrator uploads the approved PDF, checks detected fields, assigns signers, sends it, and stores the completed record with an audit trail.
Who uses Section 457 forms
Public employers, tax-exempt organizations, and their plan administrators use approved Section 457 documents to record participant elections and approvals.
A public-sector benefits office can route Section 457(b) participant elections to employees and plan administrators, preserving signed approvals and audit evidence alongside payroll records. A tax-exempt organization can use the workflow for approved deferred-compensation elections, while its administrator verifies plan eligibility, effective dates, and retention duties before accepting signatures. A multi-location employer can standardize an approved Section 457 template, delegate sending to authorized staff, and connect completed elections to its ERP or secure document repository.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Useful features for Section 457 forms
Section 457 administrators can combine verified fields, controlled routing, audit evidence, and connected storage around the employer-approved document.
Verified fields
Upload the employer-approved Section 457 PDF and verify detected fields before sending. This keeps plan-specific elections visible without recreating the document manually.
Signer routing
Assign participant, administrator, and approval fields in the required order. Role-based routing helps separate the employee election from plan-administrator review.
Audit evidence
Capture timestamps, signer actions, and completion evidence with the signed record. The audit trail supports later review of how the election was executed.
Reusable templates
Use templates for recurring Section 457 election documents after the plan administrator approves the source version. Version control reduces accidental use of an outdated form.
Mobile access
Send from a browser or mobile device when authorized staff work away from the office. The completed document remains connected to its signing workflow.
Connected storage
Store completed elections in connected systems such as NetSuite, Google Drive, Box, or Microsoft 365. Integration can reduce duplicate entry after completion.
How this Section 457 workflow works
The workflow keeps the deferred-compensation election document, signer actions, and completion evidence together from preparation through archival.
Upload document: Upload the Section 457 document. Add fields: Place fields for elections and signatures. Send to signers: Send assigned fields to authorized signers. Archive record: Store the completed record and audit trail.
Complete the Section 457 form
Use the approved plan document, verify its fields, and preserve the signed election with its audit evidence.
Upload form:
Upload the approved Section 457 document. Check fields:
Auto-detect fields, then verify every election field. Assign signers:
Assign signer roles and required signature fields. Complete record:
Send, monitor completion, and download records.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Configure the Section 457 workflow
Configure the Section 457 document around verified signer identity, plan-approved signatures, audit evidence, controlled retention, and encrypted storage.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps and signer actions |
| Document retention | Follow plan and IRS requirements |
| Encryption | TLS 1.2 or 1.3 and AES-256 |
Review the Section 457 audit trail
The audit trail records who handled the Section 457 document, when each event occurred, and how the completed record can be retrieved.
Signer authentication:
Timestamp capture:
Document hashing:
Tamper-evident seal:
Action history:
Audit export:
Authenticate signers for this form
Email authentication:
SMS verification:
Identity verification:
PKI signatures:
X.509 certificates:
Event evidence:



Keep Section 457 records accurately
Accurate classification, controlled access, and preserved audit evidence help administrators support each Section 457 election without assigning unsupported retention or tax rules.
Classify the election record
Export signed evidence promptly
Restrict access to participant data
Reconcile with plan documents
Set a retention schedule carefully
Retention depends on how the Section 457 document is used, the governing plan, and any other applicable federal or state recordkeeping rule.
Three years: tax records
Six years: tax understatement
Indefinite: fraud or no return
Six years: HIPAA records
Plan-specific: administrator records
Avoid Section 457 filing mistakes
The title does not identify whether the document supports a Section 457(b) or 457(f) arrangement, creating a plan-classification risk before signature. Unverified election fields can omit participant eligibility, deferral amounts, effective dates, or administrator approvals required by the employer’s governing plan. A signed PDF without its completion certificate and audit trail may provide weaker evidence of signer identity, consent, and document history. Applying a generic retention period can conflict with the employer’s plan rules, IRS record requirements, or state-specific employment-record obligations.
Why teams look for DocuSign alternatives
Organizations seek alternatives when they need different pricing models, stronger native automation, simpler bulk affidavit workflows, or more flexible identity-verification options than those available in a legacy envelope-based vendor.

Troubleshoot Section 457 form issues
Resolve document-identification, signer-authentication, plan-eligibility, and recordkeeping questions before relying on a completed Section 457 election.
signNow can route the Section 457 document through assigned fields, but the plan administrator must confirm eligibility, contribution limits, and election timing under the governing plan and IRC §457. Business includes templates and audit trails; advanced signer authentication is available in Enterprise.
The supplied title does not identify a standard IRS form number. Before sending, compare the document with the employer’s approved Section 457(b) or 457(f) plan materials and IRS guidance. Use signNow’s fillable fields only after the plan administrator confirms the correct form.
A typed or drawn signature can document intent when the signer consents and the record remains reproducible under ESIGN and applicable UETA rules. signNow records timestamps, signer activity, and a completion certificate; the employer remains responsible for plan-specific execution requirements.
Business provides legally binding eSignatures, templates, and audit trails at $8/user/month when billed annually. It includes 100 signature invites per user per year; additional invite charges may apply, so high-volume plan administration should review usage.
If the document contains protected health information, HIPAA compliance requires a business associate agreement with signNow. HIPAA’s six-year rule applies to covered-entity documentation under 45 CFR §164.530(j), not automatically to every Section 457 record.
Use signNow’s advanced authentication options when signer identity needs stronger evidence, including SMS verification or Enterprise authentication features. For a disputed election, preserve the completed PDF, certificate of completion, audit trail, and governing plan records together.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.