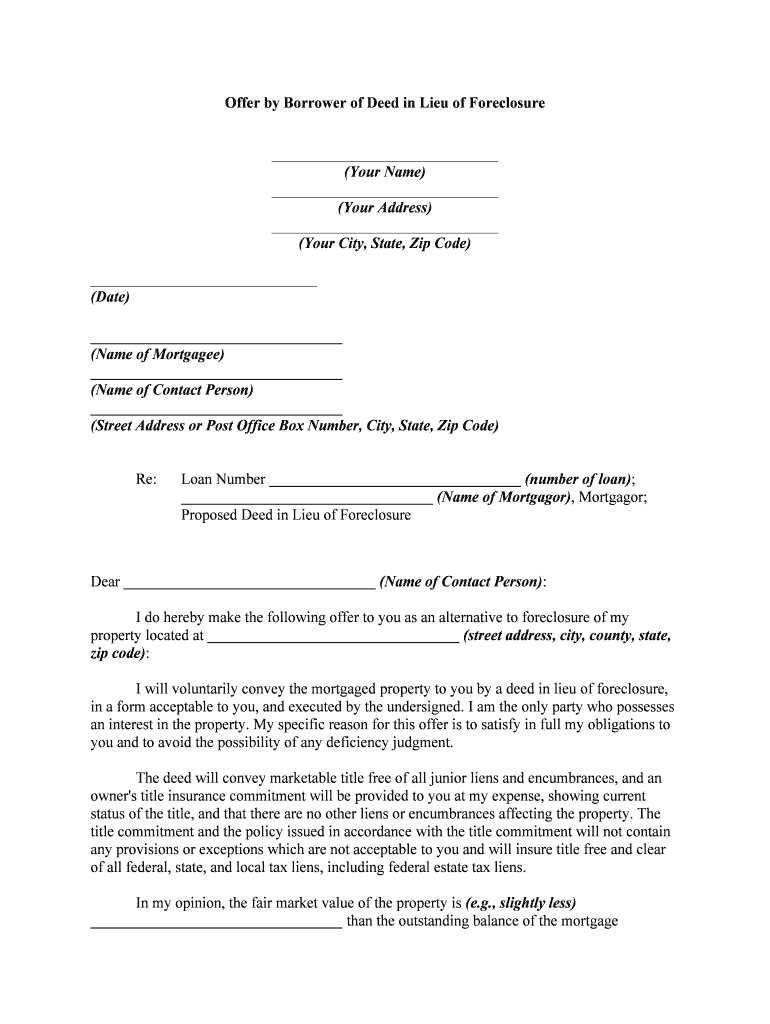
Offer By Borrower Of Deed In Lieu Of Foreclosureus Legal Forms
Use a Offer By Borrower Of Deed In Lieu Of ForeclosureUS Legal Forms template to make your document workflow more streamlined.
What this deed-in-lieu offer does
An Offer By Borrower Of Deed In Lieu Of Foreclosure is a written proposal in which a borrower offers to convey mortgaged property to the lender to avoid a foreclosure proceeding. It identifies the borrower, lender, property, loan, and proposed conditions for acceptance. The lender may require title review, lien checks, financial information, written approval, and a separate deed or settlement agreement. Signing the offer does not automatically transfer ownership, cancel the debt, or eliminate junior liens; those outcomes depend on the lender’s written agreement and applicable state law.
Who uses this deed-in-lieu offer
Distressed homeowners
Borrowers use this form to propose transferring property to a lender instead of proceeding through foreclosure. The document records the borrower’s offer, property details, lender review, and any negotiated conditions. Because deed transfers and foreclosure alternatives are governed by state law, parties should confirm required acknowledgments, title procedures, and lender approvals before signing.
Lenders and counsel
Mortgage servicers, lenders, and real-estate counsel review the offer, verify authority, assess title and liens, and document acceptance or rejection. A completed form can organize borrower representations and negotiated terms, but it does not itself guarantee approval, release liens, or complete recording requirements.
Who benefits from this workflow
The form is most useful when borrowers, lenders, and counsel need a traceable proposal before separate transfer and settlement documents are finalized.
A homeowner facing foreclosure can use the offer to present a documented property-transfer proposal, identify requested conditions, and send it to the mortgage servicer without confusing the proposal with a completed deed or debt release. A mortgage-servicing team can route borrower offers to authorized reviewers, preserve lender decisions, and maintain a consistent audit trail while title staff verify liens, ownership, and state recording requirements. A real-estate attorney or foreclosure counselor can prepare the borrower’s offer, coordinate lender signatures, and compare the signed proposal with the separate deed, settlement agreement, and recording documents required for completion.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the signing flow works
The signNow workflow keeps the borrower’s proposal, lender review, signatures, and completion evidence together without treating the offer as the deed itself.
Upload document: Upload the borrower’s completed offer PDF. Check fields: Review detected fields and add participants. Send for review: Send the offer to borrower and lender. Archive records: Store the signed offer and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Complete the offer in signNow
Check every property and loan detail before sending the offer to the lender for review and signature.
Review details:
Confirm borrower, lender, loan, and property details. Upload and check:
Upload the offer and inspect detected fields. Assign signers:
Assign borrower and lender signing roles. Send offer:
Send for review and signatures. Save evidence:
Download the completed record and audit trail.
What the audit trail records
For this property-transfer proposal, the audit trail separates evidence of signing from the deed, lender approval, and county recording process.
Authenticate signers:
Capture timestamps:
Hash document:
Seal document:
Log actions:
Export trail:
Signer authentication and certificates
Basic authentication:
Two-factor authentication:
ID verification:
PKI certificates:
X.509 certificates:
Completion evidence:
Recommended signing setup
Configure the offer so borrower identity, lender review, document integrity, and access controls are recorded consistently.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Export after lender completion |
| Document retention | Follow lender and state policy |
| Encryption and users | AES-256 with controlled access |
Privacy and disclosure pitfalls
Borrower financial information, loan numbers, addresses, and hardship details may appear in the offer and become visible to unintended recipients through forwarded copies or unrestricted signing links. A lender may receive a signed offer without a clear electronic-consent record, weakening evidence that the borrower agreed to use electronic records under 15 U.S.C. §7001(c). Shared templates can expose a prior borrower’s property address, loan data, or signature fields when staff reuse the document without removing old information. A signed offer may be mistaken for a recorded deed, debt release, or foreclosure dismissal even when the lender has not accepted its conditions in writing.
Record-keeping practices for this offer
Preserve the offer as part of the lender’s complete foreclosure-alternative file, with an exportable audit trail and a retention decision tied to the applicable record category.
Keep the offer with related closing records
Export the audit trail after completion
Restrict access to borrower information
Apply the correct retention authority
Troubleshooting deed-in-lieu signing issues
Resolve field, authentication, consent, and recording questions before treating the signed offer as a completed property transfer.
Upload the original Offer By Borrower Of Deed In Lieu Of Foreclosureus Legal Forms as a PDF, then use signNow’s field-detection tools to review every borrower, lender, property, loan, date, and signature field. On the Business plan, save the prepared document as a reusable template so later offers retain consistent placement without changing negotiated terms.
A signNow signature records intent and signer attribution under ESIGN and UETA, but it does not complete a deed transfer by itself. Confirm whether the lender requires notarization, witnesses, a separate deed, county recording, or original documents under the applicable state law before relying on the signed offer.
Business includes audit trails and templates at $8 per user per month when billed annually. Business Premium is $15 per user per month annually and adds bulk send, while Enterprise is $30 per user per month annually and adds advanced signer authentication and conditional fields.
If the lender requires stronger identity evidence, enable available signer-authentication controls rather than relying only on an email link. Enterprise adds advanced signer authentication. The audit trail should preserve the authentication event, timestamps, signer actions, and completed document for later review.
Consumer-facing electronic records may require disclosure of the right to receive paper records, access to the electronic format, and a process for withdrawing consent under 15 U.S.C. §7001(c). Obtain any required consent before sending this offer electronically, especially when the borrower is a consumer.
A signed offer can document the parties’ proposal and acceptance process, but foreclosure relief, deficiency waivers, lien releases, and title transfer require express written terms. Ask counsel to review the lender’s approval, settlement agreement, deed, and recording instructions before treating the matter as resolved.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.