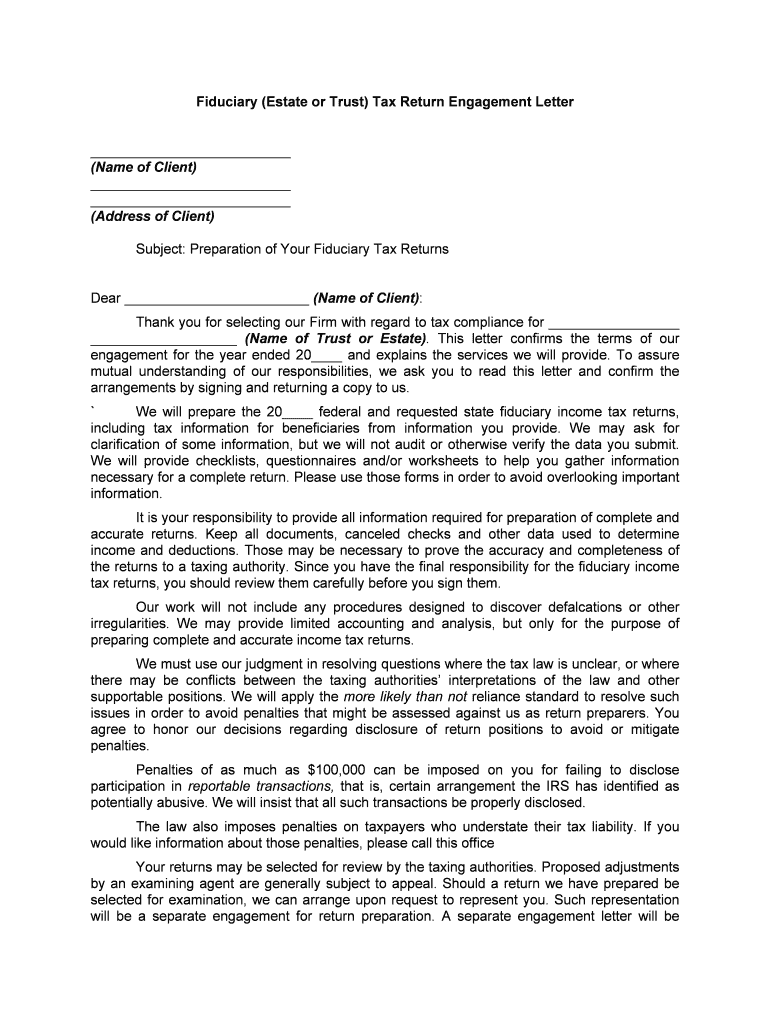
General Engagement Letter For Fiduciary Form 1041 Tax
Use a General Engagement Letter For Fiduciary Form 1041 Tax template to make your document workflow more streamlined.
What this fiduciary tax engagement letter does
The General Engagement Letter For Fiduciary Form 1041 Tax is an agreement that records a tax professional’s engagement to prepare or support a fiduciary income tax return for an estate or trust. It identifies the client, fiduciary, services, responsibilities, fees, and authorization terms before work begins. The letter is not Form 1041 itself and does not replace IRS filing requirements. Upload the completed document to signNow, review detected fillable fields, assign signer roles, collect signatures, and preserve the completed letter with its audit trail.
Who uses this fiduciary tax letter
Tax practitioners
Tax professionals use the letter to document the scope, responsibilities, and authorization for preparing fiduciary income tax work for estates and trusts. The signed record helps connect the engagement terms to the client matter and preserves evidence of approval before preparation begins.
Fiduciaries
Executors, trustees, and estate administrators review and sign the engagement terms for the estate or trust. They can receive the document remotely, confirm the agreed services and fees, and retain the completed letter with fiduciary tax records.
Complete the fiduciary engagement letter online
Prepare the document once, then use signNow to identify fields, route the letter, and preserve signing evidence.
Upload letter:
Upload the completed fiduciary engagement letter to signNow. Check fields:
Review detected fields and add missing signer fields. Assign roles:
Assign the fiduciary and tax professional signing roles. Complete signing:
Send the letter, collect signatures, and save the audit trail.
Recommended setup for the fiduciary tax letter
Use a controlled signing workflow that identifies the fiduciary, preserves authorization, and keeps the completed letter with the related tax records.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps and signer actions |
| Document retention | Three years from filing under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 encryption |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Platform requirements for signing
Use signNow through Chrome, Firefox, Safari, or Edge on Windows or macOS. Fiduciaries can also review and sign the General Engagement Letter For Fiduciary Form 1041 Tax through the signNow apps for iOS and Android.
Browsers Chrome, Firefox, Safari, Edge Desktop systems Windows and macOS desktop access Mobile apps iOS and Android signNow apps
A tax practice should manage access through approved devices and user permissions when the letter contains taxpayer or fiduciary information. Confirm that recipients can open, review, sign, and download the completed record before sending, especially when the matter requires an exported audit trail for IRS-related workpapers.
How the fiduciary letter audit trail works
The audit trail connects each signature on the fiduciary tax engagement letter to identifiable events and a retrievable completed record.
Authenticate signer:
Capture timestamp:
Link document:
Seal record:
Track actions:
Retrieve evidence:
Retention periods for fiduciary tax records
Retention depends on the federal tax limitation period and any longer state or professional-record requirement applying to the estate or trust.
Three years from filing
Six years when understatement exceeds 25 percent
Indefinite for fraud or no return
Through the applicable IRS period
Longer state period if required
Recordkeeping practices for fiduciary tax engagements
Retain the letter with the supporting records, preserve proof of signing, and apply the applicable IRS limitation period.
Apply the IRS retention period
Export the audit trail
Restrict taxpayer information access
Archive records by tax year
Risks of incomplete engagement records
Authority gap
Fee dispute
Unclear authorization
Recordkeeping failure



Troubleshooting fiduciary engagement letter signing
Resolve field, signer, consent, plan, validity, and retention questions before relying on the completed fiduciary tax engagement record.
Upload the engagement letter as a supported document, then use signNow’s field tools to place or correct signature, date, and text fields. The Business plan includes templates and audit trails, allowing the tax practice to reuse a reviewed fiduciary letter without recreating fields.
Confirm the fiduciary’s email address, resend the signing invitation, or create a signing link when appropriate. If stronger proof is needed, configure SMS OTP or another available authentication method and preserve the resulting event in the audit trail.
Business is listed at $8 per user per month with annual billing and includes legally binding eSignatures and audit trails. It includes 100 signature invites per user per year; additional invite pricing depends on the plan and usage.
The signed letter can be used as electronic evidence when the signer demonstrates intent, consents to electronic records, can access the record, and the record remains reproducible. ESIGN, 15 U.S.C. ch. 96, and applicable UETA rules govern electronic transactions; they do not replace IRS filing rules.
For a consumer-facing transaction, review the ESIGN consumer-disclosure requirements in 15 U.S.C. §7001(c), including paper-record rights, electronic-access capability, and withdrawal procedures. A fiduciary tax engagement should also identify the correct fiduciary and preserve the completed record.
Export the completed PDF and audit trail from signNow, then store both with the estate or trust’s tax workpapers. Apply IRC §6501(a): three years from filing, six years for a greater-than-25-percent understatement, and indefinite retention for fraud or no return.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.