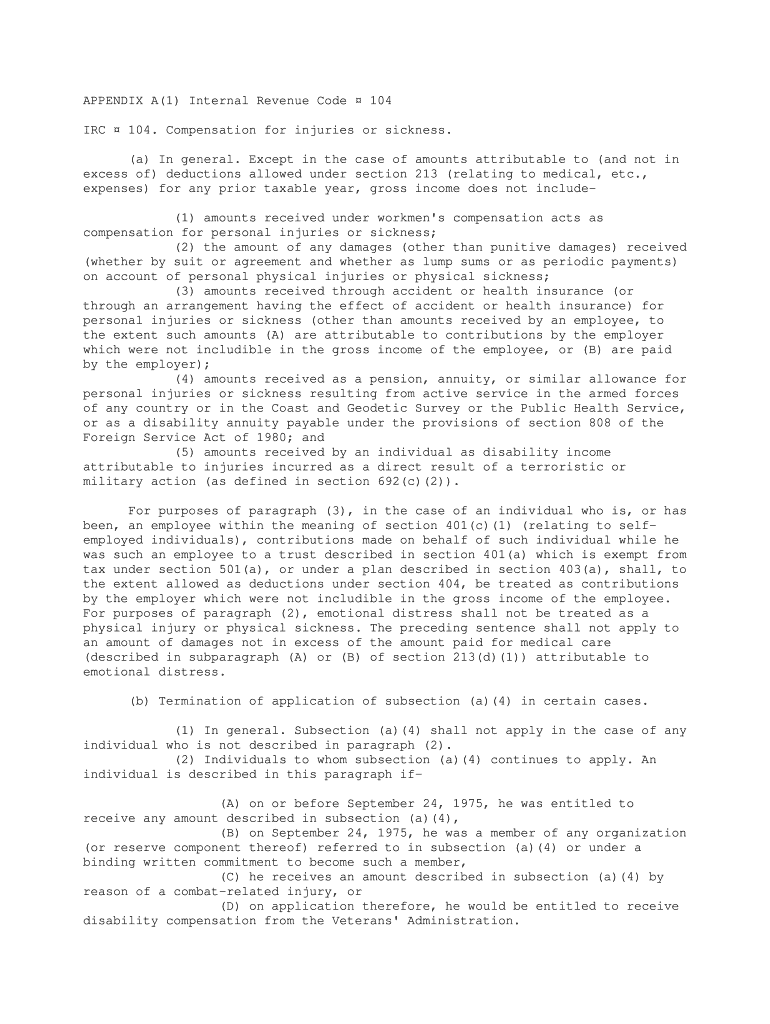
26 U S C 104 U S Code Title 26 Internal Revenue Code Form
Use a 26 U S C 104 U S Code Title 26 Internal Revenue Code template to make your document workflow more streamlined.
What this Internal Revenue Code form does
The 26 U S C 104 U S Code Title 26 Internal Revenue Code Form is a tax-related record identified by its reference to 26 U.S.C. §104, which addresses exclusions from gross income for certain compensation connected with personal injuries or sickness. The exact applicable exclusion depends on the payment and underlying facts, so the form should identify the transaction accurately and be reviewed against the Internal Revenue Code and IRS guidance. signNow can convert an uploaded document into a fillable workflow, collect an intentional electronic signature, and preserve the completed record with an audit trail.
Who uses this tax form
Financial services
Payers and tax departments can prepare the form, verify taxpayer information, and retain signed evidence alongside payment records and related tax documentation.
Tax and legal practices
Tax professionals and legal teams can route the document for review, capture an authorized signature, and preserve the completed record for federal and state inquiries.
How to complete this form
Use this workflow to prepare, sign, and preserve the 26 U S C 104 U S Code Title 26 Internal Revenue Code Form.
Upload:
Upload the source document Complete fields:
Review detected fields and add missing taxpayer information. Send:
Assign the authorized signer and send the document. Archive:
Sign, download, and retain the completed form with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended workflow setup
Configure the form around signer identity, evidence preservation, and the applicable federal tax record period.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps, IP address, and actions |
| Document retention | Apply IRC §6501(a) retention rules |
| Encryption | TLS 1.2/1.3 and AES-256 protection |
Audit trail for this form
The signNow audit trail links the completed 26 U S C 104 U S Code Title 26 Internal Revenue Code Form to its signing events and preserved evidence.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Log activity:
Export evidence:
Retention periods for tax records
Retention depends on the tax record and the circumstances described in IRC §6501(a).
Three years from filing
Six years for 25% understatement
Indefinite for fraudulent returns
Indefinite without a return
State rules may require longer
Record-keeping practices for this form
Accurate retention protects the tax information and signing evidence associated with this form.
Retain the form and audit trail
Export completion evidence promptly
Limit access to taxpayer information
Review taxpayer details before signing
Risks of inaccurate completion
Mismatched identity
Incomplete execution
Reporting error
Privacy breach



Troubleshooting this tax form workflow
Resolve field, signature, consent, plan-limit, and retention questions before relying on the completed tax record.
Upload the form as a PDF, then use signNow field detection and inspect every detected field manually. The sender remains responsible for confirming taxpayer information, signature placement, and document completeness before sending.
The Business plan costs $8 per user per month with annual billing and includes legally binding eSignatures and audit trails. Confirm the current plan terms before sending this tax record.
The Business plan includes 100 signature invites per user per year, with overage fees. Business Premium adds bulk send, while Enterprise adds advanced signer authentication; verify volume needs before selecting a plan.
SignNow supports ESIGN and UETA compliance, but electronic validity does not decide whether a payment qualifies under IRC §104. Review the payment facts and applicable IRS guidance separately.
For consumer-facing electronic records, ESIGN requires disclosure of the right to paper, electronic-access capability, and withdrawal procedures under 15 U.S.C. §7001(c). Configure and document that process before collection.
Export the signed PDF and audit trail, then apply the relevant IRC §6501(a) retention period. Keep records three years from filing, six years for a 25% understatement, or longer when applicable.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.