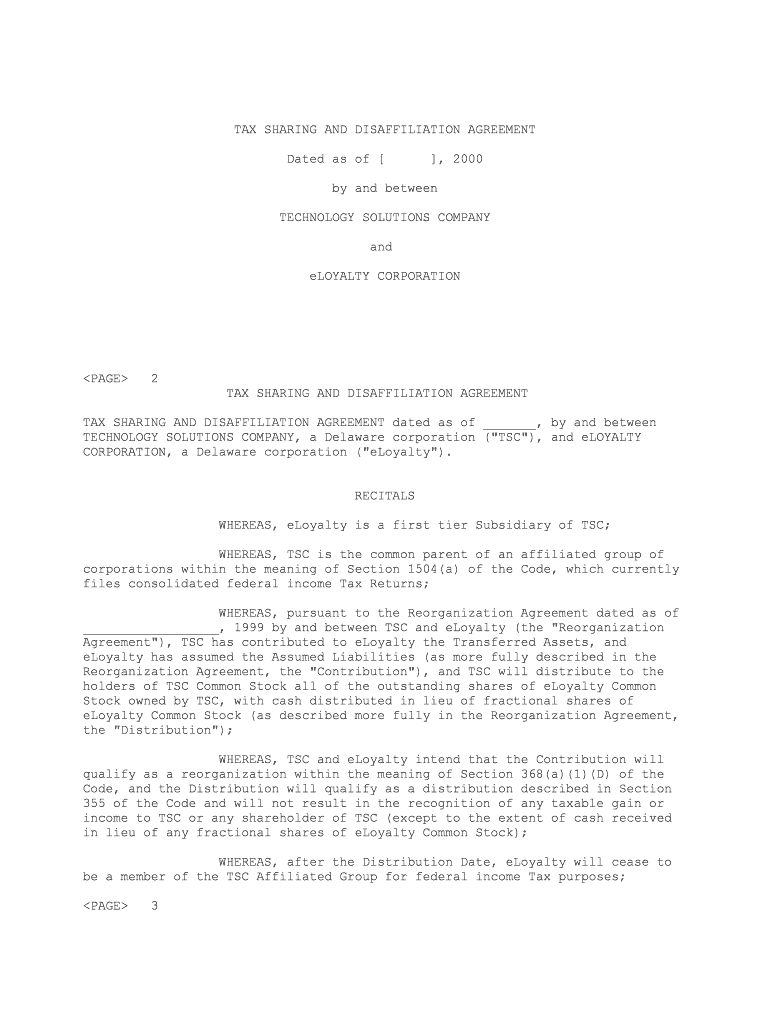
Tax Sharing And Disaffiliation Agreement Technology Form
Use a Tax Sharing And Disaffiliation Agreement Technology template to make your document workflow more streamlined.
What this tax-sharing agreement does
A Tax Sharing And Disaffiliation Agreement Technology Form records how affiliated companies allocate tax liabilities, benefits, payments, and responsibilities before or after a corporate separation. It identifies the participating entities, effective dates, allocation method, payment obligations, information-sharing duties, and signatures that make the arrangement auditable. Upload the agreement to signNow, let the platform auto-detect fillable fields, assign authorized representatives, and send it for electronic signature. ESIGN and UETA can support electronic execution when intent, consent, attribution, and record retention requirements are satisfied; tax counsel should confirm the agreement’s governing law.
Who uses this tax-sharing agreement
Corporate tax groups
Parent companies, subsidiaries, and tax departments use the agreement to document how tax liabilities, benefits, filings, and payments are allocated within a consolidated or affiliated corporate structure. Legal and finance teams should confirm authority, defined entities, effective dates, and state-law requirements before execution.
Advisers and counsel
Accounting firms and transaction counsel use the form to coordinate signatures, preserve the executed allocation terms, and support later audits or post-separation reconciliation. The agreement should identify responsible entities clearly and should not replace professional review of applicable tax rules.
How this agreement workflow works
A tax-sharing agreement moves from controlled preparation to authorized signatures, with the completed record and audit trail retained together.
Upload document: Upload the agreement PDF to signNow. Prepare fields: Auto-detect fillable fields and review placement. Add signers: Assign entities or representatives as signers. Complete and archive: Collect signatures and store the completed agreement.
Complete the agreement in four steps
Prepare the exact tax-sharing terms first, then use signNow to route the agreement to authorized representatives and preserve completion evidence.
Upload agreement:
Upload the approved agreement PDF. Check fields:
Review auto-detected fields and add missing fields. Assign signers:
Assign authorized representatives to each signature field. Complete signing:
Send, monitor, and download the completed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended agreement workflow setup
Use controlled signer access, a reviewed agreement version, and an auditable record for each affiliated entity.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps, IP addresses, and actions |
| Document retention | Retain under applicable tax and state policy |
| Encryption | TLS 1.2/1.3 and AES-256 encryption |
What the agreement audit trail records
The audit trail preserves evidence about who accessed, reviewed, signed, and completed the tax-sharing agreement.
Authenticate signer:
Timestamp actions:
Hash document:
Seal document:
Retrieve evidence:
Archive record:
Signer authentication and certificates
PKI-based signing:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
21 CFR Part 11:
Retention periods for agreement records
Keep the executed agreement and its audit trail for the longest period required by the related tax record, corporate record, or state rule.
Three years for tax records
Six years for understatement
Indefinite for fraud
Longer period under state law
Longest applicable requirement
Risks from incomplete execution
Tax allocation dispute
Electronic consent gap
Authority challenge
Evidence retention failure
Privacy and disclosure pitfalls to avoid
Personal information may appear in tax-sharing schedules, so limit document access and remove unrelated identifiers before sending. Missing electronic consent language can weaken evidence that each party agreed to transact and sign the agreement electronically. Unrestricted access may let unauthorized staff view intercompany tax allocations, termination terms, or confidential financial information. Sending the wrong agreement version can create conflicting obligations between affiliated companies and complicate later reconciliation.
Legal standing and document limits
For U.S. business transactions, an electronic tax-sharing agreement may be admissible when the parties demonstrate intent, consent, attribution, and reliable record retention under ESIGN, 15 U.S.C. ch. 96, and applicable state law such as UETA. Wills, certain court orders, family-law decrees, and other statutory exceptions remain outside ESIGN’s electronic-record framework.

Troubleshooting this tax-sharing agreement
Resolve field, plan, signature, accuracy, and retention questions before distributing the agreement to affiliated entities.
Upload the final PDF again and check whether text is selectable. If fields are not detected, place signature, date, and initials fields manually before sending the agreement.
Use signNow’s Business plan for legally binding eSignatures, templates, and audit trails at $8/user/month when billed annually. Confirm that the selected plan meets your organization’s authentication and retention requirements.
Business Premium adds bulk send and kiosk mode at $15/user/month billed annually. Those features help only when the same approved agreement must be distributed repeatedly or signed in person by multiple representatives.
Electronic execution can be supported under ESIGN and UETA when intent, consent, attribution, and record retention are established. For consumer-facing transactions, review the ESIGN disclosure requirements in 15 U.S.C. §7001(c).
Review every entity name, allocation percentage, effective date, payment term, and representative before sending. A completed audit trail documents the signing event but does not correct an inaccurate tax allocation.
Export the completed agreement and audit trail from signNow, then store them under the organization’s approved retention policy. Tax and corporate records may require different periods under applicable federal and state rules.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.