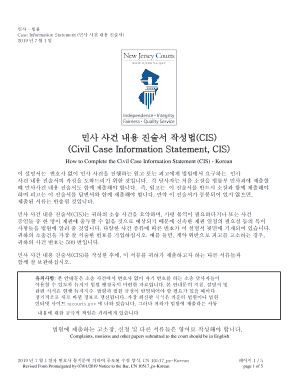
IRS Publication 519 Internal Revenue Service Form
Use a IRS Publication 519 Internal Revenue Service template to make your document workflow more streamlined.
What IRS Publication 519 explains
IRS Publication 519 is an Internal Revenue Service guide explaining how U.S. tax rules apply to nonresident and resident aliens. It is not itself a return, application, or signature form. The publication discusses the substantial presence test, residency elections, income connected with a U.S. trade or business, deductions, treaty positions, and filing responsibilities. Readers use its explanations to determine which separate IRS return or information form may apply. Because tax outcomes depend on facts and current law, confirm the applicable filing instructions and treaty provisions before submitting records.
Review Publication 519 correctly
Use Publication 519 as tax guidance, then complete the separate IRS forms it identifies for your circumstances.
Confirm scope:
Confirm that Publication 519 applies to your U.S. tax situation. Review guidance:
Review residency, source-of-income, and treaty guidance in the publication. Gather records:
Gather passport, visa, travel, and income records supporting your analysis. Prepare returns:
Complete any required IRS return or withholding form separately.
Set up related IRS workflows
Configure signNow for separate IRS documents informed by Publication 519, while preserving the guide as reference material.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps, IP address, and signer actions |
| Document retention | Keep tax records three years from filing (IRC §6501(a)) |
| Encryption | Use TLS 1.2/1.3 and AES-256 |
Choose the right signing method
- Use the web app to upload Publication 519 or related IRS records, then prepare separate forms identified by the guide.
- Use the mobile app to review tax-reference documents and capture supporting records while traveling or working remotely.
- Use kiosk mode for supervised, in-person completion of a separate signable IRS document, not as a substitute for Publication 519.
- Use a shareable signing link when an identified IRS form requires a signer’s electronic consent and audit trail.
Trace related document activity
For a separate signable IRS document, signNow records the events needed to show who acted, when, and what was completed.
Signer authentication:
Timestamp capture:
Document hashing:
Sealing evidence:
Action logging:
Audit export:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Features for Publication 519 workflows
Publication 519 is reference guidance, while signNow helps organize and sign separate IRS documents that follow from the tax analysis.
Scope clarity
Separates Publication 519’s tax explanations from the actual return or information form requiring completion, reducing the risk of treating guidance as a filed document.
Residency review
Organizes residency and substantial-presence analysis before users prepare the applicable IRS return or withholding paperwork.
Document workflow
Supports electronic completion of a separate signable document with signer actions, timestamps, and an exportable audit trail.
Evidence control
Keeps supporting travel, visa, income, and tax records associated with the relevant review process.
Data protection
Applies access controls and encrypted storage to sensitive taxpayer information handled during document preparation.
Named integrations
Connects related workflows with systems such as Google Drive, Box, NetSuite, and Microsoft 365.
Protect related tax documents
Transport encryption:
Storage encryption:
Independent controls:
Security management:
U.S. eSignature law:
Protected health information:
Access related documents securely
Use signNow through Chrome, Firefox, Safari, or Edge on Windows and macOS, or through its iOS and Android mobile apps. TLS 1.2/1.3 protects data in transit.
Browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile apps iOS and Android mobile apps
Teams handling taxpayer information should manage devices, permissions, and retention centrally. Review whether API access, SSO provisioning, or additional authentication is needed for the separate IRS documents created after applying Publication 519.


Process related IRS documents
Publication 519 has no signing deadline; deadlines belong to the separate IRS return or form selected after review.
Document preparation
Delivery to signers
Signer turnaround
Completion and archival
Retain records supporting tax analysis
Retention depends on the return, the facts, and applicable federal or state rules; Publication 519 itself does not create a universal retention period.
Three years after filing
Six years for understatement
Indefinite for fraud
Indefinite without return
State rules may extend retention
Risks from misusing the guide
Tax misclassification
Lost treaty benefit
Audit evidence gap
Late-filing penalties
Avoid Publication 519 mistakes
Publication 519 explains tax treatment but does not replace the IRS return, withholding certificate, or information form required by the reader’s facts. Residency conclusions can change when travel days, visa status, treaty elections, or closer-connection facts are recorded incorrectly. Taxpayer identification, income-source, and filing-status information may be copied inaccurately from supporting records into a separate IRS form. Using an electronic signature workflow does not itself determine whether the IRS accepts a specific form or filing method.
Troubleshoot Publication 519 workflows
Resolve the tax-classification issue first, then verify the separate IRS document’s signing and retention requirements.
Publication 519 is IRS guidance, not a filing form. Use it to determine whether a separate return, withholding certificate, treaty statement, or information form applies, then follow that document’s current IRS instructions and submission method.
Count U.S. presence days using the substantial presence test described in Publication 519, including the applicable weighted calculation. Confirm exceptions, exempt individual rules, and closer-connection provisions against current IRS instructions before classifying residency.
signNow can upload and route a separate signable IRS document, but electronic completion does not guarantee IRS acceptance. Check the applicable form instructions for signature, wet-signature, mailing, and electronic-submission requirements.
The signNow Business plan is listed at $8 per user per month with annual billing and includes audit trails and templates. Publication 519 remains a reference document, so only separate signable workflows consume signature invites.
For consumer-facing electronic records, ESIGN requires disclosure of the right to paper records, access capability, and withdrawal procedures under 15 U.S.C. §7001(c). Configure the workflow accordingly when the recipient is a consumer.
Keep supporting tax records according to the applicable rule. IRC §6501(a) generally uses three years after filing, six years for certain substantial understatements, and no limit for fraud or no filed return; state requirements may differ.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.