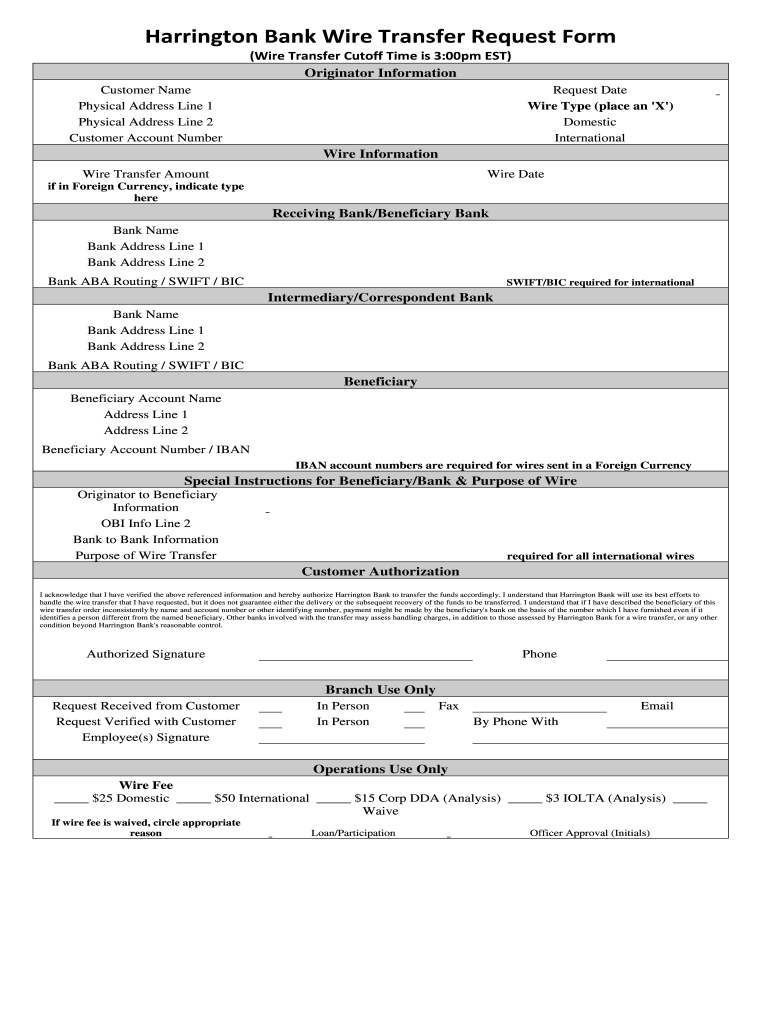
Generic Wire Transfer Form
Create a custom Generic Wire Transfer Form 0 that meets your industry’s specifications.
What a Generic Wire Transfer Form records
A Generic Wire Transfer Form records the banking and approval information a business uses to request or authorize a wire payment. It commonly identifies the sender, beneficiary, financial institution, routing and account details, amount, currency, purpose, and approving signer; the exact fields depend on the organization’s template and bank requirements. signNow lets a sender upload the document, detect or place fillable fields, route it to designated signers, and preserve the completed record with an audit trail. It does not itself move funds or replace bank verification, sanctions screening, or internal payment controls.
Who uses this wire transfer form
Finance and treasury
Treasury teams use Generic Wire Transfer Form to document beneficiary details, bank instructions, transfer amount, currency, purpose, and approval before payment release. signNow lets authorized staff upload the form, place or detect fields, route it for signature, and retain the completed record with an audit trail.
Business operations
Operations, legal, and accounting teams use the form when a business needs documented authorization for a supplier, client, intercompany, or settlement payment. The workflow supports remote review, controlled signer order, and a reproducible record without treating the form as a bank-issued payment instruction.
Complete the wire transfer form in signNow
Follow these steps to prepare the form, collect approval, and preserve evidence of the completed wire transfer authorization.
Upload form:
Upload the completed Generic Wire Transfer Form. Check fields:
Review detected fields and add missing bank fields. Assign signers:
Assign recipients and set signing order. Send form:
Send the form for electronic approval. Store record:
Download the signed PDF and audit trail.
How the signNow workflow works
signNow turns the prepared wire transfer document into a controlled approval workflow without initiating the underlying bank payment.
Upload document: Upload the wire transfer PDF to signNow. Prepare fields: Auto-detect or place fields for banking details. Send approval: Route the form to authorized signers. Preserve evidence: Store the signed document with its audit trail.
Configure a secure wire transfer workflow
Use these recommendations to prepare, authenticate, sign, and retain Generic Wire Transfer Form records for U.S. business transactions.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture signer, timestamp, IP, and actions |
| Document retention | Retain transaction records under company policy |
| Encryption | TLS 1.2 or 1.3 and AES-256 |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.



Platform requirements for wire transfer forms
Generic Wire Transfer Form can be prepared in Chrome, Firefox, Safari, or Edge on Windows and macOS. signNow also provides mobile apps for iOS and Android, while secure sessions use TLS 1.2 or TLS 1.3.
Desktop browsers Chrome, Firefox, Safari, and Edge on Windows or macOS Mobile apps signNow mobile apps for iOS and Android Connection security TLS 1.2 or 1.3 for secure browser sessions
Organizations should manage access through approved Windows, macOS, iOS, or Android devices and restrict downloaded wire transfer records. Teams using API access, SSO provisioning, or regulated workflows should confirm their signNow plan, identity controls, and retention configuration before deployment.
Record-keeping practices for wire transfers
Accurate fields, documented approval, and controlled retention make Generic Wire Transfer Form records easier to reconcile and defend.
Verify every banking field before signature
Export signed records and audit evidence
Map retention to the underlying record
Separate preparation and payment approval
Retention periods for wire transfer records
Keep the signed form, completion certificate, and supporting payment evidence according to the underlying tax, banking, contractual, and state requirements.
Three years from tax filing
Six years for major understatement
Indefinite period for fraud
Policy period for bank records
Documented policy period
Challenges when completing wire transfer forms
Incorrect routing or account numbers can redirect funds, so compare every banking field with an independently verified instruction before approval. Missing purpose, currency, beneficiary, or authorization details can delay reconciliation and make the completed transfer record difficult to interpret. Uncontrolled access to signed wire instructions can expose account information or allow unauthorized edits before final approval. A retained signature without its audit trail may provide weaker evidence of signer identity, timing, and transaction history during a dispute.
Risks of incomplete wire authorization
Misdirected funds
Weak authorization evidence
Reduced dispute evidence
Confidentiality exposure
Legal standing of electronic approval
A signed Generic Wire Transfer Form can provide evidence of intent, attribution, consent, and record integrity when the transaction satisfies the federal ESIGN Act, 15 U.S.C. ch. 96, and applicable state UETA or New York ESRA requirements. It does not replace bank controls, notarization, or excluded records such as wills and court filings.

Protect wire transfer records
Data in transit:
Data at rest:
Security assurance:
Information security:
Electronic signatures:
Completion evidence:
Troubleshoot Generic Wire Transfer Form issues
Resolve field-detection, consent, authentication, and audit-trail questions before releasing a wire transfer for processing.
Upload the original PDF or a clear scan, then review signNow’s detected fields before sending. If a bank field is missed, add it manually and assign the correct signer rather than relying on an incomplete template.
The Business plan includes templates and audit trails; Business Premium adds bulk send. For a single wire transfer, place fields manually or update the template, then verify routing and account numbers before delivery.
signNow supports legally binding electronic signatures and audit trails under its ESIGN and UETA compliance program. The record should show intent, signer attribution, consent, and a retained reproducible copy under 15 U.S.C. ch. 96 and applicable state law.
For consumer-facing transactions, provide the ESIGN consumer disclosure and confirm electronic access before signing. Under 15 U.S.C. §7001(c), consumers must be able to retain records and understand how to withdraw consent.
Business Premium includes bulk send, while Enterprise adds advanced signer authentication. If a bank or internal policy requires stronger identity proofing, configure the available authentication method before sending the form.
Use signNow’s audit trail and completion certificate to investigate a disputed authorization. Review signer identity, timestamps, IP information, and action history, then compare the signed bank details with the institution’s independent instructions.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.