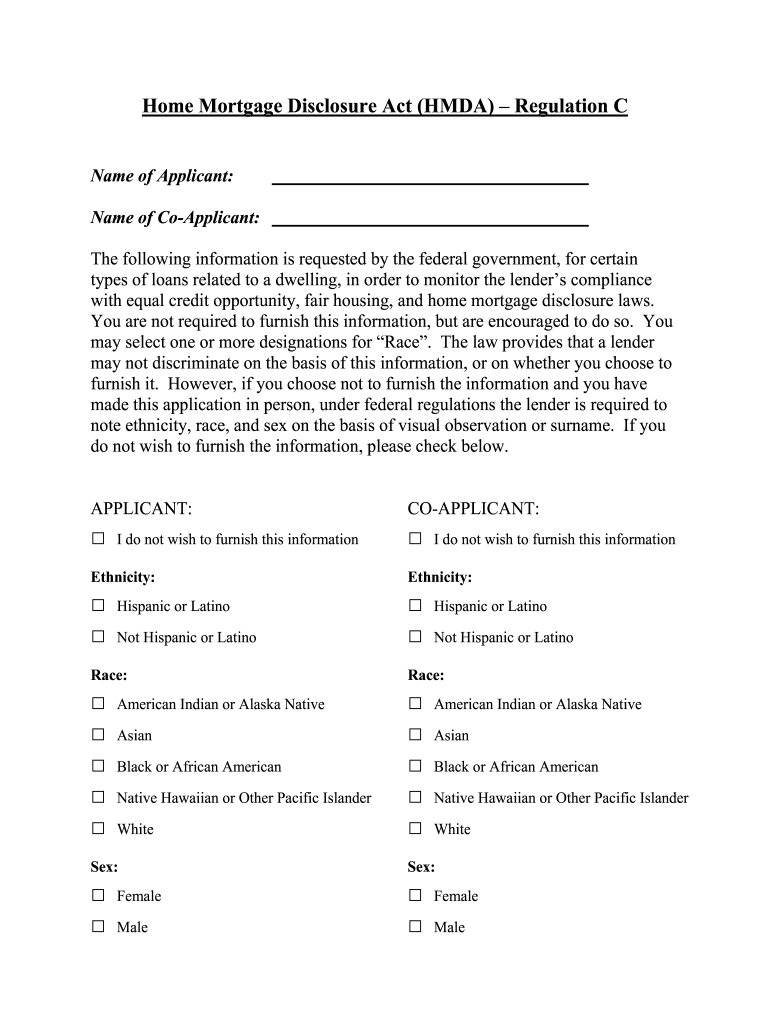
Get The Get The Get The Hmda Form St Mary's Bank
Create a custom Get The Get The Get The HMDA Form St Mary's Bank 0 that meets your industry’s specifications.
What the HMDA form records
The HMDA form is a mortgage-lending data report used to record application, origination, pricing, property, and applicant information for covered transactions. A bank or other covered financial institution gathers the required fields during its lending workflow, reviews them for accuracy, and submits the applicable loan-level data under Regulation C, 12 CFR part 1003. signNow can help teams complete designated fields, route internal approvals, obtain signatures where required, and preserve the completed record with an audit trail, but it does not determine whether a transaction is reportable.
Who works with this HMDA form
Mortgage lenders
Mortgage lenders use the form to coordinate application, property, underwriting, pricing, and action data before HMDA reporting. Accuracy reviews help align source documents with Regulation C requirements.
Compliance teams
Compliance teams use controlled templates, approvals, and audit records to document who entered, reviewed, and changed HMDA-related information before submission.
Organizations that use HMDA workflows
The form is most useful where mortgage-lending data must move through defined entry, review, approval, and recordkeeping responsibilities.
Community banks can use controlled HMDA templates to collect application and property details consistently across branches, then route records to compliance reviewers before reporting decisions are finalized. Mortgage lenders can connect loan-document workflows with operational systems, assign data-entry and review roles, and preserve evidence showing how each HMDA-related record moved through approval. Enterprise financial institutions can combine role-based access, audit trails, SSO, and API connections when processing high volumes of mortgage applications across multiple business units.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features that support HMDA document handling
signNow organizes the document workflow around field review, role-based routing, electronic signatures, and evidence preservation for lender records.
Document upload
Upload the lender’s HMDA document and identify fields before routing it for review or signature.
Field review
Use detected fields as a starting point, then verify every field against source records and approved instructions.
Role routing
Assign data-entry, review, and signing responsibilities so each action has a traceable owner.
Audit trail
Capture timestamps, actions, and completion history with the signed HMDA-related document.
Mobile access
Review or sign assigned documents from supported desktop browsers and mobile apps.
System connections
Connect approved documents with systems such as Microsoft 365, Google Drive, Salesforce, or NetSuite.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Complete the HMDA document in signNow
Use this sequence to prepare the HMDA document while keeping regulatory review separate from the electronic signing workflow.
Upload document:
Upload the HMDA document to signNow. Check fields:
Review detected fields and add missing fields. Assign roles:
Assign reviewers or signers by role. Send document:
Send the document through the approved workflow. Store record:
Review the completed file and audit trail.



Recommended HMDA workflow setup
Use controlled access, documented review, and an exportable audit history for HMDA-related records.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Retain completed history with document |
| Document retention | Follow institution policy and Regulation C |
| Encryption | TLS 1.2/1.3 and AES-256 |
How the HMDA audit trail is built
The audit trail records evidence around each HMDA document event, helping reviewers connect the completed file with its signing and handling history.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Log actions:
Export history:
Authentication for HMDA records
PKI certificates:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Advanced authentication:
Platform requirements for HMDA workflows
The signNow web experience supports Chrome, Firefox, Safari, and Edge on Windows and macOS. Mobile apps are available for iOS and Android, allowing authorized users to review or sign assigned documents. Use TLS-protected connections when accessing applicant and loan information.
Browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile systems iOS and Android mobile apps
Lending organizations should use managed Windows, macOS, iOS, or Android devices, enforce account permissions, and restrict downloads to approved locations. Enterprise deployments may use SSO and advanced integrations; configure retention, access, and export procedures separately to meet Regulation C, privacy, and internal records policies.
Privacy and disclosure pitfalls
Applicant names, addresses, demographic information, and loan details may appear together, increasing exposure if access permissions are too broad. A consumer-facing electronic process may require disclosure of paper-record rights, electronic access, and withdrawal procedures under 15 U.S.C. §7001(c). Shared templates can preserve an outdated HMDA field or instruction, causing inconsistent data collection across loan officers and branches. Sending a completed HMDA-related file to the wrong recipient can disclose sensitive applicant or property information.
Risks of mishandling HMDA records
Reporting gap
Review error
Audit weakness
Privacy exposure
HMDA form troubleshooting
Use the answers below to distinguish signNow workflow settings from the lender’s separate HMDA reporting obligations under Regulation C.
Business provides legally binding eSignatures, audit trails, templates, and mobile apps for completing and routing the HMDA document. Business includes 100 signature invites per user annually; overage fees may apply.
Business Premium adds bulk send, kiosk mode, request payments, and quick invite links. It is useful when a lender sends the same approved HMDA-related package to multiple recipients, but the plan does not replace Regulation C reporting controls.
The 7-day free trial requires no credit card. Before using it for production HMDA workflows, confirm user access, template permissions, retention procedures, and the organization’s reporting controls.
signNow states that ESIGN and UETA compliance supports electronic signatures and records. The institution must still establish intent, consent where required, signer attribution, accurate reproduction, and compliance with Regulation C and applicable privacy rules.
Use signNow templates and role-based routing to separate data entry from review. Verify every field against the lender’s source records because signNow does not decide whether an application or loan is reportable.
Business provides audit trails, while Enterprise adds advanced signer authentication and integrations. Site License adds full API and SSO options, with HIPAA and 21 CFR Part 11 available as add-ons; choose controls based on the institution’s risk assessment.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.