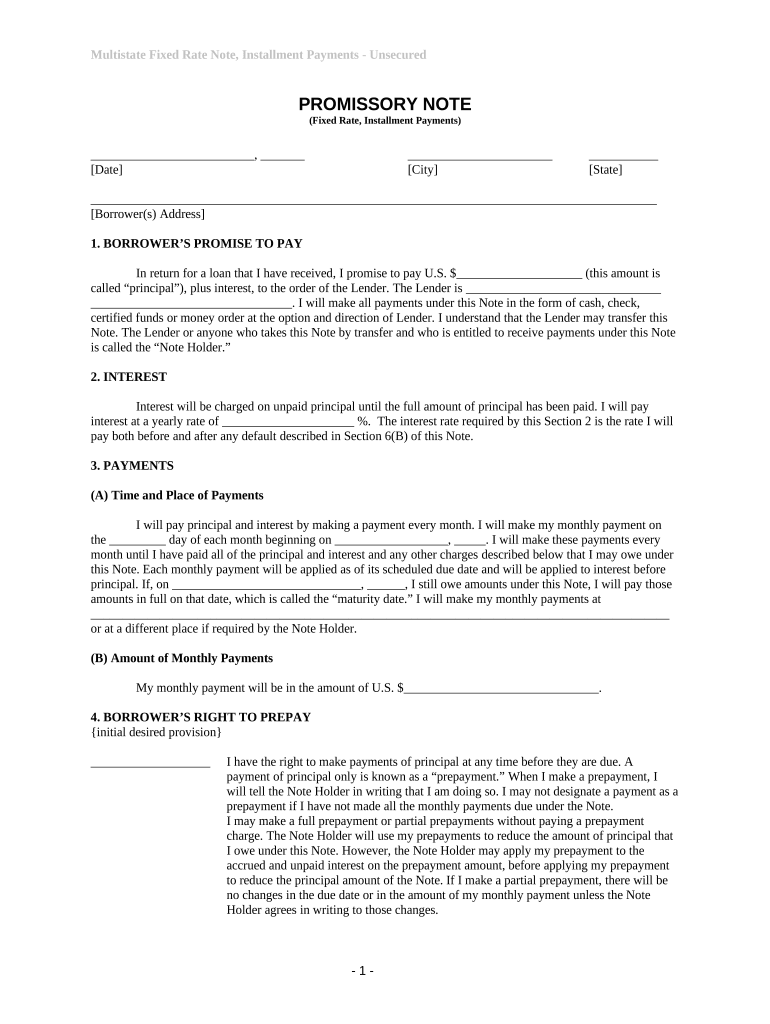
Montana Unsecured Installment Payment Promissory Note For Fixed Rate Montana Form
Use a Montana Unsecured Installment Payment Promissory Note For Fixed Rate Montana template to make your document workflow more streamlined.
What this Montana promissory note does
This Montana form records a borrower’s promise to repay an unsecured loan through fixed installment payments. It identifies the lender and borrower, states the principal, fixed interest rate, payment schedule, maturity date, late-payment terms, and governing-law provisions, while documenting that no collateral secures the obligation. The borrower signs to acknowledge the debt, and the lender keeps the executed note as evidence of the agreed repayment terms. Because enforceability depends on accurate terms, capacity, consent, and applicable Montana law, parties should obtain legal advice for unusual transactions or disputed provisions.
Who uses this promissory note
Small lenders
Montana small-business lenders document fixed-rate unsecured financing without collateral schedules.
Borrowers and counsel
Borrowers and counsel review principal, installments, maturity, and default terms before signing.
Key features for this Montana note
signNow connects the note’s repayment terms, signer routing, execution evidence, and retained records in one document workflow.
Structured terms
Place the principal, fixed rate, installment amount, due dates, and maturity date in a structured note before circulation, reducing omissions that can create repayment disputes.
Signer routing
Send the completed Montana note to identified parties in signing order, keeping borrower and lender actions tied to the same document record.
Audit trail
Capture signatures, timestamps, and transaction activity with the completed note so parties can demonstrate how the repayment agreement was executed.
Record retention
Keep the signed note and completion record together, allowing a lender to retrieve the exact fixed-rate terms if payment performance is questioned.
Mobile access
Use mobile signing when lender or borrower is away from the office, while preserving the same note version and signing history.
Controlled access
Apply role-based access and stronger authentication when the note includes sensitive financial information or multiple internal reviewers.
How to complete this Montana note
Prepare the fixed-rate repayment terms, verify every party’s details, and use signNow to create an auditable executed record.
Upload note:
Upload the completed Montana note. Check fields:
Review detected fields and terms. Add signers:
Add borrower and lender signers. Complete record:
Send, sign, and download records.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended workflow setup
Use a controlled signing workflow that keeps the Montana note, signer identity, execution evidence, and retention responsibility aligned.
| Setting | Recommendation |
|---|---|
| Authentication and signature | Email link with SMS verification |
| Audit trail | Retain completion certificate and activity log |
| Document retention | Follow lender policy and applicable law |
| Encryption | Use TLS and AES-256 protections |
| User provisioning | Assign lender reviewers by role |
What the audit trail records
The audit trail separates signer authentication and document-integrity evidence from the Montana note’s substantive repayment terms.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Retrieve evidence:
Archive records:
Signer authentication and certificates
Digital certificates:
Certificate format:
Two-factor access:
SMS verification:
Identity checks:
Signing evidence:
Challenges when preparing the note
Leaving the principal, fixed interest rate, installment amount, or maturity date incomplete can make the repayment obligation difficult to interpret or enforce. Using inconsistent borrower names or signing a circulated draft can create attribution problems when the lender later relies on the executed note. Treating an unsecured note like a collateralized loan can create inaccurate default remedies because the document does not identify pledged security. Failing to preserve the signed note, completion certificate, and audit trail can weaken evidence of consent, timing, and the agreed payment schedule.
Legal standing and document limits
For a Montana business transaction, an electronic note may be admissible when the parties show intent, consent, attribution, and reliable record retention under ESIGN, 15 U.S.C. chapter 96, and applicable UETA rules. Those frameworks exclude wills, codicils, testamentary trusts, court orders, and family-law decrees, so this promissory note should not be repurposed for those documents.

Documents this note cannot replace
Notarization
Wills
Family law
Real-estate deeds
Best practices for this note
Accuracy, version control, signer attribution, and documented retention matter more than speed when preparing an unsecured fixed-rate repayment obligation.
Verify every repayment term
Send one final version
Preserve execution evidence
Confirm retention requirements
Mobile options for signing
signNow mobile apps support preparing and signing this Montana promissory note on iOS and Android devices; camera capture can convert paper pages into uploadable documents.
Mobile apps iOS and Android Offline work Offline signing available Document capture Camera document capture
Use managed devices when the note contains financial or identity information. Confirm offline work is synchronized before closing the transaction, and preserve the completed PDF and audit trail according to the lender’s records policy. Mobile availability does not replace review of Montana contract requirements.
Troubleshooting this Montana promissory note
Resolve field, signing, consent, and retention questions before the fixed-rate repayment note is finalized.
Upload the final Montana note as a PDF, then review signNow’s detected fields before adding or correcting principal, interest, installment, and signature fields. Auto-detection does not validate whether the fixed rate or payment schedule complies with the parties’ agreement or Montana law.
The signNow Business plan includes legally binding eSignatures, templates, mobile apps, and audit trails. If this workflow requires bulk send, Business Premium adds that capability; confirm the selected plan’s annual or month-to-month pricing before sending multiple notes.
For a consumer-facing electronic transaction, provide the ESIGN disclosure, demonstrate access to electronic records, and explain how consent may be withdrawn under 15 U.S.C. §7001(c). signNow can capture the signing workflow, but the lender remains responsible for legally required disclosures.
If a signer cannot open the invitation, verify the email address, resend the invitation, or use a controlled signing link. SMS authentication may add identity verification. Do not substitute a different note version after signing; send the corrected document as a new transaction.
signNow records signing activity in an audit trail and retains the completed document history under its applicable controls. Export the signed PDF and audit trail together, then apply the lender’s retention policy; the platform does not determine the note’s legal limitation period.
Electronic signatures generally have legal equivalence under ESIGN, 15 U.S.C. chapter 96, and applicable UETA rules when intent, consent, attribution, and reproducible records are established. A Montana lawyer should review unusual collateral, usury, default, or consumer-credit provisions.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.