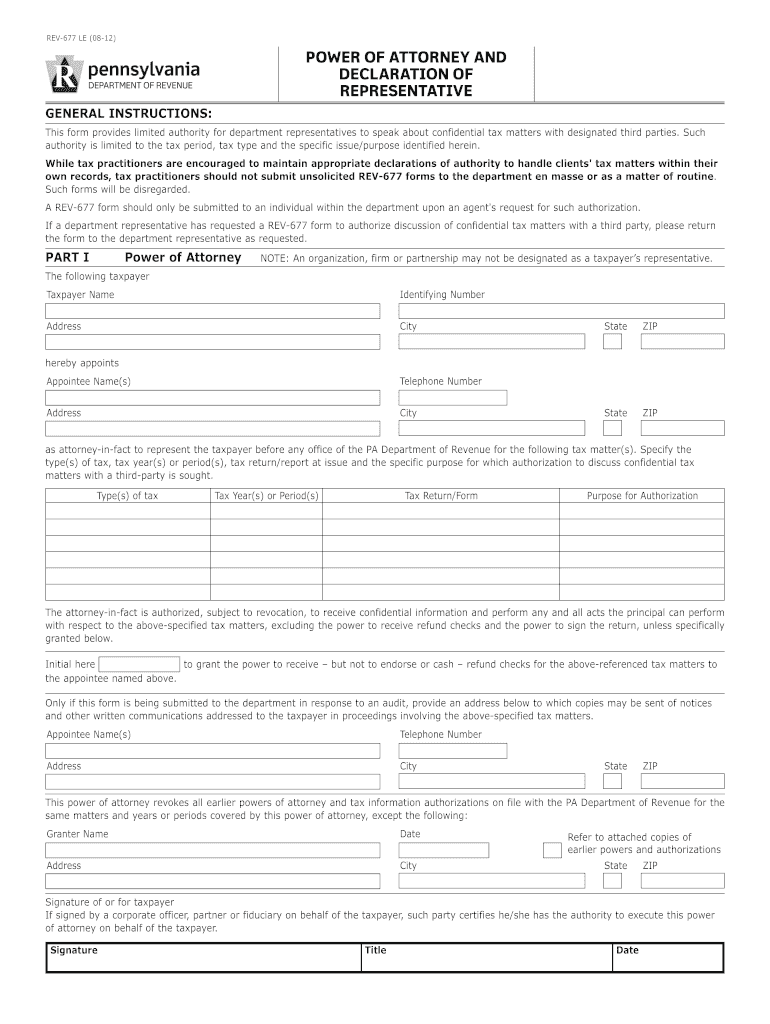
Power Of Attorney And Declaration Of Representative Rev 677
Use a Get template to make your document workflow more streamlined.
What Rev 677 does and how it works
Power Of Attorney And Declaration Of Representative Rev 677 is an authorization record that connects a taxpayer with a representative for specified tax matters. The taxpayer identifies the representative and the authority being granted, reviews the information, and signs the completed document. The representative signs where required, creating a record of consent and attribution. In signNow, you upload the form, review auto-detected fillable fields, assign each field, send it for signature, and retain the signed PDF with its audit trail. IRS instructions and applicable state law govern use, submission, and any additional formalities.
Who uses this authorization form
Taxpayers
Taxpayers use the form to authorize a named representative for specified tax matters and periods, then review the completed record before retaining or submitting it under applicable IRS instructions.
Representatives
Tax professionals and authorized representatives use the form to document delegated authority, collect taxpayer signatures, and preserve an auditable copy for the engagement file.
How the authorization moves from draft to record
The form creates a documented authorization by connecting taxpayer information, representative authority, signatures, and a retained completion record.
Identify parties: Complete taxpayer and representative information. Define authority: Specify authorized tax matters and periods. Sign the form: Collect required signatures and consent. Retain evidence: Preserve the completed record and audit trail.
Complete Rev 677 in signNow
Use this sequence to prepare the authorization, assign the parties, collect signatures, and preserve evidence of completion.
Upload form:
Upload Rev 677 into signNow. Check fields:
Review auto-detected fields and correct assignments. Add signers:
Add taxpayer and representative recipients. Send request:
Send the authorization for completion. Store record:
Download the signed form and audit trail.
Choose the signing method for your workflow
- Use the signNow web app when you need to upload the form, map fields, assign taxpayer and representative roles, and monitor completion from a desktop workflow.
- Use the signNow mobile app when a taxpayer or representative must review, complete, and sign the form from an iOS or Android device.
- Use kiosk mode when representatives assist signers at a controlled location and each taxpayer must complete the Power Of Attorney form in person.
- Use a shareable signing link when you need to distribute the prepared form through a secure channel without entering each signer’s email individually.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Authentication and certificate controls
PKI certificates:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Completion evidence:
When the form carries evidentiary weight
Power Of Attorney And Declaration Of Representative Rev 677 can support a representative’s authority when it identifies the taxpayer, representative, tax matters, and signed authorization clearly. ESIGN and applicable state electronic-transaction law may support admissibility when intent, consent, attribution, and record retention are demonstrated. Wills, codicils, testamentary trusts, and court orders remain outside ESIGN’s general coverage.

Check exclusions and state formalities
Notarization rules
Wills and codicils
Court orders
Real-estate deeds
Processing stages for the authorization form
No universal IRS turnaround period is stated here; completion depends on required parties, tax matters, and any separate filing or submission instructions.
Prepare the document
Deliver to signers
Collect signatures
Archive the record
What the audit trail records
For Rev 677, the audit trail connects signer identity, actions, timestamps, document integrity, and the final authorization record.
Authenticate signer:
Timestamp actions:
Hash document:
Seal record:
Log activity:
Export evidence:
Retention periods for related records
The correct retention period depends on the tax record and circumstances. Apply the cited federal rule only where it matches the underlying record, and check state requirements.
Three years: tax records
Six years: large understatement
Indefinite: fraudulent filing
Indefinite: no return
Document-specific schedule
Best practices for Rev 677 completion
Accuracy matters because this form connects a taxpayer with a representative and defined tax authority. Use a controlled review process before requesting signatures.
Verify every authorization detail before sending
Assign fields to the correct signer
Document consent and electronic access
Check state requirements before relying
Mobile options for Rev 677 completion
The signNow mobile workflow supports the Power Of Attorney form on iOS and Android devices, including camera-based document capture and offline signing options. Confirm current app compatibility before deployment because supported operating-system versions can change.
iOS app iOS 15 or later Android app Android 10 or later Mobile workflow Camera capture and offline signing
For regulated or distributed teams, use managed iOS or Android devices, controlled access, and documented identity procedures. Configure signer authentication according to the authority’s risk profile, preserve the completed PDF and audit trail, and verify any state-specific notarization or submission requirement separately.
Troubleshooting Rev 677 signing issues
Resolve field, plan, authentication, and legal-scope questions before treating a completed Power Of Attorney form as ready for use.
Upload the current Power Of Attorney And Declaration Of Representative Rev 677 file, then inspect signNow’s detected fields manually. Auto-detection can accelerate setup, but the sender remains responsible for assigning taxpayer and representative fields correctly before sending.
The Business plan is listed at $8 per user per month when billed annually and includes legally binding eSignatures, templates, mobile apps, and audit trails. Business Premium adds bulk send and kiosk mode at $15 per user per month annually.
signNow states that paid plans include 100 signature invites per user per year, with overage fees applying to subscription plans. Review the selected plan and invite usage before sending repeated authorization requests.
Use signNow’s audit trail to preserve timestamps, action history, and completion evidence. For legal validity, also establish intent, consent, signer attribution, and record reproduction under ESIGN’s electronic-signature framework.
HIPAA compliance is relevant only when the workflow contains protected health information; signNow states that a Business Associate Agreement is required. A tax authorization alone does not automatically create a HIPAA obligation.
If the form involves notarization, a will, codicil, testamentary trust, court order, or official court filing, do not assume an electronic workflow is sufficient. ESIGN expressly excludes several categories, so confirm the governing state and federal rule.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.