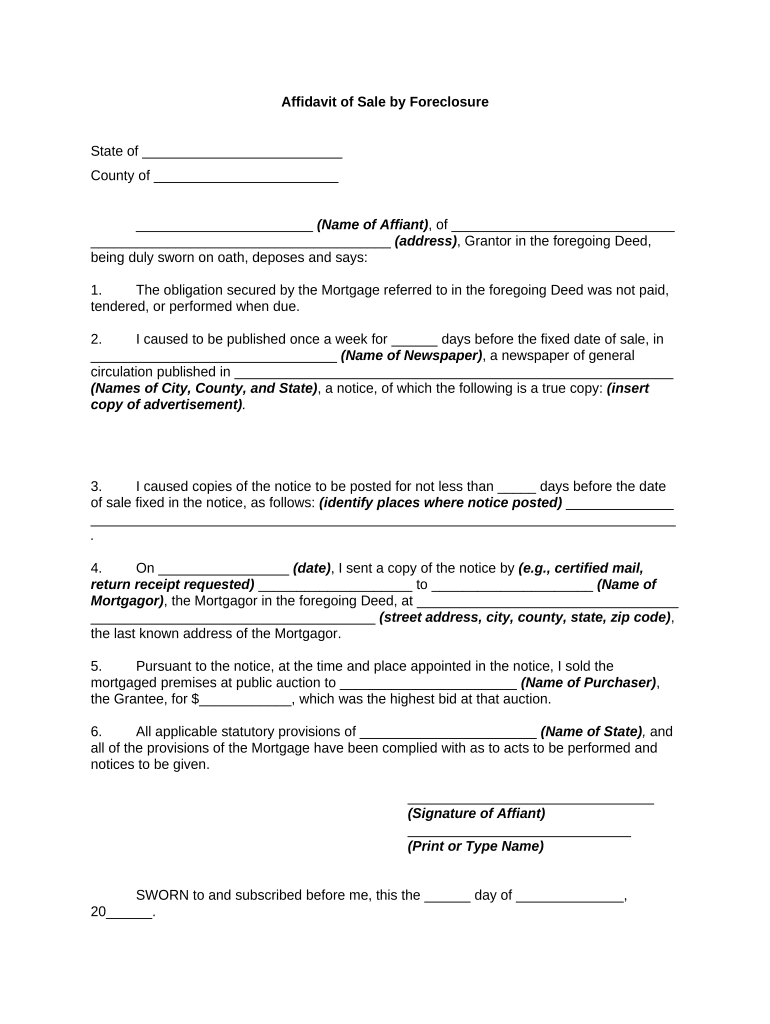
Foreclosure Form
Use a Foreclosure template to make your document workflow more streamlined.
What a foreclosure form does
A Foreclosure Form records a lender’s or servicer’s notice and supporting information about a defaulted mortgage or property matter. It may identify the borrower, property, loan, default, amounts due, cure or redemption information, and required next steps, depending on state law and the document type. Foreclosure procedures are state-specific, and notices concerning a primary residence are excluded from ESIGN’s general electronic-record rules. Before signing, serving, or filing, compare the document with the governing statute, court rule, and required delivery method.
Who handles foreclosure documents
Mortgage servicers
Mortgage servicers and foreclosure counsel use Foreclosure Form to prepare notices, document service, and preserve approval records under applicable state law.
Property stakeholders
Property owners, trustees, and legal teams review foreclosure notices, supporting facts, and delivery records before responding or filing.
Who uses foreclosure forms
Foreclosure Form is handled by servicing, legal, trustee, and property stakeholders with different review and response responsibilities.
Mortgage servicers use Foreclosure Form workflows to coordinate borrower, property, default, and amount-due information before legal review and statutory notice delivery. Their teams need controlled templates, assigned reviewers, and records showing which version was approved for the specific property matter. Foreclosure attorneys and property trustees use the form to organize notice language, supporting documents, and service evidence. They must distinguish internal electronic approvals from legally required notice delivery, especially when state law governs judicial filings, notarization, or primary-residence foreclosure notices. Borrowers and property owners use the completed notice to understand the claimed default, amounts, deadlines, and available response steps. They should verify the named lender, property address, dates, and instructions, then seek state-specific legal assistance when the notice appears inaccurate or incomplete.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How to prepare a foreclosure form
Prepare the document in signNow, verify every property and loan detail, then confirm the legally required signing and service method before completion.
Upload document:
Upload the foreclosure notice template or completed document. Check fields:
Review detected fields and add missing dates or names. Assign roles:
Assign internal reviewers and authorized recipients. Complete records:
Export records and follow the required service method.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended foreclosure document setup
Configure access, records, and delivery controls around the foreclosure notice and applicable state requirements.
| Setting | Recommendation |
|---|---|
| Authentication and provisioning | Use verified email access with administrator-controlled roles |
| Signature type | Use wet-ink or approved state-law method |
| Audit trail | Export timestamps, IP data, and action history |
| Document retention | Follow the applicable state foreclosure schedule |
| Encryption | Use TLS 1.2/1.3 and AES-256 protection |
What the foreclosure audit trail records
A complete audit trail connects the approved foreclosure document to signer identity, timestamps, document integrity, and retained evidence.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Track activity:
Export evidence:
Security controls for foreclosure records
Data encryption:
Security certification:
Information security:
Signature compliance:
Sensitive records:
Transport security:
Platform requirements for foreclosure work
Foreclosure Form workflows can be prepared through supported browsers on Windows or macOS, with signNow mobile access available for iOS and Android devices. Use TLS-protected connections when handling notice details and supporting property records.
Browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile systems iOS and Android mobile apps
Organizations should manage access through approved devices, role-based permissions, and documented retention policies. Before relying on electronic delivery, confirm whether the applicable state foreclosure process permits it, because primary-residence foreclosure notices may fall outside ESIGN and require prescribed service methods.
Best practices for foreclosure forms
Accuracy, legally appropriate service, and complete records matter more than speed when preparing a Foreclosure Form for a U.S. property matter.
Verify property and borrower details
Use independent legal review
Check the service method
Preserve the complete record
Foreclosure-specific compliance risks
Service defect
Deadline error
Proof gap
ESIGN exclusion
Legal standing and document limits
Electronic records may support business evidence when intent, consent, attribution, and reproducible retention are shown under ESIGN and UETA. However, notices of foreclosure for a primary residence are excluded from ESIGN, so state law may require paper service or another legally prescribed method.

Foreclosure Form troubleshooting
The key troubleshooting question is whether the platform workflow is legally permitted for this foreclosure notice, not merely whether the document can be signed electronically.
signNow can upload a foreclosure document, detect fillable fields, assign recipients, and preserve an audit trail. Those platform features do not determine whether electronic service is lawful. For a primary-residence foreclosure notice, verify the applicable state service rule before using email or an electronic signing workflow.
A signNow audit trail can record signer actions, timestamps, IP information, and document history. Under ESIGN and UETA, those records can support attribution and retention evidence, but the foreclosure-notice exception and state service rules still control whether the notice itself may be electronic.
Consumer-facing electronic records require an ESIGN disclosure explaining the right to paper records, electronic access, and withdrawal procedures under 15 U.S.C. §7001(c). Obtain the required consent before relying on electronic records, while separately checking foreclosure-specific service requirements.
Business is signNow’s $8/user/month plan when billed annually and includes templates and audit trails. Business Premium is $15/user/month annually and adds bulk send. Select the plan based on workflow volume, but confirm legal service requirements outside the platform.
signNow protects data in transit with TLS 1.2/1.3 and at rest with AES-256. Its security credentials include SOC 2 Type II and ISO 27001. Apply role-based access and an approved retention policy to foreclosure records containing borrower information.
If a foreclosure document requires notarization or a prescribed paper delivery method, signNow cannot replace that legal step. Use the platform for preparation, internal review, or record organization only when the governing state law permits those electronic actions.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.