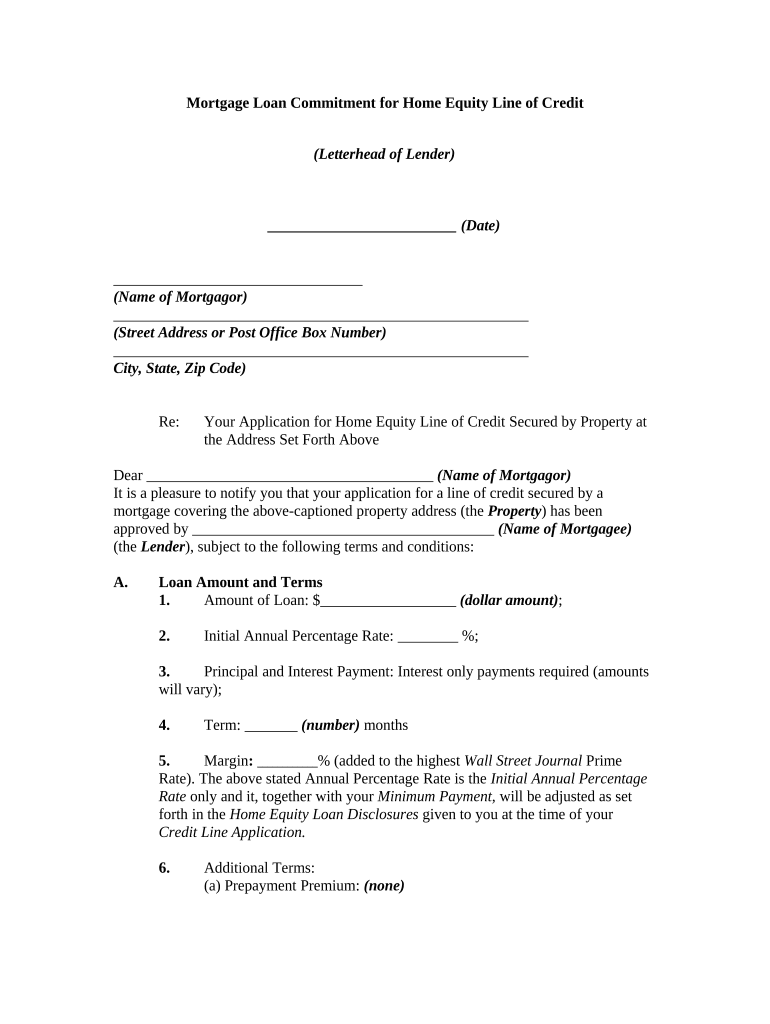
Mortgage Loan Commitment For Home Equity Line Of Credit Form
Use a Mortgage Loan Commitment For Home Equity Line Of Credit template to make your document workflow more streamlined.
What this home equity commitment does
A Mortgage Loan Commitment For Home Equity Line Of Credit Form records a lender’s commitment to establish or extend a home equity line of credit under stated terms. It identifies the borrower, property, approved credit amount, interest or repayment provisions, conditions, expiration information, and required signatures. The lender uses the completed form to document the proposed transaction before closing or funding. With signNow, the lender uploads the approved document, reviews detected fields, assigns each field to the correct participant, sends it for electronic signature, and retains the completed record with its audit trail.
Who benefits from this commitment workflow
Mortgage brokers, credit unions, and enterprise lenders use this form to coordinate borrower signatures, approvals, and auditable home equity line documentation.
Independent mortgage brokers can prepare borrower-specific home equity line commitments, collect signatures remotely, and preserve the signed package without arranging repeated office visits. Regional credit unions can route commitments between loan officers, borrowers, and authorized reviewers while maintaining a consistent audit trail for each home equity line. Enterprise lenders can standardize high-volume commitment workflows with templates, delegated sending, and controlled access across branches, underwriting teams, and closing operations.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features that support home equity commitments
signNow organizes the commitment from field preparation through borrower signing, audit evidence, and record handling for mortgage operations.
Structured fields
Convert the Mortgage Loan Commitment into a structured signable document so loan teams can collect required borrower and lender approvals without manual paper routing.
Signer routing
Send the commitment to each participant in sequence, helping borrowers, lenders, and authorized reviewers sign the correct document in the required order.
Audit trail
Keep the commitment, completion certificate, timestamps, and action history together so lending teams can retrieve evidence when reviewing a completed home equity line file.
Mobile signing
Let borrowers review and sign from supported mobile devices, reducing dependence on branch appointments while keeping the same commitment document in the workflow.
Reusable templates
Apply templates and delegated sending to repeat approved commitment workflows across loan officers, branches, and underwriting groups without recreating fields each time.
Workflow integrations
Connect completed commitments with Salesforce, NetSuite, Google Drive, Box, or Microsoft 365 to reduce duplicate entry and organize signed loan records.
How the commitment workflow works
The signNow workflow turns the lender’s approved commitment into a controlled electronic signing process without changing the transaction’s stated credit terms.
Upload: Upload the lender-approved Mortgage Loan Commitment PDF. Review: SignNow detects fields and lets you verify placement. Route: Assign borrower and lender roles before sending. Complete: Collect signatures and preserve the completed audit trail.
Complete the commitment in four steps
Prepare the Mortgage Loan Commitment for Home Equity Line of Credit in signNow, verify every party’s fields, then send and monitor the signature workflow.
Upload document:
Upload the lender-approved commitment PDF to signNow. Check fields:
Review detected fields and add missing borrower, lender, date, and signature fields. Assign signers:
Assign every field to the correct borrower, lender, or reviewer. Track signing:
Send the commitment and monitor completion from the document workspace.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Choose a signing method for this commitment
- Use the web app when loan officers prepare the commitment, place signer fields, and send the completed document from a desktop workflow.
- Use the mobile app when borrowers or lending staff need to review and sign the commitment from an iOS or Android device.
- Use kiosk mode for branch or closing-room signing when multiple participants complete the Mortgage Loan Commitment together on one controlled device.
- Use a shareable signing link when a lender needs to distribute the same commitment process through a secure, reusable recipient link.
Recommended commitment workflow setup
Configure the Mortgage Loan Commitment workflow around verified signer identity, electronic intent, audit evidence, controlled access, and the lender’s applicable retention policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with intent evidence |
| Audit trail | Enable completion certificate and action history |
| Document retention | Follow lender policy and state law |
| Encryption | TLS 1.2/1.3 and AES-256 protection |



Platform requirements for signing
Use signNow with Chrome, Firefox, Safari, or Edge on Windows 10 or macOS. Borrowers can also use signNow mobile apps on iOS or Android to review and sign the Mortgage Loan Commitment.
Browsers Chrome, Firefox, Safari, Edge Operating systems Windows 10, macOS, iOS, Android Access options Desktop browsers and signNow mobile apps
Lenders should manage access through approved devices and organizational identity controls. Enterprise deployments may also connect API workflows, SSO provisioning, and managed storage, while legal teams should configure retention and access policies for borrower records under applicable state and federal requirements.
Security controls for commitment records
Transport encryption:
Stored encryption:
Security certification:
Information security:
Electronic signatures:
Protected health data:
Process the commitment from draft to archive
The processing sequence follows document preparation, delivery, signer review, and preservation of the completed Mortgage Loan Commitment and its audit evidence.
Prepare the document
Deliver to signers
Collect signatures
Archive completion
Privacy and disclosure pitfalls to avoid
Borrower income, property, credit-limit, or expiration fields may be exposed if the commitment is sent to an unintended recipient. A lender may lack evidence that the borrower received electronic-record disclosures and consented to sign the commitment electronically. Overbroad branch permissions can expose borrower financial details or allow unauthorized edits to a commitment template. Incomplete signer authentication can make it harder to attribute the commitment signature to the intended borrower during a later dispute.
Best practices for commitment processing
Accurate fields, controlled signer roles, complete evidence, and restricted access help lenders process this home equity commitment consistently.
Verify every commitment field before sending
Assign borrower and lender roles carefully
Preserve the signed record and audit evidence
Restrict access to borrower information
Risks from incomplete commitment records
Identity error
Consent gap
Document dispute
Proof deficiency
Legal standing of the commitment
For U.S. transactions, an electronic Mortgage Loan Commitment can carry legal significance when the parties demonstrate intent, consent, attribution, and reliable record retention under ESIGN, 15 U.S.C. chapter 96, and applicable state law such as UETA or New York ESRA. Electronic-signature laws do not replace state requirements for excluded records, including wills, certain court filings, and family-law decrees.

Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting commitment signing issues
Use these answers to resolve plan, authentication, consent, browser, and compliance questions before the home equity commitment is finalized.
Business includes legally binding eSignatures, templates, audit trails, and mobile apps at $8/user/month when billed annually. Its annual allowance is 100 signature invites per user; additional invites may incur overage fees.
Business Premium adds bulk send and kiosk mode at $15/user/month when billed annually. That plan may fit lenders sending repeated commitment packages or signing with borrowers at a branch or closing desk.
signNow can capture email-based signing and optional SMS OTP authentication, but the lender remains responsible for confirming identity requirements, electronic consent, and any state-law closing or notarization requirements.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record retention are established. Consumer-facing transactions also require the electronic-record disclosure requirements in 15 U.S.C. §7001(c).
For protected health information, signNow identifies HIPAA compliance as requiring a business associate agreement. A mortgage commitment should not include PHI unless the lender has a valid business reason and appropriate controls.
If a signer cannot open the document, verify the email address, resend the invitation, or provide a signNow signing link. Confirm browser access through Chrome, Firefox, Safari, or Edge before changing the commitment.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.