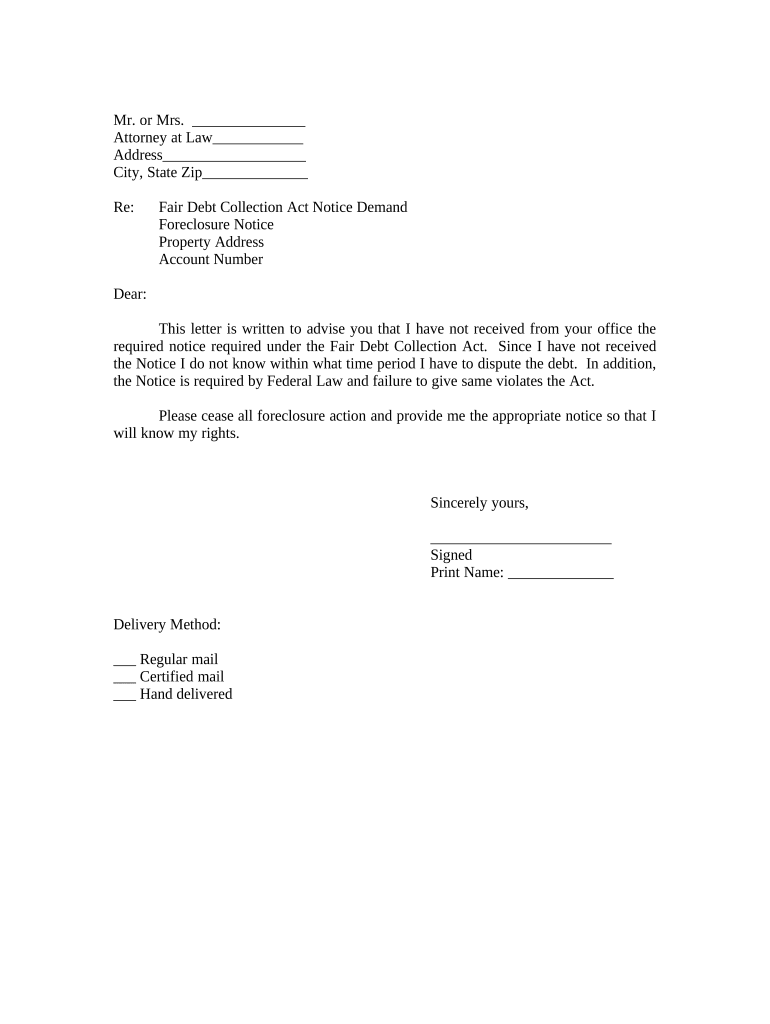
Letter Foreclosure Notice Form
Use a Letter Foreclosure Notice template to make your document workflow more streamlined.
What a foreclosure notice form does
A Letter Foreclosure Notice Form records a lender or servicer’s written notice about a property loan that may proceed toward foreclosure. It generally identifies the borrower, property, loan account, payment or default information, response instructions, and applicable contact details. The sender must verify state notice and delivery rules because foreclosure notices affecting a primary residence are excluded from the federal ESIGN Act’s electronic-record provisions. Where electronic execution is legally permitted, signNow can upload the notice, detect fillable fields, route assigned signatures, capture timestamps and actions, and preserve the completed record with its audit trail.
Who benefits from this foreclosure notice workflow
Different legal and servicing teams use structured foreclosure notices to coordinate review, delivery, signatures, and retention while applying state-specific requirements.
Solo foreclosure attorneys can prepare borrower-specific notices, collect acknowledgments, and preserve a complete signing record without exchanging multiple paper copies. A controlled template helps maintain consistent property, loan, cure-period, and contact information across matters while counsel verifies state-specific requirements before delivery. Mortgage servicing enterprises can route notices through defined teams, monitor signer completion, and connect records to existing systems. Administrators can manage access while authorized staff handle document preparation, delivery evidence, and archival for high-volume foreclosure workflows involving multiple properties and jurisdictions. Real-estate law departments can use structured templates for internal review, borrower communications, and supporting acknowledgments. The workflow separates drafting from sending, records each signing event, and helps preserve the notice alongside loan documents, subject to state law and federal electronic-record exceptions.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Complete a foreclosure notice form
Prepare the notice carefully, confirm state requirements, then route the document for appropriate signatures and records management.
Review details:
Confirm the notice identifies the property, borrower, loan, and required response. Upload form:
Upload the completed notice and let signNow detect available fillable fields. Add fields:
Add required signature, date, and acknowledgment fields for each signer. Send notice:
Send the notice through an approved method and retain delivery evidence. Archive record:
Store the signed record with its audit trail and supporting documents.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Choose a signing method for the notice
- Use the web app when counsel or servicing staff prepare the notice, review detected fields, assign signers, and track completion from a desktop workspace.
- Use the iOS or Android app when authorized staff need to review or sign the notice during field visits, office handoffs, or travel.
- Use kiosk mode for supervised, in-person signing at a controlled office location when the workflow and applicable state law permit electronic execution.
- Use a shareable signing link when the intended signer should open the assigned notice from a controlled message without receiving a separate account invitation.
Recommended foreclosure notice setup
Configure the notice workflow around signer identity, execution evidence, access controls, and the retention rule governing the underlying foreclosure record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with recorded intent |
| Audit trail | Enabled with completion certificate |
| Document retention | Retain under state servicing policy |
| Encryption | TLS 1.2/1.3 and AES-256 |
Retention periods for related records
A foreclosure notice does not have one universal federal retention period. Match the record to its governing rule and preserve longer when state law or a litigation hold applies.
Three years: tax records
Six years: HIPAA records
Six years: broker records
Seven years: SOX records
Thirty years: exposure records
Legal standing and document limits
An electronic foreclosure notice may be admissible when applicable law permits it and the record shows intent, consent, attribution, integrity, and reliable reproduction under ESIGN, 15 U.S.C. chapter 96, or UETA. ESIGN excludes notices of foreclosure affecting a primary residence, along with wills, certain family-law decrees, and court filings; state law controls the required alternative process.

Challenges when preparing a foreclosure notice
Using electronic delivery for a primary-residence foreclosure notice can conflict with ESIGN’s statutory exception and applicable state service requirements. Missing property, loan, cure-period, or contact information can make the notice unclear and require correction before service. A signed PDF without its audit trail, delivery evidence, and retention context may weaken the record’s evidentiary value during a dispute. Sharing a borrower-facing link without access controls can expose personal, property, payment, or loan information to an unintended recipient.



Foreclosure notice troubleshooting
Resolve field, authentication, plan, legal-scope, and retention questions before sending a foreclosure notice to a borrower or other signer.
If signNow does not detect fields, upload a clearer PDF or add signature, date, and acknowledgment fields manually. Confirm the notice’s property, borrower, loan, cure-period, and contact information before sending. Detection does not determine whether state law permits electronic delivery or execution.
Business includes legally binding eSignatures, templates, audit trails, and mobile apps at $8 per user per month when billed annually. Business Premium is $15 per user per month annually and adds bulk send and kiosk mode. Actual plan selection should reflect the notice volume and workflow.
A signNow audit trail can document signer actions, timestamps, and document history, but it cannot override ESIGN exceptions or state foreclosure-notice rules. For a primary-residence foreclosure notice, confirm whether paper service, statutory language, notarization, or another method is required.
Use SMS OTP or another configured authentication method when stronger signer attribution is needed. For consumer-facing electronic records, ESIGN requires disclosure of the right to paper, access to electronic records, and procedures for withdrawing consent under 15 U.S.C. §7001(c).
Do not delete the signed notice merely because the signNow transaction is complete. Export the audit trail and completion record, then apply the governing state servicing, litigation-hold, or federal retention rule to the notice and supporting communications.
signNow is HIPAA compliant when a BAA is required, but HIPAA’s six-year rule under 45 CFR §164.530(j) applies only when the retained record is subject to HIPAA. A foreclosure notice without PHI needs the retention rule governing its actual record category.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.