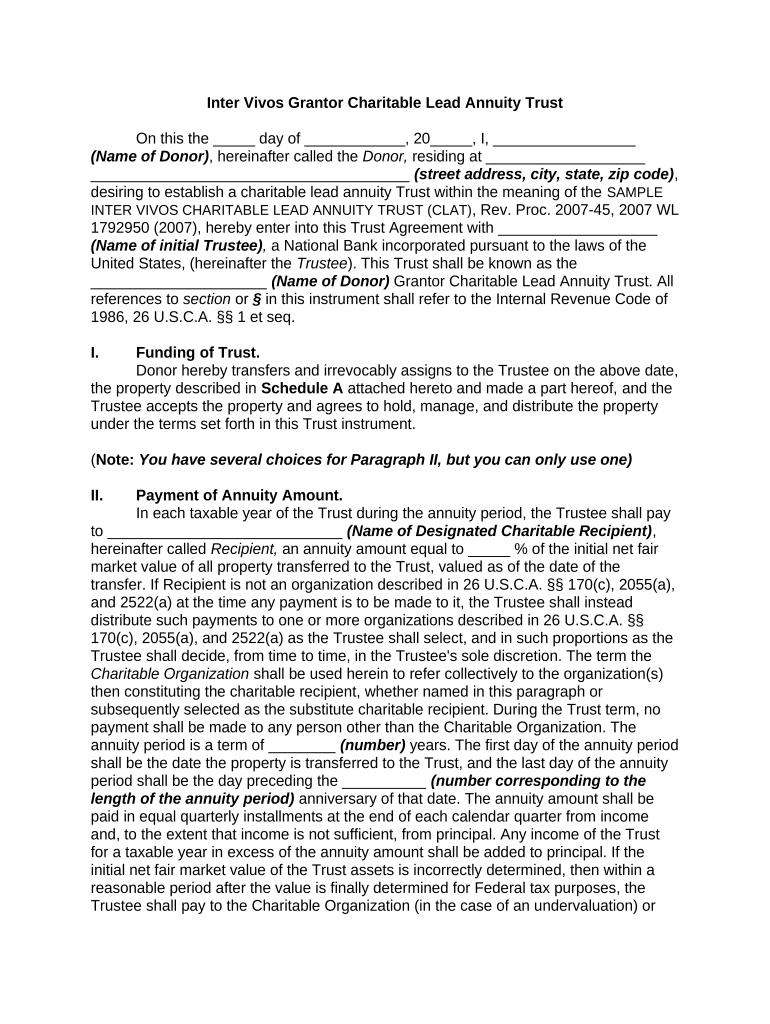
Charitable Lead Trust Form
Use a Charitable Lead Trust template to make your document workflow more streamlined.
What Charitable Lead Trust Form does
Charitable Lead Trust Form records the terms and approvals for a charitable lead trust, where charitable interests receive defined benefits before remaining trust property passes to designated beneficiaries. The document typically identifies the grantor, trustee, charitable recipient, beneficiaries, funding property, payment terms, duration, and execution requirements. It is not a universal federal filing form; its enforceability depends on the trust instrument, applicable state law, and tax planning. Electronic signing may be recognized under ESIGN and UETA when intent, consent, attribution, and record retention are established, subject to statutory exceptions.
Who uses charitable trust forms
Legal services
Estate-planning attorneys use Charitable Lead Trust Form for trust instruments, grantor acknowledgments, trustee approvals, and charitable-recipient documentation. Role-based routing helps separate drafting, review, signature, and archival responsibilities while preserving an audit trail for the executed record.
Nonprofit and fiduciary teams
Private foundations and fiduciary departments use the form for donor-facing approvals, charitable distribution records, and trustee correspondence. Access controls, signer authentication, and downloadable completion records help protect personal and charitable information during administration.
Who benefits from trust form workflows
Charitable Lead Trust Form workflows help legal, nonprofit, and fiduciary teams coordinate signatures, records, and permissions around charitable trust administration.
Solo estate-planning attorneys can prepare charitable lead trust instruments, collect grantor signatures, and preserve completed records without coordinating paper exchanges across offices. Private foundations and nonprofit administrators can route trust-related acknowledgments to authorized signers while separating donor information from operational access permissions. Enterprise fiduciary and tax departments can standardize trust-document templates, delegate sending, and maintain audit evidence across multiple charitable planning matters.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the trust form workflow works
The signNow workflow follows the document from field preparation through authorized signatures and auditable storage.
Upload document: Upload the trust document and let signNow detect fillable fields. Check fields: Review grantor, trustee, beneficiary, and charitable-recipient fields. Send requests: Send signature requests to the authorized parties in sequence. Archive record: Store the executed trust record with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the signNow audit trail records
The audit trail documents signer identity controls, event timing, document integrity, and retrieval actions without replacing the trust instrument itself.
Signer authentication:
Timestamp capture:
Document sealing:
Audit export:
Evidence linkage:
History review:
Recommended trust form setup
Use signer verification, role-based access, encryption, and documented retention rules for charitable trust records.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Intent-based electronic signature |
| Audit trail and retention | Export audit trail and apply IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 |
| User provisioning | Role-based access with delegated sending |



Retention periods for trust records
Keep signed trust records according to the underlying tax, healthcare, or audit obligation, and document the rule applied.
Three years from tax filing
Six years from tax filing
Indefinitely for fraud or nonfiling
Six years from creation or effective date
Seven years for audit records
Best practices for trust records
Accurate party data, controlled signing, complete audit evidence, and rule-based retention reduce avoidable problems with charitable trust documentation.
Review every trust party and provision
Match authentication to signer risk
Export the complete evidence package
Limit access to authorized administrators
Legal standing for trust transactions
A signed charitable trust record can provide evidence when the signer shows intent, consents to electronic records, and the record remains attributable and reproducible under ESIGN, 15 U.S.C. chapter 96, and applicable UETA law. ESIGN exceptions include wills, testamentary trusts, court orders, and family-law decrees.

State rules and document limits
State execution rules
Wills and codicils
Court orders
Real-estate deeds
Privacy pitfalls in trust documents
Grantor addresses, beneficiary details, and charitable recipient information can remain visible to unauthorized recipients when access permissions are too broad. A missing electronic-consent disclosure can weaken evidence that a consumer agreed to receive or sign trust-related records electronically. Shared links without signer verification can make it difficult to attribute a completed signature to the intended grantor. Unrestricted downloads may expose signed trust instruments, tax identifiers, or charitable distribution details beyond the required administrative group.
Trust form troubleshooting questions
Resolve field, signer-authentication, consent, plan, and retention questions before distributing a completed Charitable Lead Trust Form.
Upload the trust PDF again after confirming it is not password-protected or corrupted. signNow can then detect fillable fields for grantor, trustee, and charitable-recipient information.
Use signNow SMS OTP or another available authentication control to strengthen signer attribution. The audit trail records signing actions, timestamps, and related event details for the executed document.
Business includes legally binding eSignatures, templates, mobile apps, and audit trails. Business Premium adds bulk send, while Enterprise adds advanced signer authentication and conditional fields.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record reproducibility are established. State law and document-specific exceptions still require review before electronic execution.
Consumer-facing records require an ESIGN disclosure explaining paper-record rights, electronic access, and consent withdrawal procedures under 15 U.S.C. §7001(c). Capture that consent before requesting the signature.
Export the completed document and audit trail from signNow, then apply the underlying retention rule. IRC §6501(a) generally uses three years, with longer periods for significant understatement, fraud, or nonfiling.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.