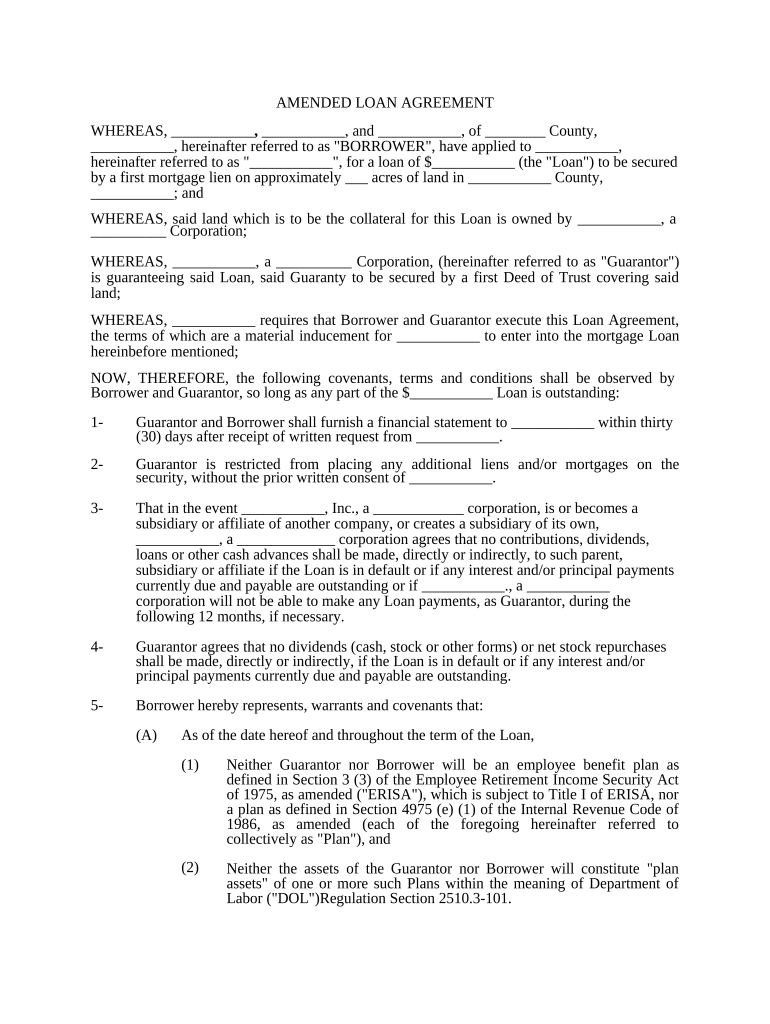
Amended Loan Agreement Form
Use a Amended Loan Agreement template to make your document workflow more streamlined.
What an amended loan agreement does
An Amended Loan Agreement Form records agreed changes to an existing loan rather than replacing the entire lending history. It may revise the interest rate, payment schedule, maturity date, principal balance, collateral, borrower details, or other negotiated terms. The parties should identify the original agreement, state each amendment precisely, confirm signing authority, and preserve the executed document with supporting records. In the United States, electronic execution may be recognized under ESIGN and applicable state law, subject to exclusions and transaction-specific requirements.
Businesses that use loan amendments
Amended loan agreements help organizations document negotiated changes without recreating the entire lending relationship or losing the original terms.
A regional credit union can document borrower payment changes and route the amendment through authorized lending staff without exchanging paper copies. A commercial finance practice can coordinate lender, borrower, and counsel signatures while preserving the revised terms beside the original loan agreement. An enterprise treasury department can standardize amendments across subsidiaries using shared templates, role-based access, and completion certificates for internal records.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses amended loan agreements
Lenders
Lenders use amended agreements to document revised rates, payment schedules, maturity dates, collateral terms, or borrower information before releasing the executed record.
Borrowers and counsel
Borrowers and business counsel review changed loan terms, confirm authority, and retain the signed amendment with the original agreement and related notices.
How to complete the amended agreement
The signNow workflow converts a revised loan agreement into a traceable document for review, signature, and record retention.
Upload agreement: Upload the amended agreement and confirm its parties, revised terms, and signature fields. Check fields: Review detected fields and add missing initials, dates, or approval fields. Send for signing: Send the completed amendment to borrowers, lenders, or authorized representatives. Archive record: Store the signed amendment with its completion certificate and audit trail.
How the loan amendment audit trail works
The audit trail records who handled the amended agreement, what happened, and when, creating evidence separate from the document’s visible signature.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Record events:
Export trail:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended amended agreement setup
Configure the amendment workflow around signer identity, evidence preservation, controlled access, and the retention policy required for the lender’s records.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Completion certificate with event history |
| Retention and encryption | Six-year policy with AES-256 storage |
| User provisioning | Role-based access through managed teams |
Security for amended loan records
Stored data:
Data in transit:
Control assurance:
Security management:
U.S. eSignature:
Protected health data:
Mobile options for loan amendments
Signers can review and complete an Amended Loan Agreement Form using signNow on iOS 15 or later or Android 10 or later. The mobile applications support document review, field completion, and camera-based capture of paper pages before sending the amendment for signature.
iPhone app iOS 15 or later signNow mobile application Android app Android 10 or later signNow application Camera capture Camera capture supports agreement page uploads
Offline work can help prepare documents when connectivity is limited, but the sender should confirm synchronization before distributing the amendment. Organizations using managed devices can combine mobile access with signNow API connections, SSO provisioning, and configured signer authentication for controlled lending workflows.



Legal standing of an amended loan agreement
An amended loan agreement can be admissible when the parties show intent, consent to electronic records, signer attribution, and reliable retention under ESIGN, 15 U.S.C. §§7001 and 7006, and applicable UETA law. Electronic signing does not cover wills, codicils, testamentary trusts, court orders, or family-law decrees.

Risks of an incomplete loan amendment
Unproven consent
Version conflict
Signer authority
Evidence gap
Privacy and disclosure pitfalls
Borrower names, revised balances, interest rates, payment dates, or maturity terms may be exposed when access permissions exceed the lending team’s needs. A missing electronic-record consent disclosure can complicate consumer-facing delivery when the borrower must receive and retain the amendment electronically. Sending an outdated amendment creates conflicting loan records, especially when multiple parties circulate revised payment schedules or collateral language. Unassigned initials, dates, or guarantor fields can leave the executed amendment incomplete and weaken evidence of agreement to specific changes.
Record-keeping practices for loan amendments
A signed amendment is most useful when its revised terms, execution evidence, and retention treatment remain connected throughout the loan record’s lifecycle.
Apply the applicable retention period
Export the completion evidence
Archive the signed agreement securely
Reconcile revised loan terms
Questions about amended loan agreements
These answers address signing, consent, plan limits, evidence, and legal treatment for an Amended Loan Agreement Form workflow.
Business includes legally binding eSignatures, templates, audit trails, mobile apps, ISO 27001, SOC 2, and GDPR support. Business Premium adds bulk send at $15 per user per month when billed annually.
A signature invite may be unavailable after the annual plan allowance is reached. Subscription plans include 100 signature invites per user per year; overage pricing depends on the plan, while Site License uses $1.50 per signature invite.
For consumer-facing electronic records, provide the ESIGN disclosure explaining the right to paper records, electronic access, and withdrawal procedures under 15 U.S.C. §7001(c). Confirm the borrower can access and retain the amendment before signing.
A completion certificate and audit trail document signing events, timestamps, and participant activity. Export both with the executed amendment, then apply the lender’s retention policy and any applicable state or federal requirements.
HIPAA compliance applies when the workflow handles protected health information and requires a BAA. A loan amendment should not be treated as a HIPAA record merely because a healthcare business signs it.
ESIGN covers interstate and foreign commerce, while UETA generally governs intrastate transactions in adopting jurisdictions. New York uses ESRA instead of UETA. Confirm exclusions, consent, intent, attribution, and record reproduction before relying on electronic execution.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.