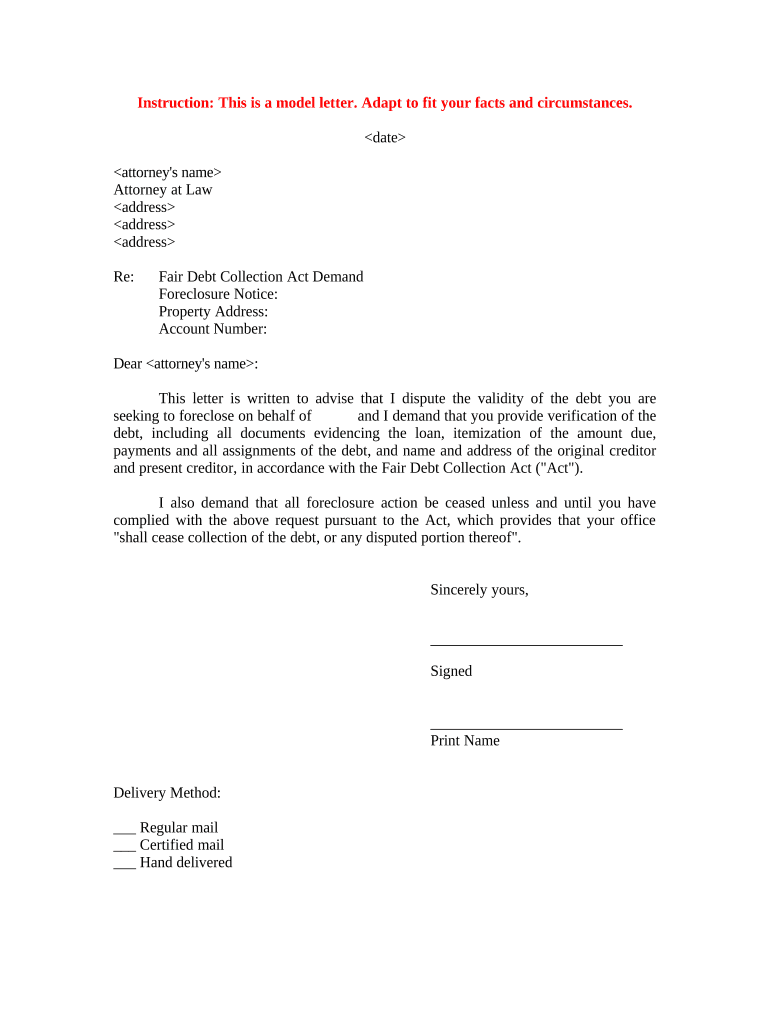
Foreclosure Letter Form
Use a Foreclosure Letter Sample template to make your document workflow more streamlined.
What a foreclosure letter form does
A Foreclosure Letter Form records a lender or servicer’s written communication about a foreclosure matter for a specified property and recipient. The preparer enters the property, borrower, notice, and contact details, then routes the document for review, delivery, or signature when legally permitted. signNow can accept the uploaded PDF, detect fillable fields, send it to designated participants, and preserve an Audit Trail. U.S. law requires special care: ESIGN excludes notices of foreclosure involving a primary residence, so state law and document purpose must be checked before electronic execution.
Who benefits from foreclosure letter workflows
Foreclosure counsel, mortgage servicers, and lender legal departments use this form to coordinate property-specific notices and preserve supporting records.
Solo foreclosure attorneys can prepare property-specific letters, route internal approvals, and preserve the signed record without combining borrower information across unrelated files. Regional mortgage servicers can standardize letter fields, assign authorized reviewers, and retain delivery evidence for each property while checking state-specific foreclosure notice requirements. Enterprise lenders and legal departments can connect foreclosure correspondence to controlled repositories, apply role-based access, and export audit evidence when a dispute or regulatory review requires it.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the foreclosure letter workflow works
signNow turns the prepared foreclosure letter into a controlled workflow, while legal staff confirm whether electronic signing is permitted for the specific notice.
Upload letter: Upload the foreclosure letter PDF to signNow. Check fields: Review detected fields and add missing property or signer fields. Route document: Send the prepared letter to authorized signers or reviewers. Preserve record: Store the completed record with its audit evidence.
Recommended foreclosure letter setup
Configure identity, evidence, storage, and access controls around the foreclosure file’s governing state and federal requirements.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Export certificate and action history |
| Document retention | Apply applicable state retention rule |
| Encryption | TLS 1.2/1.3 and AES-256 |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the foreclosure audit trail records
The audit trail documents who interacted with the foreclosure letter, when each action occurred, and how the completed record can be retrieved.
Authenticate signer:
Capture timestamp:
Record document hash:
Seal audit history:
Log activity:
Export evidence:
Security controls for foreclosure records
Transport and storage:
Independent controls:
Information security:
Protected information:
Electronic records:
Signer verification:
Privacy pitfalls in foreclosure letters
Borrower names, property addresses, loan details, and financial information can be exposed when access permissions are broader than the foreclosure team requires. A missing consumer electronic-record disclosure can weaken consent evidence when the recipient is a consumer and electronic delivery is being considered. Using a signing link without verifying the intended recipient can make attribution difficult when multiple borrowers, agents, or counsel share contact details. Combining a foreclosure notice with unrelated medical or financial records can create unnecessary privacy exposure and complicate retention decisions.
Retention practices for foreclosure letters
Preserve the signed letter, delivery evidence, and audit history together, then apply the rule governing the underlying foreclosure record.
Apply the underlying retention rule
Export the complete audit evidence
Archive the original securely
Maintain a traceable file index
Retention periods for foreclosure records
No single federal period governs every foreclosure letter; select the period tied to the record’s underlying tax, health, securities, or audit obligation.
Three years from filing
Six years for understatement
Six years for HIPAA records
Six years for broker records
Seven years for audit records
Risks from improper execution
Primary-residence notice
Missing audit trail
Weak attribution
Invalid execution
Legal standing and document limits
A signed business record may be admissible when the signer intended to sign, consented to electronic records, can be identified, and the record can be retained and reproduced under ESIGN, 15 U.S.C. chapter 96, and applicable UETA law. However, ESIGN excludes notices of foreclosure involving a primary residence, wills, codicils, testamentary trusts, and court orders. Confirm the document’s legal category and state requirements before relying on electronic execution.

Foreclosure Letter Form troubleshooting
Resolve the specific legal, plan, authentication, and retention issue before treating a foreclosure letter as complete.
signNow Business is listed at $8 per user per month with annual billing and includes audit trails. If the letter concerns a primary-residence foreclosure notice, electronic-signature availability does not override the ESIGN exclusion; obtain legal guidance before sending.
Business Premium includes bulk send, while Business does not include that plan feature. Use individual routing for a single property letter, or confirm the plan before distributing multiple property-specific documents.
signNow supports ESIGN and UETA compliance, but compliance does not decide whether a particular foreclosure notice is excluded. ESIGN excludes notices involving foreclosure of a primary residence, so review the notice and applicable state law.
Use signer authentication, such as email verification with SMS OTP, and preserve the certificate of completion and Audit Trail. Attribution, intent, consent, and reproducible records support evidence; they do not cure an excluded document type.
HIPAA applies when the foreclosure file contains protected health information, not merely because signNow supports HIPAA compliance. A business associate agreement is required for HIPAA-covered use, and access should remain limited to authorized personnel.
Export the completed PDF, certificate of completion, and Audit Trail, then store them together under the governing retention policy. Do not rely on an account view alone when the organization requires an independently preserved record.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.