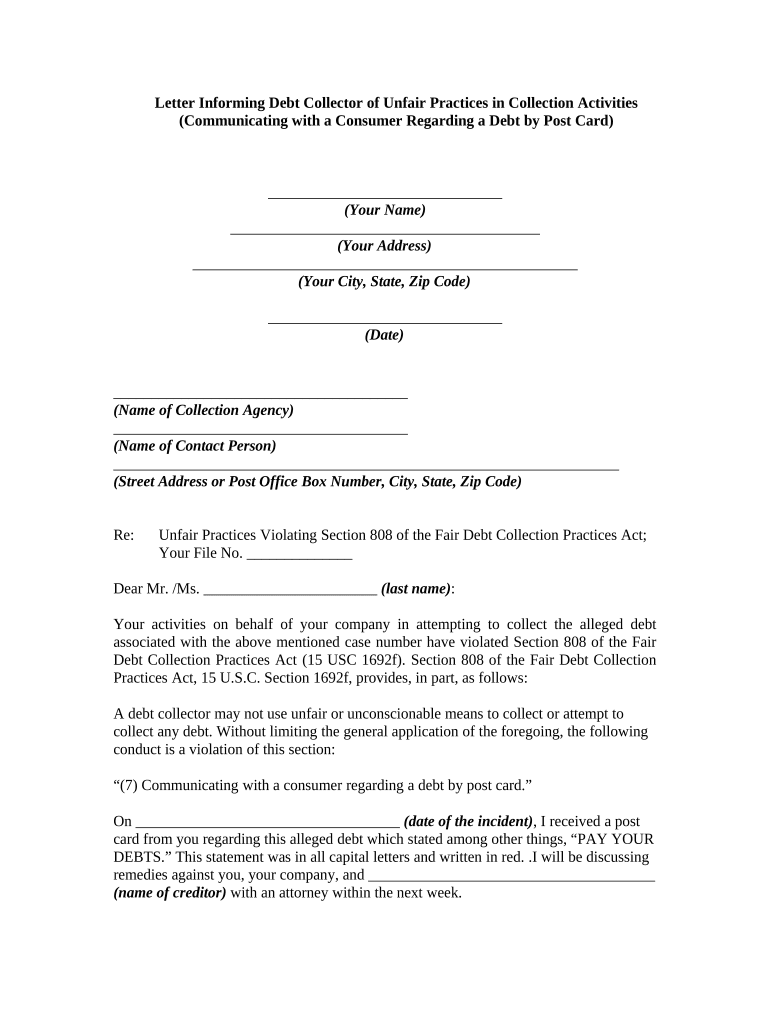
Letter Informing Debt Collector Of Unfair Practices In Collection Activities Communicating With A Consumer Regarding A Debt By P
Use a Letter Informing Debt Collector Of Unfair Practices In Collection Activities Communicating With A Consumer Regarding A Debt By P template to make your document workflow more streamlined.
What this debt-collection letter does
This letter is a consumer’s written notice to a debt collector describing allegedly unfair collection practices and requesting a defined response or communication change. It should identify the collector, reference the debt without unnecessary personal data, explain the conduct with dates and examples, and state the requested remedy. The letter itself does not establish that a violation occurred, cancel a debt, or replace a court filing. When signed electronically, ESIGN and applicable UETA rules can support the record if intent, consent, attribution, and reproducibility are documented.
How this debt letter workflow works
The workflow moves the consumer communication from document preparation through signature and auditable record storage.
Upload letter: Upload the debt letter into signNow. Check fields: Review detected fields and add missing ones. Assign roles: Assign the consumer and sender signing roles. Complete record: Send, sign, and preserve the completed record.
Steps for completing this debt letter
Prepare the letter from verified account information, describe the conduct clearly, and preserve delivery and signature evidence.
Verify recipient:
Confirm the collector’s legal name, address, and contact channel from reliable records. Describe conduct:
State the debt reference and describe each disputed collection practice precisely. State requested remedy:
Request the specific communication change or other relief sought from the collector. Add evidence:
Attach only documents necessary to support the letter’s factual statements. Review disclosures:
Review consent, signer identity, and delivery details before sending electronically. Store records:
Download the signed letter and audit trail after completion.
Choose a signing method for this letter
- Use the web app to upload the letter, review detected fields, assign the consumer and sender roles, and send the completed document from a desktop workflow.
- Use the mobile app when preparing or reviewing the letter away from the office, including signature requests and status checks on supported mobile devices.
- Use kiosk mode for supervised signing when a consumer is physically present and staff must control the signing session on an organization-managed device.
- Use a shareable signing link when the same letter template must be distributed through an approved channel without manually addressing each invitation.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended settings for this consumer letter
Use controlled identity checks, an auditable signature event, and protected storage when preparing this debt-collection communication.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with optional SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture signer identity, timestamps, IP address, and actions |
| Document retention | Retain signed records under a documented legal hold policy |
| Encryption | Use TLS 1.2 or 1.3 and AES-256 at rest |
What the audit trail records
For this letter, the audit trail connects the consumer’s identity, signing activity, document version, and preserved completion evidence.
Authenticate signer:
Capture timestamps:
Protect document:
Log activity:
Export evidence:
Control retrieval:
Privacy risks when preparing this debt letter
Including a full account number or unnecessary medical detail can expose sensitive personal information in the completed debt-collection letter. Sending the letter before confirming the recipient’s identity may disclose debt information to an unintended person. Consumer consent to electronic records should be documented before relying on electronic delivery or signature under ESIGN. Broad team permissions can let unauthorized users view, alter, or resend a consumer’s signed debt correspondence.
Record-keeping practices for this letter
Preserve the exact consumer communication, signing evidence, and delivery record while applying the retention rule for the underlying dispute.
Limit personal information to necessary details
Preserve the letter and audit trail together
Record electronic-record consent before sending
Set retention from the underlying dispute
Processing stages for this consumer letter
Use a controlled sequence to prepare, deliver, sign, and preserve this debt-collection communication without adding unsupported filing deadlines.
Prepare the letter
Deliver to consumer
Consumer review
Archive completed records
Security controls for signed debt letters
TLS 1.2 and 1.3 in transit:
AES-256 encryption at rest:
SOC 2 Type II certified:
ISO 27001 certified:
GDPR and CCPA compliant:
ESIGN and UETA compliant:
Legal standing of this signed letter
A signed debt-collection letter can provide evidence of the sender’s stated position and the consumer’s intent when attribution, consent, and record reproducibility are established under ESIGN and applicable UETA rules. Electronic-signature laws do not guarantee a legal result, and exclusions such as wills, certain court filings, and family-law decrees remain outside their ordinary scope.

Questions about completing this debt letter
These answers address field detection, consumer consent, delivery, preservation, and the legal limits of electronically signing this specific collection communication.
signNow’s Business plan provides templates, legally binding eSignatures, audit trails, and mobile apps at $8 per user per month when billed annually. Upload this letter, review detected fields, and add any missing signature or date fields before sending.
Use signNow’s electronic-record workflow to document consent before sending this consumer-facing letter. ESIGN, 15 U.S.C. §7001(c), requires disclosure of the paper-record option, electronic access, and withdrawal procedures for covered consumer records.
The Business Premium plan is listed at $15 per user per month annually and includes bulk send. For one individualized debt letter, use a direct invitation rather than bulk distribution to prevent disclosure to the wrong consumer.
If the consumer cannot access the invitation, verify the email address, resend through the controlled signNow workflow, or use an approved signing link. Confirm identity before sharing debt information, and avoid placing sensitive account details in the invitation subject line.
signNow records signing timestamps, signer actions, and audit-trail information. Download the completed PDF and audit trail together, then preserve them under a documented dispute-retention or legal-hold policy rather than deleting them immediately.
Electronic signatures generally receive legal recognition under ESIGN and applicable UETA rules when intent, consent, attribution, and record reproducibility are established. This letter does not become legal advice or guarantee a particular debt-collection outcome through electronic signing.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.