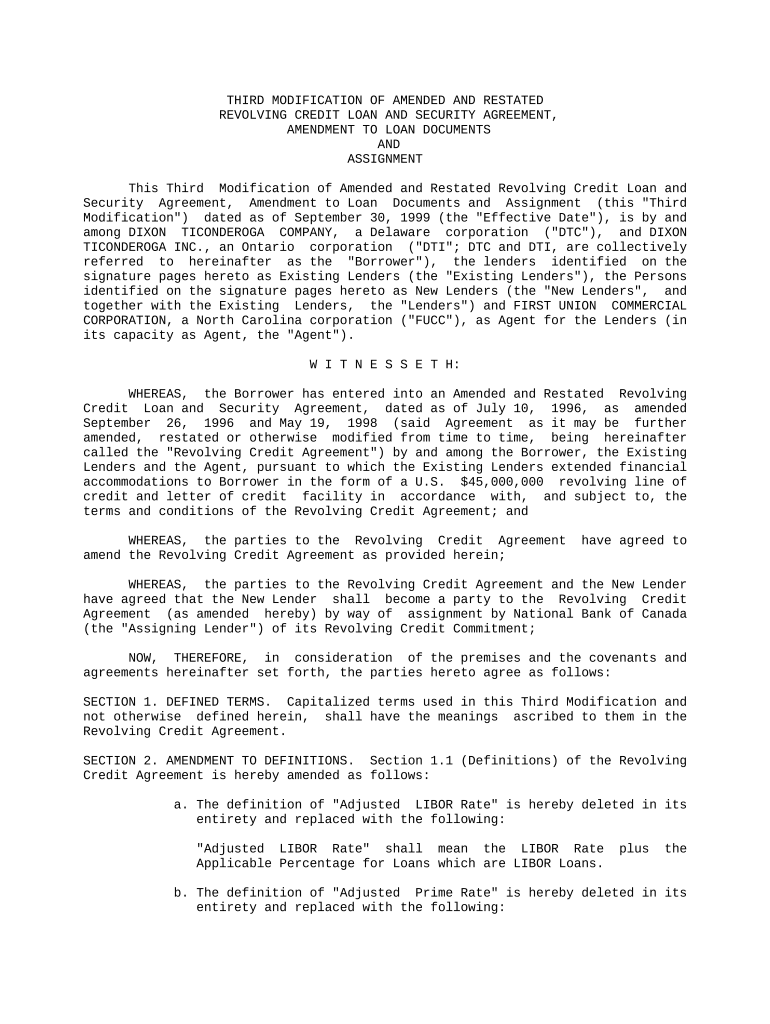
Revolving Loan Agreement Form
Use a Revolving Loan Agreement Template template to make your document workflow more streamlined.
What a revolving loan agreement does
A Revolving Loan Agreement Form records the terms under which a borrower may draw, repay, and redraw funds up to an approved credit limit. It identifies the lender and borrower, states principal and interest provisions, defines requests and repayment, and addresses defaults, representations, notices, and signatures. Because this is a transaction contract rather than a federally standardized filing, the parties must verify the form’s terms, governing law, and any collateral or guaranty requirements. signNow can route the prepared agreement for electronic signatures and preserve the executed record and audit trail.
Who uses this loan agreement
Lenders
Lenders use the form to document approved credit limits, draw requests, interest calculations, repayment obligations, default provisions, notices, and authorized representatives before releasing revolving funds.
Borrowers
Borrowers and guarantors review the facility terms, provide required representations, sign assigned fields, and retain the completed agreement for future draw and repayment reference.
Business types that use loan agreements
Revolving loan agreements serve lenders and borrowers that need documented access to repeat borrowing under defined financial terms.
Solo lenders and small finance practices use revolving loan agreements to document borrower limits, draw procedures, interest terms, and repayment duties without rebuilding the document for every approved facility. Commercial lending teams use reusable templates, delegated sending, and controlled signer routing for borrowers, guarantors, and authorized officers. Larger organizations can connect completed agreements to finance and document systems for review and retention. Corporate treasury and credit departments use the form when affiliated entities need documented access to a revolving facility. Role-based administration helps separate template ownership, transaction preparation, approval, and execution responsibilities.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Key features for revolving loan agreements
A revolving loan agreement needs accurate financial terms, controlled signing, and retrievable evidence. These signNow features address the document’s drafting, execution, and records workflow.
Reusable fields
Reusable fields capture principal, credit limit, draw terms, interest provisions, repayment dates, and signatures consistently across agreements. Standardized templates reduce omissions while preserving space for transaction-specific terms and lender-approved amendments.
Signer routing
Signer routing sends the agreement to borrowers, guarantors, and authorized lender representatives in the intended order. Each participant receives only the actions assigned to them, reducing accidental execution before required approvals are complete.
Audit trails
Audit trails record signer actions, timestamps, and document history for the completed agreement. Maintaining this evidence helps teams demonstrate intent, attribution, and reliable record reproduction under ESIGN and applicable state law.
Mobile signing
Mobile signing lets borrowers and lender personnel review the revolving loan agreement from supported devices. The workflow can reduce printing and scanning while keeping the executed document connected to its completion record.
Conditional fields
Conditional fields can display transaction-specific terms when configured for the selected workflow. This helps separate optional guaranty, collateral, or draw provisions without altering the underlying agreement for every borrower.
Secure storage
Secure storage preserves the signed agreement and completion evidence in one controlled workspace. Retention policies can then be aligned with the lender’s contract, tax, litigation, and state-law obligations.
How a revolving loan agreement works
A revolving loan agreement moves from transaction-specific preparation to assigned signing, execution, and evidence retention.
Prepare terms: Prepare the agreement with borrower, lender, principal, interest, draw, repayment, default, and signature provisions. Add fields: Upload the completed document to signNow and place required signature, initial, date, and acknowledgment fields. Route signers: Assign fields to each borrower, guarantor, and lender representative, then send the agreement in signing order. Store evidence: Collect signatures and retain the executed agreement with its completion certificate and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended agreement workflow setup
Configure the revolving loan agreement workflow around signer identity, execution evidence, controlled access, and the retention period applicable to the underlying record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS two-factor authentication |
| Signature type | Electronic signature with completion certificate |
| Audit trail | Enabled for every borrower and lender action |
| Document retention | Three years from filing under IRC §6501(a) |
| User provisioning | Administrator-controlled roles and shared templates |
What the loan agreement audit trail records
The audit trail connects signer identity, document actions, timestamps, and completion evidence to the executed revolving loan agreement.
Authenticate signer:
Capture timestamps:
Track document history:
Seal completion:
Connect evidence:
Export audit trail:
Security for signed loan agreements
Data at rest:
Data in transit:
Security certification:
Information security:
Electronic signatures:
Signer authentication:



Best practices for completing loan agreements
Accuracy matters because the agreement defines borrowing authority, repayment duties, and evidence of assent. Use this checklist before and after signing.
Reconcile financial terms before sending
Assign execution fields by party
Document consumer electronic consent
Archive the complete execution record
Rollout and retention for loan agreements
Adopt the agreement workflow in defined phases, then retain executed records according to the transaction’s legal and tax requirements.
Account setup:
First agreement:
Team onboarding:
Record retention:
Extended retention:
Execution evidence:
State review:
Policy ownership:
Privacy and disclosure pitfalls
A revolving loan agreement may expose bank account details, taxpayer information, or personal addresses when copies are emailed without controlled access. Missing consent evidence can weaken proof that a borrower agreed to electronic records, especially when consumer-facing disclosures and paper-record rights apply. Overbroad workspace permissions can let unauthorized staff view credit limits, repayment terms, guarantor information, or completed signature records. Sending a draft with sensitive exhibits to the wrong recipient can disclose collateral, financial statements, or borrower identifiers outside the intended transaction.
Platform requirements for loan agreements
Prepare and sign the Revolving Loan Agreement Form in Chrome, Firefox, Safari, or Edge on Windows or macOS. signNow also provides mobile apps for iOS and Android, while encrypted connections use TLS 1.2/1.3 for data in transit.
Desktop browsers Chrome, Firefox, Safari, and Edge on Windows or macOS Mobile apps signNow mobile apps for iOS and Android Connection security TLS 1.2/1.3-secured internet connection required
Organizations should manage signer access through approved devices and administrator-controlled accounts. Finance teams may connect the workflow to NetSuite, Microsoft 365, Google Drive, Box, or other supported systems, while enterprise deployments should review SSO, API, authentication, and retention requirements before production use.
Key performance indicators that demonstrate SignNow's proven track record.
Troubleshooting revolving loan agreements
These answers address field assignment, plan selection, electronic-signature validity, consent, authentication, and evidence retention for this agreement.
The Business plan includes templates and audit trails at $8/user/month when billed annually. Upload the approved agreement, place fields manually or use automatic field detection, and confirm the template contains every required transaction field before sending.
Business Premium is the signNow plan that includes bulk send. It is priced at $15/user/month with annual billing. Use it only when sending substantially similar agreements to multiple borrowers; review each recipient’s credit-specific terms before dispatch.
A signed agreement can be electronically enforceable when intent, consent, attribution, and record retention are established. ESIGN, 15 U.S.C. ch. 96, and applicable UETA provisions support electronic records, but contract and lending requirements still apply.
Consumer-facing electronic records require the ESIGN disclosure under 15 U.S.C. §7001(c), including paper-record rights, electronic-access capability, and withdrawal procedures. Capture that consent before relying on an electronic revolving loan agreement with a consumer.
Enterprise is listed at $30/user/month with annual billing and adds advanced signer authentication, formula fields, conditional fields, payments, and advanced integrations. Select the controls required by the lender’s risk policy rather than assuming every agreement needs Enterprise.
The Business plan includes audit trails, while signNow’s compliance portfolio includes ESIGN and UETA compliance, SOC 2 Type II certification, and ISO 27001 certification. Preserve the completed agreement and audit trail together; platform controls do not replace legal review.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.