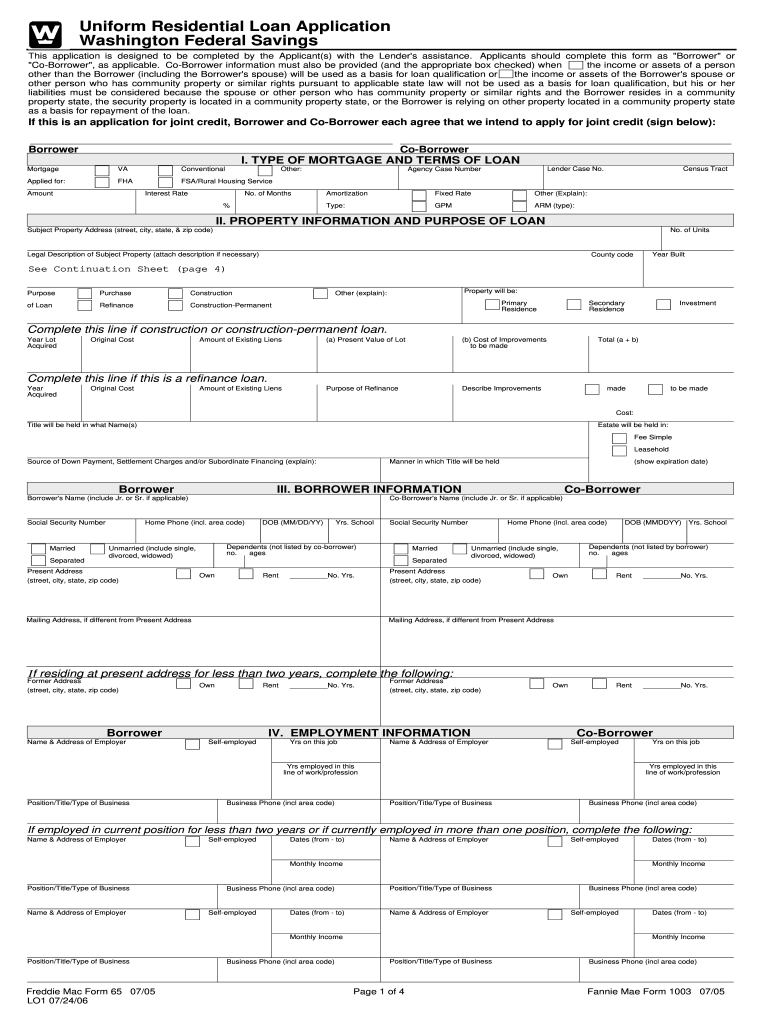
Uniform Residential Loan Application (2005 2026)
Create a custom Uniform Residential Loan Application 2005 that meets your industry’s specifications.
What the Uniform Residential Loan Application does
The Uniform Residential Loan Application (2005 2026) is a mortgage application that organizes a borrower’s identity, income, assets, debts, property details, and requested loan terms for lender review. Borrowers and co-borrowers provide the information, then sign the completed record. With signNow, a lender uploads the application, reviews detected fillable fields, assigns signer roles, sends the document, and retains the completed PDF with its audit trail. Electronic signing may be recognized under ESIGN and applicable state law, subject to lender procedures and transaction requirements.
Who benefits from digital loan applications
Mortgage professionals and lending organizations use signNow to coordinate borrower information, signatures, and records for this application.
Independent mortgage brokers use the application to collect borrower data, co-borrower signatures, and supporting acknowledgments without coordinating repeated office visits. Regional credit unions use standardized application workflows to route borrower and loan-officer signatures, preserve audit evidence, and organize completed records. National mortgage lenders use controlled templates, delegated sending, and role-based access to process high-volume borrower applications across distributed teams.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Features for completing loan applications
signNow organizes the Uniform Residential Loan Application (2005 2026) from upload through signature, while keeping borrower-specific information and completion evidence together.
Field detection
Upload the Uniform Residential Loan Application (2005 2026) and review automatically detected fields before assigning borrower and co-borrower information.
Signer roles
Assign separate roles for borrowers, co-borrowers, loan officers, and other required participants to clarify who completes each application field.
Remote signing
Send the application by email or signing link, helping remote borrowers review and sign without exchanging repeated paper copies.
Audit trail
Capture timestamps, signer actions, and completion history so lending teams can investigate the application’s signing sequence when questions arise.
Reusable templates
Use templates for recurring application packages while preserving the distinct borrower and property information required for each transaction.
Connected records
Store signed applications and completion evidence in connected systems such as Google Drive, Box, Salesforce, or NetSuite.
How the digital workflow works
The application moves from lender preparation to borrower completion through a controlled signNow sequence.
Upload: Upload application PDF Detect: Review detected fields Assign: Assign borrower signers Finish: Complete and archive
Complete the loan application in signNow
Follow these steps to prepare, sign, and retain the Uniform Residential Loan Application (2005 2026).
Upload form:
Upload the completed loan application PDF. Check fields:
Review detected fields and correct placements. Assign signers:
Add borrower and co-borrower signers. Send document:
Send for signatures and monitor completion. Archive records:
Download the signed application and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Secure signer authentication for loan applications
PKI authentication:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Authentication records:
Audit trail steps for loan records
The signNow audit trail records technical and signer events separately from the application’s substantive borrower information.
Authenticate signer:
Capture timestamp:
Hash document:
Seal record:
Create certificate:
Export evidence:
Find and fill out the correct washington federal residential loan application form
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| *2005 Freddie Mac 65 / Fannie Mae 1003 LO1 [2005-07] 2005 | 4.8 Satisfied (4543 Votes) |



Mobile options for loan applications
Borrowers and loan staff can review the Uniform Residential Loan Application (2005 2026) through signNow mobile apps on iOS and Android. Browser-based access supports desktop completion, while camera capture can digitize supporting pages before signing.
Mobile apps iOS and Android apps support mobile review. Offline signing Offline signing supports limited connectivity. Camera capture Camera capture digitizes supporting documents.
Lenders should manage mobile permissions, signer identity checks, and storage access before sending borrower records. For regulated workflows, confirm consumer electronic-record consent, retention obligations, and organizational policies. Mobile availability does not replace lender review, underwriting requirements, or any required in-person notarization for separate documents.
Best practices for loan applications
Accurate field review, documented consent, controlled routing, and evidence preservation reduce avoidable issues when processing this mortgage application.
Review every borrower field
Document electronic consent
Test signer routing
Archive evidence together
Retention planning for loan applications
No single retention period for this application is supplied here. Apply the lender’s mortgage-record schedule, applicable state requirements, and any transaction-specific rule before deleting signed records.
Federal rule not specified
State rule not specified
Transaction records policy
Compliance review required
Secure archival practice
Risks of inaccurate loan applications
Missing information
Data inaccuracies
Signer attribution
Data exposure
Privacy pitfalls in loan applications
Borrower income, debt, and asset details can appear in broadly shared PDFs without carefully restricted access permissions. Consumer consent records may be incomplete when electronic-record disclosures are not presented before signing the application. Co-borrower fields can be assigned to the wrong person, creating attribution and correction problems during underwriting. Email forwarding can expose the completed application and sensitive financial information beyond the intended lending team.
Troubleshooting loan application workflows
Resolve field, signer, consent, plan, and retention questions before sending the Uniform Residential Loan Application (2005 2026).
Upload the PDF again or inspect its permissions before placing fields. signNow can detect fillable areas, but a scanned or restricted PDF may require manual field placement and review before sending.
Open the recipient settings and confirm each borrower or co-borrower has the correct role and email address. Reassign misplaced fields before sending so signer attribution remains clear in the audit trail.
Business includes templates, audit trails, and legally binding eSignatures at $8/user/month with annual billing. Business Premium adds bulk send at $15/user/month, which may suit repeated application packages.
signNow states that ESIGN and UETA compliance applies to its platform. For a consumer-facing application, provide required electronic-record disclosures and confirm consent, access, and withdrawal procedures under 15 U.S.C. §7001(c).
Use signNow’s audit trail and completion certificate with the signed PDF, then apply the lender’s documented retention schedule. The supplied authorities do not establish one universal retention period for this application.
Business Premium includes bulk send, while Enterprise adds advanced signer authentication and advanced fields. Confirm the selected plan’s capabilities before building a multi-borrower workflow around those features.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.