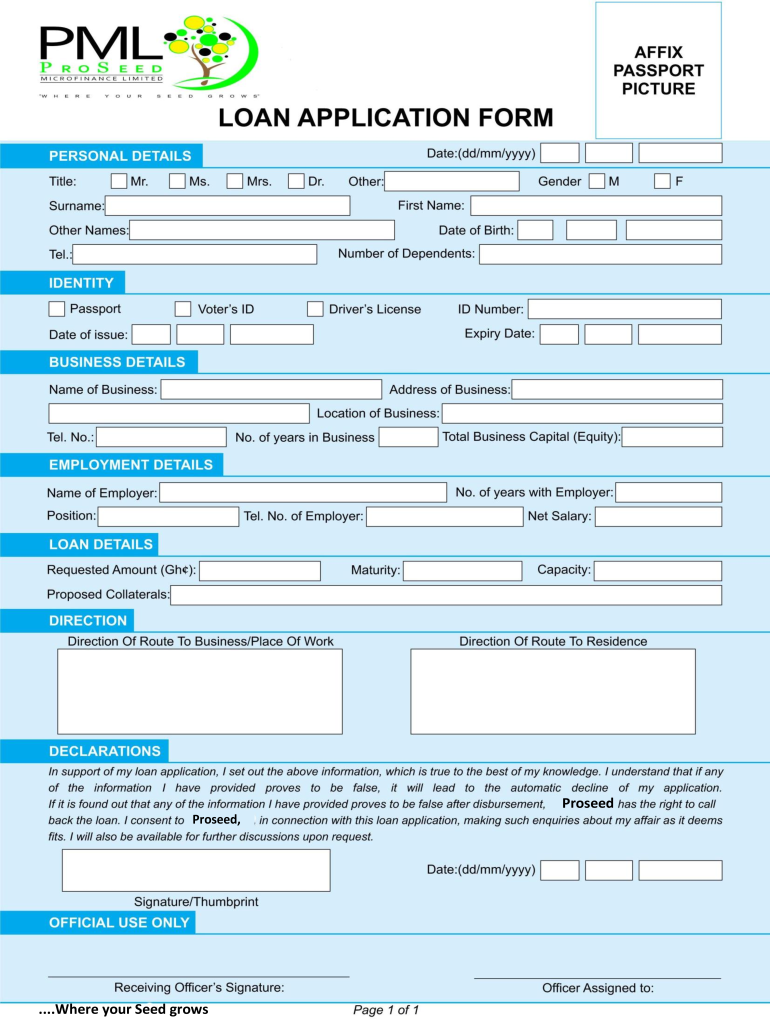
Microfinance Loan Application Form
Get a Loan Application Form 0 template with airSlate SignNow and complete it in a few simple clicks.
What this loan application form does
A Microfinance Loan Application Form collects the borrower information a lender needs to evaluate a small-dollar loan request. It generally records identity, contact details, household or business information, requested amount, intended use of funds, income, expenses, existing obligations, references, and consent for verification. The lender reviews the submitted information, requests supporting documents, and decides whether to approve, decline, or request clarification. In the United States, electronic execution can be supported by ESIGN and applicable state law when intent, consent, attribution, and reliable record retention are established.
Businesses that use this loan form
Microfinance programs, credit unions, and small-business lenders use this form to collect consistent borrower information and signed lending evidence.
Community microfinance organizations can standardize borrower intake, collect guarantor signatures, and keep supporting records with each application instead of managing disconnected paper files. Credit unions and financial services teams can route applications among borrowers, loan officers, reviewers, and approvers while preserving role-specific fields and an audit trail. Small business lenders can reuse a controlled application template, connect signed records to storage, and process borrower requests from desktop or mobile workflows.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who completes the loan application
Microfinance lenders
Microfinance lenders use the form to collect borrower identity, requested financing, repayment information, income evidence, and consent before underwriting. Loan officers can send a structured application for electronic completion, while reviewers use the signed record and audit trail to confirm what the borrower submitted and when.
Borrowers and guarantors
Borrowers, guarantors, and community-based lending partners complete assigned sections from desktop or mobile devices. The workflow separates personal information, business details, supporting documents, and signatures so each participant sees the fields relevant to the loan request.
Complete this loan application in signNow
Use this sequence to prepare borrower information, collect approvals, and preserve a reliable completed application record.
Upload documents:
Upload the lender’s Microfinance Loan Application Form and supporting borrower documents. Review fields:
Let signNow detect fillable areas, then verify every borrower and lender field. Assign signers:
Assign borrower, guarantor, and lender signature fields to the correct parties. Complete and store:
Send the application, collect signatures, and retain the completed record.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Features that support loan processing
signNow organizes the Microfinance Loan Application Form from initial upload through field completion, signature collection, audit review, and controlled storage.
Field detection
Upload the lender’s existing application and let signNow identify likely fillable areas before staff verify field placement and borrower-specific information.
Role-based signing
Assign borrower, guarantor, loan officer, and reviewer fields so every participant completes only the information and approvals assigned to them.
Remote signing
Collect signatures on the application from desktop or supported mobile workflows while preserving the completed document as a single record.
Audit trail
Capture timestamps, signer actions, and document history so the lender can review how the application moved through completion.
Reusable templates
Reuse a controlled application template for repeated lending programs while updating loan-specific amounts, borrower information, and required attachments.
System integrations
Connect completed applications with systems such as Salesforce, NetSuite, Google Drive, Box, or Microsoft 365 for controlled downstream processing.
Authenticate parties to the loan
PKI certificates:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Signer attribution:



Protect borrower information during completion
Borrower income, identification, and banking details may remain visible to recipients who do not need access to the completed application. A consumer-facing application may lack required disclosure of paper-record rights, electronic access, or withdrawal procedures under 15 U.S.C. §7001(c). Sending a completed application through personal email can expose financial information outside the lender’s controlled document workflow. Shared administrator access can obscure which employee viewed, changed, or sent a borrower’s application.
Best practices for loan applications
A controlled workflow reduces transcription errors, protects borrower information, and preserves evidence showing how this application was completed.
Reconcile figures before sending
Assign fields by responsibility
Record electronic consent clearly
Archive the signed record securely
Risks of incomplete loan applications
Consent evidence missing
Missing borrower records
Access controls fail
Signer identity unclear
Legal standing of electronic loan applications
A completed Microfinance Loan Application Form can support a U.S. lending record when the borrower demonstrates intent, consents to electronic records, can be identified, and the lender preserves an accurate, reproducible copy. ESIGN, 15 U.S.C. ch. 96, and applicable state UETA rules generally recognize qualifying electronic signatures; they do not cover wills, codicils, testamentary trusts, or specified court filings.

What the application audit trail records
The audit trail documents the evidence surrounding this borrower’s application rather than replacing underwriting or lender review.
Authenticate signer:
Capture timestamps:
Track document history:
Protect final record:
Review audit trail:
Export evidence:
Troubleshoot this loan application workflow
These answers address field assignment, consent, plan selection, signer access, and the legal limits of electronic loan records.
Upload the original PDF again and verify that it is not password-protected or corrupted. signNow’s field-detection workflow can identify fillable areas, but a loan officer should confirm every detected field before sending the application.
Open the recipient settings and confirm that the borrower, guarantor, and lender reviewer have distinct roles. Reassign fields before sending; changing responsibility after signature can require a new application record and fresh consent.
For consumer-facing electronic records, provide the ESIGN disclosure required by 15 U.S.C. §7001(c), including paper-record access and withdrawal procedures. Retain evidence of consent with the signed application and audit trail.
The signNow Business plan includes legally binding eSignatures, audit trails, templates, and mobile apps at $8/user/month with annual billing. Business Premium adds bulk send at $15/user/month annually; Enterprise adds advanced signer authentication at $30/user/month.
Signers can receive the application by email or signing link and complete assigned fields without editing unrelated sections. If stronger identity evidence is required, configure the available authentication controls and document the lender’s policy.
signNow is ESIGN and UETA compliant, but compliance does not decide whether a particular loan product or state lending rule permits electronic records. Confirm state lending, disclosure, privacy, and retention requirements before deployment.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.