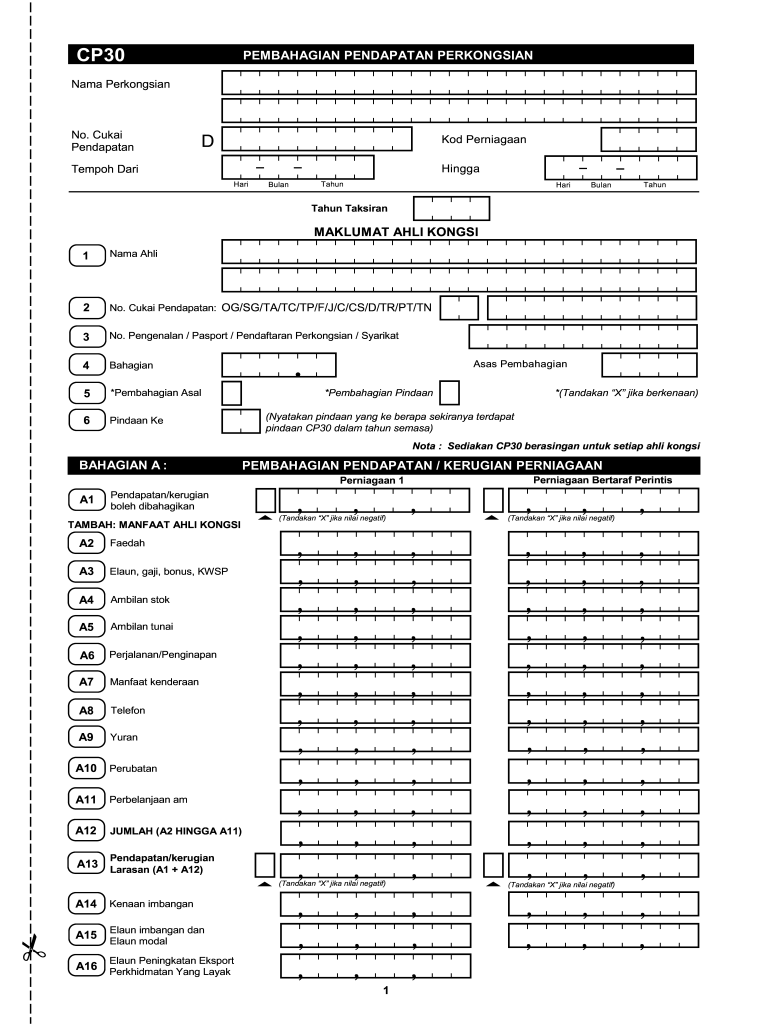
CP30 Pembahagian Pendapatan Perkongsian
Get a Cp30 template with airSlate SignNow and complete it in a few simple clicks.
What CP30 partnership income division means
CP30 Pembahagian Pendapatan Perkongsian is a partnership-income allocation form used to record how partnership earnings are divided among partners. It identifies the partnership, reporting period, participating partners, allocated income amounts, and related declarations. The completed form creates a written record of each partner’s share for accounting, tax, and internal governance purposes. Before signing, partners should confirm that names, identification details, allocation percentages, and amounts match the partnership agreement and supporting records. U.S. users should verify the applicable state and federal filing requirements because the form’s local terminology may not correspond to an IRS form.
Key CP30 workflow features
signNow connects CP30 preparation, partner review, electronic signing, and record preservation in one traceable document workflow.
Structured fields
Place partner names, allocation percentages, dollar amounts, dates, and signatures directly on the CP30 document so reviewers can confirm each required entry before signing.
Flexible delivery
Route one CP30 to each authorized partner by email, or use a signing link when the partnership’s approved process permits link-based access.
Audit trail
Capture signer actions, timestamps, and document history so the completed CP30 can be reviewed alongside the partnership agreement and allocation calculations.
Reusable template
Use templates for recurring partnership distributions while checking each period’s amounts and partner list before sending the document for signature.
Mobile signing
Allow partners to review and sign from signNow mobile apps when a desktop workflow is not practical, subject to the organization’s access controls.
Record preservation
Export the signed CP30 and completion evidence for controlled storage, tax review, and later retrieval under the applicable retention policy.
How the CP30 workflow works
The process connects the approved partnership allocation to a traceable signing record without changing the underlying financial calculation.
Prepare: Upload the approved CP30 document and supporting allocation schedule. Configure: Place partner, amount, date, and signature fields. Route: Send the document to authorized partnership signers. Preserve: Store the signed CP30 with its audit trail.
How to complete CP30 in signNow
Prepare the partnership allocation first, then use signNow to convert the approved CP30 document into a controlled, auditable signing workflow.
Upload document:
Upload the completed CP30 source document to signNow. Add CP30 fields:
Place fields for partner details, amounts, dates, and signatures. Review fields:
Auto-detect fillable areas, then verify every field manually. Send for signing:
Add authorized partners and send the signature request. Collect signatures:
Partners review allocation details and sign electronically. Archive record:
Store the completed CP30 with its audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended CP30 workflow settings
Use a controlled signing workflow that links each signed CP30 to the partnership agreement, allocation calculations, and approval record.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture IP, timestamps, and signer actions |
| Document retention | Retain under the partnership record policy |
| Encryption | TLS 1.2/1.3 and AES-256 protection |
Security controls for CP30 records
Transport encryption:
Storage encryption:
Security reporting:
Information security:
Electronic signatures:
Health information:
Best practices for CP30 completion
Accurate allocation data and a connected record set matter more than the signature technology alone. Apply these controls before and after signing.
Reconcile amounts before sending
Build a controlled CP30 template
Control recipients and approvals
Archive the signed record
CP30 document retention schedule
Retention depends on the record’s tax purpose and applicable state requirements. Apply the longest verified rule to the signed CP30 file.
Three years: federal tax records
Six years: substantial understatement
Indefinite: fraud or no return
State period: verify applicable rule
Policy period: signed CP30
Legal value of a signed CP30 record
A completed CP30 record can support a U.S. business transaction when the parties show intent, consent, signer attribution, and reliable retention under ESIGN and applicable UETA rules. The electronic record does not replace required tax review or state procedures, and exclusions include wills, testamentary trusts, court orders, and certain family-law documents.

Privacy and disclosure pitfalls
Partner names, taxpayer identification details, and distribution amounts can expose sensitive financial information when the completed CP30 document is shared beyond the intended recipients. An unsigned CP30 may lack evidence that every partner consented to the electronic transaction; document consent and provide access to the electronic record. Sending the form to the wrong partner or granting broad template access can disclose allocation data and weaken internal confidentiality controls. A mismatch between the signed CP30, partnership agreement, and accounting ledger can create an evidentiary dispute even when the electronic signature itself is valid.
CP30 troubleshooting and signing questions
Use these answers to resolve allocation, signature, plan, and record-retention questions before the CP30 partnership-income document is finalized.
If the allocation differs from the partnership agreement, pause signing and reconcile the percentage, amount, and reporting period. signNow templates can standardize field placement, but they cannot determine the correct allocation. Under UETA and ESIGN, the electronic record may be enforceable when consent, intent, attribution, and retention requirements are satisfied.
Business includes legally binding eSignatures, audit trails, and templates. Upload the CP30 document, place fields for each partner, and send it for signature. The plan includes 100 signature invites per user annually; additional usage may incur overage fees, so monitor the account before a large partnership distribution cycle.
Business Premium adds bulk send, which is useful when the same CP30 workflow must be sent to multiple partnership groups. It does not validate tax calculations or replace review by the partnership’s accountant. Confirm each recipient, reporting period, and allocation before sending a batch.
signNow can capture signer identity, timestamps, actions, and the completed document in an audit trail. For consumer-facing records, ESIGN may require electronic-record disclosures, access to the electronic format, and a withdrawal procedure under 15 U.S.C. §7001(c). Obtain professional advice for the specific transaction.
A signNow audit trail helps show who signed and when, but an electronic signature does not cure an incorrect allocation or missing partner approval. Preserve the signed CP30, partnership agreement, approval record, and related calculations together under the organization’s retention policy.
signNow supports ESIGN and UETA requirements for electronic signatures, while state law governs many intrastate transactions. Those frameworks do not establish the CP30 form’s tax treatment or filing deadline. Confirm acceptance, submission method, and retention rules with the relevant authority or qualified U.S. adviser.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.