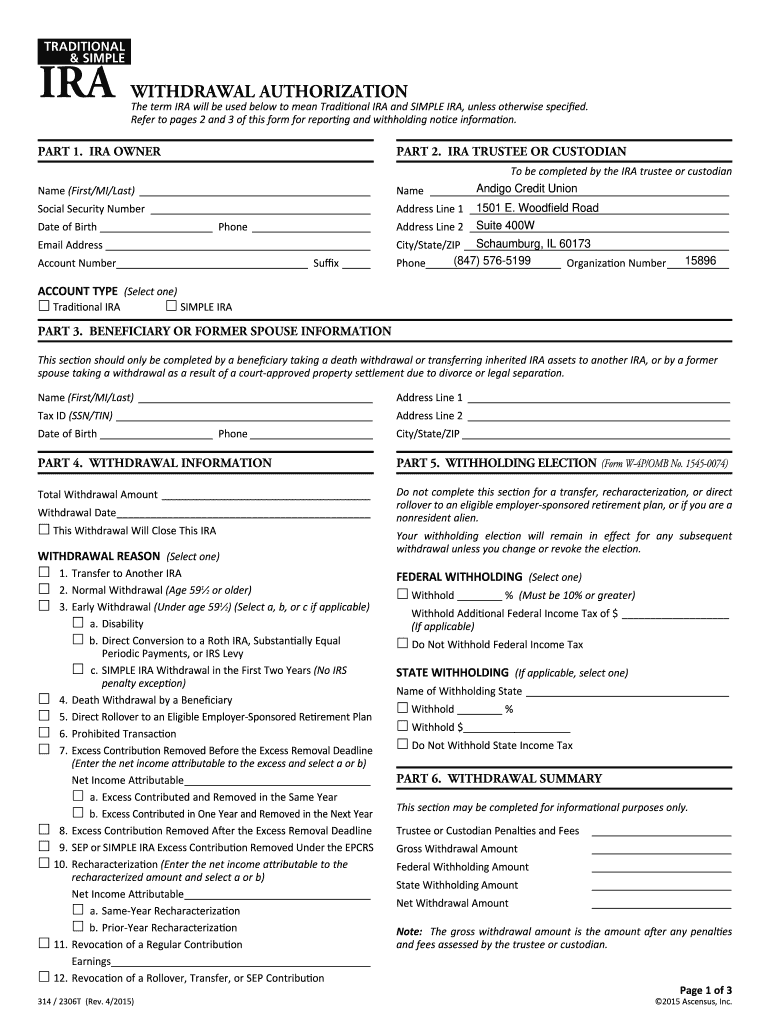
Ira Withdrawal Authorization Form
Use a Ira Withdrawal Authorization Form template to make your document workflow more streamlined.
What the Ira Withdrawal Authorization Form does
An Ira Withdrawal Authorization Form gives an IRA account holder a documented way to approve a retirement-account distribution and direct how the custodian should process it. The form generally identifies the account holder, IRA account, requested withdrawal amount, payment destination, tax withholding election, and signature. With signNow, a sender uploads the form, reviews auto-detected fillable fields, assigns the account holder’s signature and date fields, sends the document, and stores the completed PDF with its audit trail. Custodian-specific instructions and state rules still control acceptance.
Who uses this IRA authorization
Financial services
IRA custodians and financial-services teams use the authorization to document an account holder’s distribution instruction, capture required signatures, confirm payment details, and retain an auditable record before releasing retirement funds.
Account administration
Account holders, plan administrators, and tax professionals use the form to record withdrawal amounts, delivery instructions, and withholding choices before coordinating processing with the IRA custodian.
How to complete the IRA authorization
Prepare the IRA withdrawal request in signNow by checking the account, amount, payment, withholding, and signature information before sending.
Upload form:
Upload the IRA authorization PDF to signNow. Check fields:
Review detected fields and add missing ones. Assign signer:
Assign signature and date fields to the account holder. Send request:
Send the completed request through signNow. Store records:
Review the signed PDF and audit trail.
Ways to send and sign the IRA form
- Use signNow’s web app when preparing the IRA authorization on a desktop, checking fields, assigning the account holder, and reviewing the completed document before archival.
- Use the signNow mobile app when an account holder needs to review and sign the withdrawal authorization from an iOS or Android device.
- Use kiosk mode when a supervised representative helps the account holder complete and sign the authorization on an organization-controlled device.
- Use a shareable signing link when distributing the same controlled IRA authorization entry point to an identified signer without creating a separate email invitation.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
How the Ira form audit trail works
The audit trail records technical evidence around the IRA withdrawal authorization, separate from placing fields or inviting the signer.
Authenticate signer:
Timestamp actions:
Hash document:
Seal record:
Store event history:
Export evidence:
Legal standing of an IRA authorization
An Ira Withdrawal Authorization Form can support admissibility when the signer demonstrates intent, consents to electronic records, can be identified, and the record remains reproducible under ESIGN, 15 U.S.C. ch. 96, and applicable UETA or New York ESRA rules. Wills, codicils, testamentary trusts, certain court orders, and specified family-law filings remain excluded.

Retention periods for IRA records
Choose the retention period based on the authorization’s underlying transaction and applicable recordkeeping rule, not the signature platform alone.
Three to six years for tax records
Six years for HIPAA records
Six years for brokerage records
Three years for payroll records
Seven years for audit records
Retention and record-keeping practices
Retain the signed authorization and supporting evidence according to the underlying IRA transaction, tax, and custodian requirements.
Match retention to the underlying transaction
Export the audit trail after completion
Archive signed records securely
Reconcile authorization and transaction records
Security for IRA withdrawal records
Encryption in transit:
Encryption at rest:
Security certification:
Information security:
Electronic signature law:
Health data protection:
Risks requiring special handling
Incorrect form
Missing instruction
Weak audit trail
Wrong recipient
Challenges when completing an IRA authorization
Entering an incorrect IRA account number or distribution amount can cause custodian rejection, processing delays, or an authorization that does not match the requested withdrawal. Leaving the tax withholding election, beneficiary information, or payment destination blank can prevent the custodian from processing the completed Ira Withdrawal Authorization Form. Sending the authorization before verifying the signer’s email address can expose account information to the wrong recipient and require cancellation or reissuance. Failing to reconcile the signed authorization with the custodian’s transaction record can leave the organization unable to explain the approved amount or distribution date.
Troubleshooting Ira Withdrawal Authorization Form
Resolve field, consent, signing-link, plan, security, and enforceability questions before submitting an IRA withdrawal authorization.
Upload the IRA authorization PDF to signNow, then confirm that auto-detected fields match the account holder’s name, distribution amount, account number, tax withholding election, and signature areas. Add or resize fields manually before sending if any field is missing or misplaced.
The signNow Business plan includes templates, audit trails, and legally binding eSignatures at $8 per user monthly when billed annually. Business Premium adds bulk send at $15 per user monthly annually. Confirm the selected plan before creating repeated withdrawal packets.
For a consumer-facing IRA authorization, provide the ESIGN Act consumer disclosure required by 15 U.S.C. §7001(c), including paper-record rights, electronic-access information, and consent-withdrawal procedures. Store evidence of consent with the signed form and audit trail.
If the account holder cannot open the signing link, resend the invitation or provide a signNow quick invite link. Verify the email address, ask the signer to check spam filtering, and use SMS authentication when the workflow requires stronger identity confirmation.
signNow encrypts data in transit with TLS 1.2 or TLS 1.3 and at rest with AES-256. HIPAA compliance requires a business associate agreement and applies only when protected health information is involved, not merely because an IRA form is signed.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record reproduction are established. They exclude wills, codicils, testamentary trusts, certain court filings, and other listed records; confirm whether the custodian imposes additional paper or notarization rules.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.