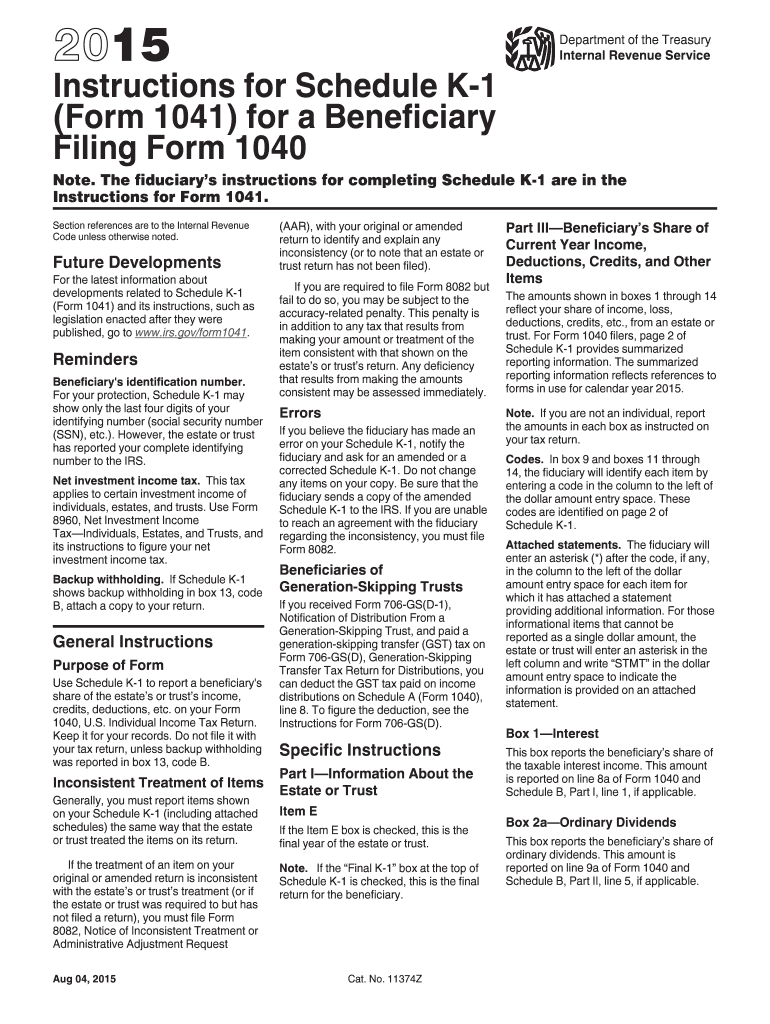
IRS K 1 Form Instructions (2015)
Use the Irs K 1 Form Instructions 2015 template to simplify high-volume document management.
IRS K-1 Form Instructions (2015) explained
IRS K-1 Form Instructions (2015) explain how recipients interpret partnership, S corporation, or trust information reported on Schedule K-1. The instructions connect each box and code with the federal tax treatment described by the Internal Revenue Service. A recipient uses the applicable entity section, reviews income, deduction, credit, and other reported items, and transfers those amounts to the appropriate tax return or supporting schedule. The document is guidance, not a substitute for the entity’s completed Schedule K-1 or professional tax advice. State requirements may require separate review.
Who uses the 2015 K-1 instructions
Partnership recipients
Partnerships distribute partner-level income, deductions, credits, and other items through Schedule K-1 materials.
Shareholders and beneficiaries
S corporations and trusts use K-1 reporting to communicate allocated tax information to shareholders or beneficiaries.
How the 2015 instructions work
The instructions guide recipients from entity classification and reported items to tax-return treatment and supporting-record retention.
Confirm entity type: Identify the entity Locate instructions: Read applicable sections Review K-1 fields: Map reported amounts Preserve documentation: Retain supporting records
Complete K-1 instructions in signNow
Use signNow to prepare the 2015 K-1 instruction document, route it to the intended recipient, and preserve the completed record.
Upload document:
Upload the IRS K-1 instructions PDF. Check fields:
Review detected fields and add missing fields. Add signer:
Add the recipient’s email and signing order. Send document:
Send the document for electronic acknowledgment. Store records:
Review the signed PDF and audit trail.
What the K-1 audit trail records
A signNow audit trail documents the electronic handling of IRS K-1 Form Instructions (2015), separate from the tax interpretation itself.
Authenticate signer:
Capture timestamp:
Hash document:
Seal document:
Record activity:
Export audit trail:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Challenges when using K-1 instructions
Identifying whether the 2015 instructions apply to the partnership, S corporation, or trust information being reported. Mapping Schedule K-1 box numbers and codes to the recipient’s individual tax return without changing source amounts. Separating federal instructions from state reporting requirements, which may require additional schedules or different filing treatment. Preserving the completed instructions, signed acknowledgments, and supporting records for later tax review.
Best practices for K-1 documentation
Accurate tax-year matching, preparer review, controlled signing, and documented retention reduce errors when distributing IRS K-1 Form Instructions (2015).
Match the correct tax year
Verify every reported amount
Separate review from signing
Apply the correct retention rule
Find and fill out the correct irs k 1 form instructions 2015
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| IRS Instructions 1041 - Schedule K-1 2022 | 4.8 Satisfied (1728 Votes) | |
| IRS Instructions 1041 - Schedule K-1 2021 | 4.8 Satisfied (2211 Votes) | |
| IRS Instructions 1041 - Schedule K-1 2020 | 4.8 Satisfied (1472 Votes) | |
| IRS Instructions 1041 - Schedule K-1 2018 | 4.8 Satisfied (3124 Votes) | |
| IRS Instructions 1041 - Schedule K-1 2017 | 4.7 Satisfied (960 Votes) | |
| IRS Instructions 1041 - Schedule K-1 2016 | 4.8 Satisfied (238 Votes) |
Retention periods for K-1 records
Keep IRS K-1 Form Instructions (2015), related schedules, and signed records under the applicable federal and state tax-record rules.
Three years after filing
Six years for understatement
Indefinite for fraud
Indefinite without filing
State period may exceed
Risks of incorrect K-1 instructions
Incorrect tax reporting
Incomplete Schedule K-1
Delayed amended filings
Insufficient audit evidence
Security for K-1 records
AES-256 at rest:
TLS 1.2/1.3 in transit:
SOC 2 Type II certified:
ESIGN and UETA compliant:
Two-factor authentication:
ISO 27001 certified:
Platform requirements for K-1 instructions
IRS K-1 Form Instructions (2015) can be reviewed and signed through a current browser on Windows, macOS, iOS, or Android.
Desktop browsers Chrome, Firefox, Safari, and Edge on Windows 10, Windows 11, and macOS. Mobile access Safari on iOS and Chrome on Android support mobile signing. Connection security TLS 1.2 or newer secures browser connections during document access.
For controlled tax workflows, confirm that managed Windows or macOS devices permit PDF access, browser storage, and secure TLS connections. Mobile users can review documents through iOS or Android applications, while administrators should verify retention, access permissions, and export procedures before distributing tax records.
Legal standing of signed K-1 records
An electronically signed K-1 instruction acknowledgment can support attribution, intent, consent, and record reproducibility under ESIGN, 15 U.S.C. chapter 96, and applicable UETA law. Those rules do not determine tax treatment or replace IRS requirements. Wills, court orders, and other statutory exclusions remain outside this framework.

Key performance indicators that demonstrate SignNow's proven track record.
K-1 instructions troubleshooting
Resolve edition, field-mapping, consent, retention, and access questions before distributing IRS K-1 Form Instructions (2015).
The 2015 instructions describe tax treatment, but they do not replace the entity’s completed Schedule K-1. Upload the actual K-1 separately, compare box numbers and codes, and ask the partnership, S corporation, or trust preparer to correct discrepancies before signing.
signNow’s Business plan includes templates, legally binding eSignatures, and audit trails. Upload the IRS K-1 document, place acknowledgment fields, and retain the completion record. The signer’s electronic act does not determine whether the underlying allocation complies with IRS rules.
The 2015 edition should not be mixed with instructions from another tax year. Compare the document title and edition before uploading, then preserve the source PDF and signed version together so reviewers can identify which guidance the recipient received.
ESIGN and UETA support electronic records when intent, consent, attribution, and reproducibility are established. For consumer-facing records, review the ESIGN disclosure requirements in 15 U.S.C. §7001(c), including access and paper-record rights.
Tax retention depends on the record and facts. IRC §6501(a) generally provides three years after filing, six years for an understatement exceeding 25 percent, and no limit for fraud or an unfiled return.
If the document contains protected health information, use a workflow appropriate for HIPAA-covered activity and confirm whether a business associate agreement is required. signNow identifies HIPAA compliance as requiring a BAA; tax relevance alone does not create HIPAA coverage.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.