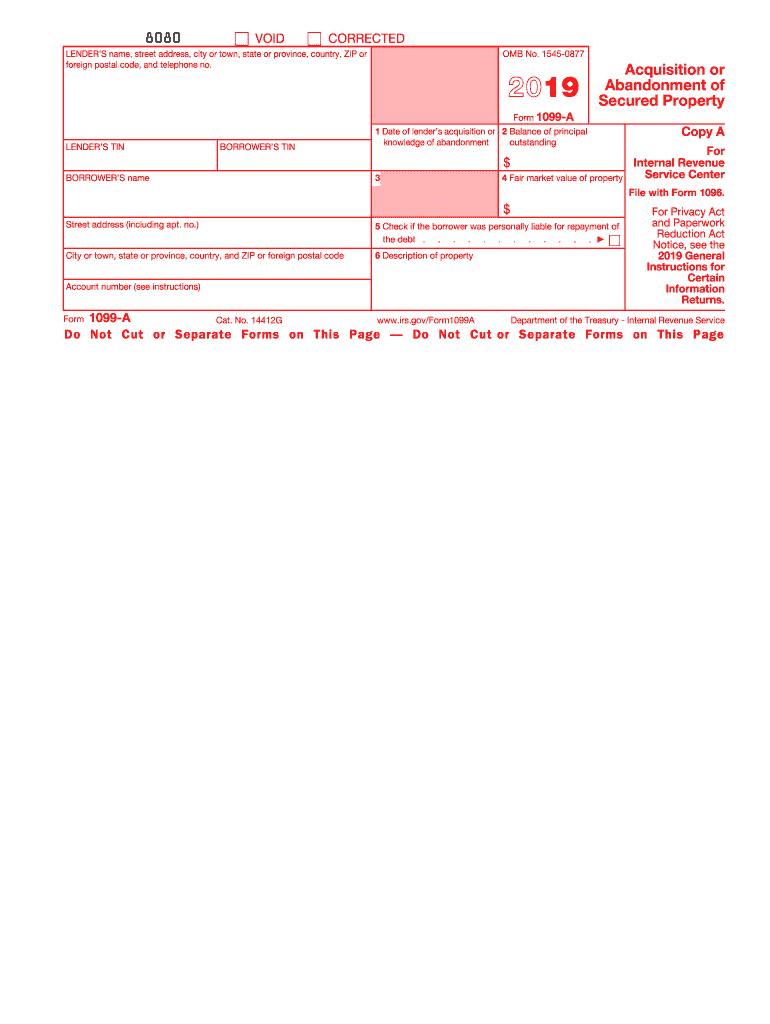
2019 Form 1099 A Acquisition Or Abandonment Of Secured Property
Use a 1099 template to make your document workflow more streamlined.
What Form 1099-A reports
The 2019 Form 1099-A reports a lender’s acquisition of, or the borrower’s abandonment of, property securing a debt. It identifies the borrower and property, reports the balance of principal outstanding, and states the property’s fair market value. The form also indicates whether the borrower remained personally liable for repayment. Lenders use the information to provide a borrower statement and support federal tax reporting. SignNow can hold the prepared PDF, route it for review or signature where appropriate, and preserve the completed document with an audit trail; it does not determine the tax amounts or replace IRS filing procedures.
Business types using Form 1099-A workflows
Form 1099-A workflows are most useful where secured-property events require coordinated tax-document preparation, review, signing, and retention.
Mortgage lenders and servicing teams use Form 1099-A to document secured-property acquisition or abandonment details, including the borrower’s outstanding principal and property fair market value, before transmitting tax information to the borrower and IRS. SignNow organizes review and signature evidence in one record for controlled processing. Financial institutions with distributed tax operations can route Form 1099-A records through role-based signNow workflows, allowing specialists to verify property information, authorized reviewers to approve the document, and administrators to preserve the completed form and audit trail for later tax inquiries. Smaller lenders and property-focused finance practices can upload the 2019 form, place required fields, and send it electronically without building a custom tax-document system. The workflow reduces manual handoffs while keeping borrower information, signer actions, and completion evidence together.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the Form 1099-A workflow works
The workflow moves from document preparation to authorized review, electronic signing, and auditable record storage.
Upload form: Upload the 2019 Form 1099-A PDF Check fields: Review fields for lender and borrower information Send securely: Send the completed form to authorized signers Archive record: Store the signed record with its audit trail
Complete Form 1099-A in signNow
Prepare the form carefully, verify its tax information, and use signNow to coordinate review and preserve completion evidence.
Upload document:
Upload the 2019 Form 1099-A PDF. Review fields:
Use auto-detection, then verify each field. Assign recipients:
Add authorized recipients and signing roles. Complete workflow:
Send, monitor, and download the completed record.
Inside the Form 1099-A audit trail
A signNow audit trail records the evidence surrounding completion of the 2019 Form 1099-A, separate from preparing the form fields.
Authenticate signer:
Capture timestamp:
Record document hash:
Seal document:
Log activity:
Export evidence:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended setup for Form 1099-A workflows
Configure each workflow around signer identity, document integrity, and retention obligations for Form 1099-A records.
| Setting | Recommendation |
|---|---|
| Authentication method | Two-factor authentication with role-based provisioning |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture timestamps, IP addresses, and signer actions |
| Document retention | Retain records under applicable IRS requirements |
| Encryption | TLS 1.2/1.3 in transit and AES-256 at rest |
Best practices for Form 1099-A
Accurate source data, controlled review, and linked records help lenders handle the 2019 Form 1099-A consistently.
Verify property and debt information
Confirm personal-liability status
Separate preparation and approval
Retain the signed evidence
Form 1099-A record retention schedule
Retention depends on the tax record, filing history, understatement level, fraud circumstances, and any longer state requirement.
Three years for tax records
Six years for understatement
Indefinite retention for fraud
Indefinite retention without filing
State rules may extend retention
Form 1099-A preparation challenges
Transcribing the principal balance or fair market value incorrectly can create inconsistent borrower and lender tax records. Failing to confirm personal-liability status can misstate the debt information reported on the 2019 Form 1099-A. Sending the form before authorized review can leave property, borrower, or lender details incomplete. Separating the signed PDF from its audit trail weakens the record needed to explain document history.
Risks from incorrect Form 1099-A handling
Tax data error
Notice failure
IRS penalty
Evidence gap
Security controls for Form 1099-A records
Transport encryption:
Stored encryption:
Control reporting:
Security management:
Signer verification:
Activity evidence:
Platform requirements for Form 1099-A
SignNow supports browser-based preparation on Chrome, Firefox, Safari, and Edge, with access from Windows and macOS computers. The signNow mobile apps support iOS and Android for reviewing and signing Form 1099-A documents. Use an HTTPS connection with TLS 1.2 or TLS 1.3 for protected transmission.
Browsers Chrome, Firefox, Safari, and Edge Desktop systems Windows and macOS desktop access Mobile apps iOS and Android mobile apps
Lenders deploying Form 1099-A workflows should manage access through organizational accounts, role permissions, and approved devices. Teams needing automated routing can evaluate signNow API access and integrations with systems such as NetSuite, Salesforce, Google Drive, or Microsoft 365. Configure authentication and retention according to internal controls and applicable IRS recordkeeping requirements.



Pricing and feature comparison
The comparison uses verified signNow plan information; competitor pricing and feature values are marked Not verified when unavailable in the supplied data.
| Features | Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|---|
| Annual Business price | $8/user/month | Not verified | Not verified | Not verified | Not verified | |
| Free trial availability | 7 days, no card required | Not verified | Not verified | Not verified | Not verified | |
| Audit trail availability | Included in Business | Not verified | Not verified | Not verified | Not verified | |
| Bulk send availability | Business Premium plan | Not verified | Not verified | Not verified | Not verified | |
| HIPAA compliance availability | Compliant with BAA | Not verified | Not verified | Not verified | Not verified |
Form 1099-A troubleshooting questions
These answers address field review, electronic-signature validity, IRS responsibilities, and signNow workflow controls for the 2019 Form 1099-A.
SignNow’s document editor can auto-detect fields after upload, but detected fields still require review. Check the lender, borrower, property, principal-balance, fair-market-value, and personal-liability entries against source records before sending the 2019 form.
The Business plan includes legally binding eSignatures, templates, and audit trails at $8 per user per month when billed annually. Business Premium adds bulk send at $15 per user per month annually, which may suit repeated lender workflows.
Electronic signing is generally recognized under ESIGN and UETA when intent, consent, attribution, and record retention requirements are satisfied. The lender remains responsible for confirming that the specific Form 1099-A workflow and recipient communications meet applicable IRS procedures.
For consumer-facing electronic records, ESIGN requires disclosure of the right to receive paper records, access to the electronic format, and procedures for withdrawing consent under 15 U.S.C. §7001(c). Apply those requirements when the transaction involves a consumer.
SignNow can preserve the completed PDF and audit trail, but it does not file Form 1099-A with the IRS or determine tax treatment. Confirm filing, furnishing, and retention duties using current IRS instructions and organizational tax procedures.
Use role permissions, signer authentication, and the exported audit trail to investigate an incomplete or disputed signing event. If the property data or debt figures are wrong, correct the source form and rerun review rather than altering the completed record.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.