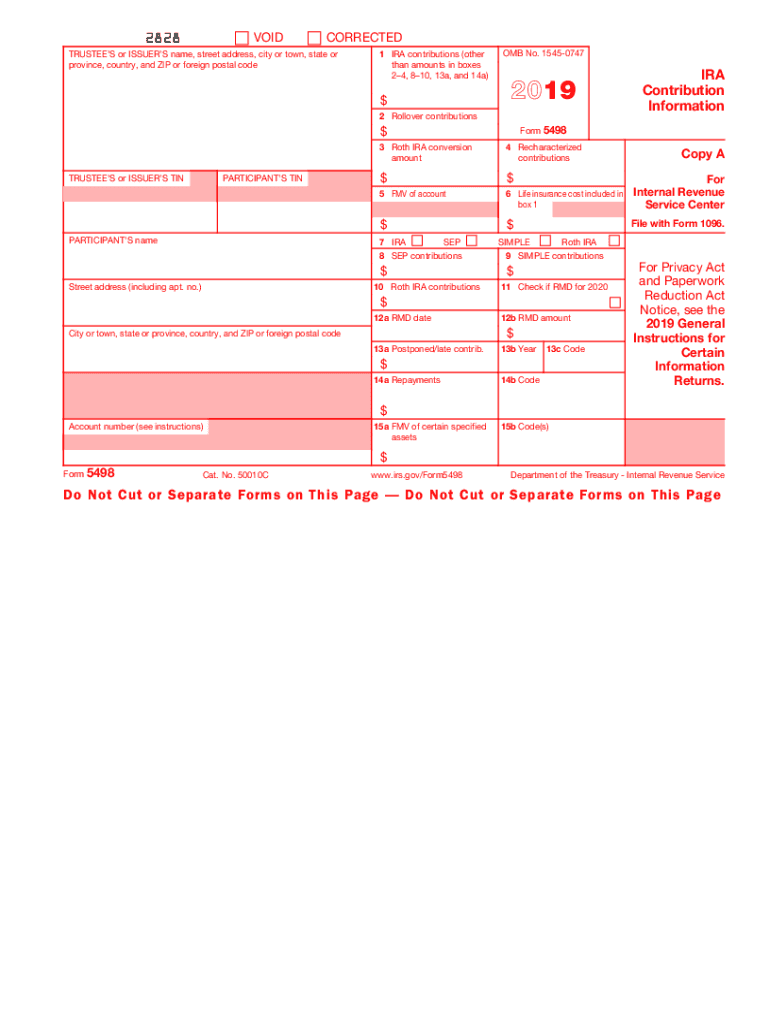
2019 Instructions For Forms 1099 R And 5498 Irsgov
Use a Form 5498 template to make your document workflow more streamlined.
What these IRS instructions cover
2019 Instructions For Forms 1099-R and 5498 explain how trustees, custodians, issuers, and plan administrators report retirement distributions, pension payments, IRA contributions, rollovers, and related information to the IRS and recipients. The instructions support preparation of Forms 1099-R and 5498, including recipient identification, distribution codes, taxable amounts, contribution information, and filing copies. They do not replace the forms themselves or establish a general e-signature requirement. Use the instructions to identify the correct reporting boxes, recipient statements, filing procedures, and recordkeeping responsibilities for the 2019 reporting year.
Who works with these instructions
Plan administrators
Trustees, custodians, and plan administrators use the instructions to prepare retirement distribution and contribution reporting for Forms 1099-R and 5498. They need accurate payer details, recipient taxpayer information, distribution codes, taxable amounts, IRA contribution data, and retained filing evidence.
Tax teams
Tax and finance teams use the instructions to review information returns before sending recipient copies or maintaining internal records. signNow can route the completed document for review, capture acknowledgment, and store the signed record with its audit trail.
How to prepare these IRS instructions
Use the 2019 instructions to map retirement reporting data to the correct Form 1099-R or Form 5498 fields, then preserve the completed record and signing history.
Identify the form:
Confirm whether the document concerns Form 1099-R reporting, Form 5498 reporting, or both. Upload the document:
Upload the 2019 instructions or working form and review detected fields before editing. Complete the fields:
Enter payer, trustee, recipient, distribution, contribution, and account information from authoritative records. Set signer controls:
Add signer roles, recipient email addresses, and SMS authentication where identity verification is needed. Send and store:
Send the completed document, monitor status, and retain the signed copy with its audit trail.
Recommended reporting workflow setup
Configure the 2019 retirement reporting workflow around verified signer identity, evidence preservation, and the applicable IRS record-retention rule.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Electronic signature with signer intent |
| Audit trail | Enable full audit trail capture |
| Document retention | Three years under IRC §6501(a) |
| Encryption | TLS 1.2/1.3 and AES-256 encryption |
What the audit trail records
A signNow audit trail separates identity, timing, document integrity, and retrieval evidence for completed 2019 retirement reporting records.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Log activity:
Export evidence:
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Features for 2019 retirement reporting
The workflow combines field preparation, recipient routing, signer evidence, and retention controls around Forms 1099-R and 5498 reporting records.
Field detection
Upload the 2019 instructions or related working document, then review automatically detected fields before entering payer, recipient, and retirement-account information.
Controlled routing
Route the reporting document to a designated reviewer or recipient without requiring paper delivery or an in-person exchange.
Audit trail
Capture signer actions, timestamps, and completion details alongside the 2019 retirement reporting record for later review.
Reusable templates
Use templates for recurring Form 1099-R or Form 5498 preparation while preserving the fields required by the applicable instructions.
Signer verification
Apply signer authentication controls, including SMS OTP where the reporting workflow requires stronger attribution.
Record retention
Retain the completed document and exported audit evidence according to IRC §6501 and applicable state requirements.



Processing stages for retirement forms
A controlled sequence helps separate data preparation, recipient review, completion, and tax-record retention for the 2019 reporting documents.
Prepare reporting data
Deliver to reviewers
Complete recipient review
Archive the record
Retention periods for retirement reporting records
The 2019 instructions do not create one universal retention period; apply the federal tax rule that matches the record and reporting circumstance.
Three years: tax records
Six years: understatement
Indefinite: fraud
Indefinite: no return
Longer period: state rules
Best practices for retirement reporting records
Accurate field review, complete evidence export, and rule-based retention reduce avoidable errors when using the 2019 instructions for Forms 1099-R and 5498.
Reconcile every reporting field
Export the audit trail
Apply the correct retention rule
Limit access to taxpayer data
Risks in retirement reporting workflows
IRC §6721 penalties
Incorrect information return
Weaker dispute response
Taxpayer privacy exposure
Challenges when preparing the 2019 instructions
Confusing Form 1099-R distribution codes with Form 5498 contribution reporting can place correct data in the wrong filing workflow. Entering an incorrect taxpayer identification number or recipient address can produce an inaccurate information return. Treating the instructions as the form itself can leave required payer, recipient, account, or distribution fields incomplete. Retaining only a signed copy without the audit trail can weaken evidence of delivery, review, and signer activity.
Security controls for tax records
Transport encryption:
Stored data encryption:
Security reporting:
Information security:
Electronic signatures:
Protected information:
Compare tools for IRS reporting records
For 2019 Forms 1099-R and 5498 workflows, compare verified signNow plan facts with vendor details that were not verified in the supplied source.
| Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|
| Starting price | $8/user/month annually | Not verified | Not verified | Not verified | Not verified |
| Free trial | 7 days, no card required | Not verified | Not verified | Not verified | Not verified |
| Bulk send | Business Premium includes bulk send | Not verified | Not verified | Not verified | Not verified |
| Audit trail | Included with Business plan | Not verified | Not verified | Not verified | Not verified |
| HIPAA support | Available with BAA requirement | Not verified | Not verified | Not verified | Not verified |
Troubleshooting 2019 IRS reporting workflows
Resolve field, signer, plan, retention, and compliance questions before sending Forms 1099-R or 5498-related records to recipients.
Upload the working PDF again and inspect detected fields before sending. signNow’s Business plan supports templates and audit trails, but field detection does not determine whether a box contains the correct IRS reporting data. Compare each entry with the payer’s authoritative records and the 2019 instructions.
The Business plan is listed at $8 per user per month with annual billing. It includes legally binding eSignatures, templates, audit trails, and mobile apps. Business Premium adds bulk send, which may matter when preparing multiple recipient documents, while Enterprise adds advanced signer authentication.
ESIGN and UETA generally recognize electronic signatures when intent, consent, attribution, and record retention are established. For consumer-facing electronic records, 15 U.S.C. §7001(c) also addresses consumer disclosure and access requirements. Confirm whether the specific tax workflow requires additional IRS or organizational controls.
Use signer authentication such as email verification or SMS OTP, confirm the recipient’s identity, and preserve the signNow audit trail. The audit trail should show timestamps, actions, and completion evidence; it does not replace checking taxpayer identification numbers or reporting amounts against source records.
Export the completed document and audit trail, then retain them under the applicable federal tax rule. IRC §6501(a) generally uses three years from filing; six years may apply when income was understated by 25% or more, and indefinite retention may apply for fraud or no return.
signNow’s Business Premium plan includes bulk send, while the supplied vendor data does not verify comparable DocuSign, Adobe Sign, PandaDoc, or Dropbox Sign features. If bulk preparation is required, confirm the recipient data, template fields, and plan limits before sending multiple documents.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.