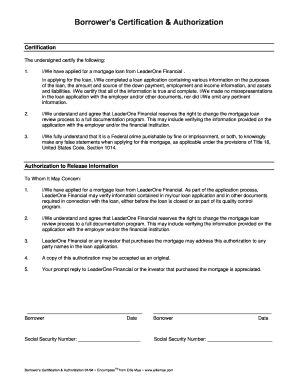
Borrower's Certification And Authorization The 2 Mortgage Guys Form
Use a Borrower's Certification And Authorization The 2 Mortgage Guys template to make your document workflow more streamlined.
What this borrower authorization does
The Borrower's Certification And Authorization The 2 Mortgage Guys Form records a borrower's certification and permission for a mortgage-related process. It gives the borrower a structured place to confirm personal information, acknowledge authorization language, and sign the document. With signNow, a lender or loan coordinator uploads the form, reviews automatically detected fillable fields, assigns signer roles, sends it for electronic signature, and preserves the completed document with an audit trail. The form itself remains the controlling source for required fields, disclosures, and lender-specific instructions.
Who uses this borrower form
Borrowers
Mortgage borrowers use the form to certify the information requested by the lender and authorize specified processing or verification activities.
Mortgage teams
Loan officers, processors, and mortgage operations teams prepare the document, route it to the correct signer, and retain the signed record for the loan file.
How the form workflow works
The signNow workflow keeps the lender’s original borrower authorization intact while adding controlled preparation, signing, and recordkeeping steps.
Upload: Upload the exact lender-provided PDF. Prepare: Auto-detect and verify fillable fields. Route: Assign borrower and lender participants. Complete: Collect signatures and archive evidence.
Complete the borrower authorization
Follow this sequence to prepare, sign, and preserve the completed Borrower's Certification And Authorization The 2 Mortgage Guys Form.
Upload form:
Upload the borrower authorization PDF to signNow. Check fields:
Review detected fields and correct placement. Add signers:
Add the borrower and lender participants. Send document:
Send the authorization for electronic signature. Archive records:
Store the completed PDF and audit trail.
Choose the right signing method
- Use the signNow web app when a loan coordinator uploads the borrower authorization, checks detected fields, and sends the prepared document from a desktop workflow.
- Use the signNow mobile app when a borrower or loan professional needs to review and sign the authorization from an iOS or Android device.
- Use kiosk mode when staff supervise an in-office signing session and need the borrower to complete the authorization on a shared device.
- Use a shareable signing link when a lender needs to distribute the same authorization through an approved borrower portal or controlled communication channel.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Recommended workflow settings
Configure the borrower authorization for identifiable signers, documented consent, and controlled retention.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Enable completion certificate and action log |
| Document retention | Retain according to lender policy |
| Encryption | TLS in transit and AES-256 at rest |
Features for borrower authorizations
signNow connects preparation, borrower signing, authentication, and evidence preservation around the exact authorization document.
Field detection
Upload the lender’s borrower authorization and review automatically detected fields before assigning the borrower’s signature and required dates.
Remote signing
Send the prepared authorization directly to the borrower by email, or use a controlled signing link for an approved workflow.
Audit trail
Capture the borrower’s signature event with timestamps, signer activity, and document history supporting the loan file.
Signer verification
Use SMS OTP or another configured authentication method when the lender requires stronger evidence connecting the borrower to the signing event.
Record control
Keep the signed authorization and completion evidence together, reducing searches across email attachments and separate document folders.
Reusable template
Use templates when the same lender-approved authorization must be prepared repeatedly without changing its required language or signer roles.
Security for borrower records
Transport encryption:
Storage encryption:
Security reporting:
Security standard:
Electronic records:
Protected health data:


Challenges with borrower authorizations
Borrower names, property details, and authorization language may be incomplete, creating review delays before a lender can rely on the document. A signer may use an email address that cannot be independently connected to the borrower, weakening attribution evidence. Mortgage teams can lose track of the final signed copy when email attachments, revisions, and lender-system records are stored separately. Submitting an authorization without checking state-specific notarization or lender instructions can require a replacement document and another signing cycle.
Legal standing and evidence
A completed Borrower's Certification And Authorization The 2 Mortgage Guys Form can document borrower intent and authorization when the signer is properly attributed, consents to electronic records, and the record remains reproducible. ESIGN, 15 U.S.C. chapter 96, and applicable UETA law generally recognize qualifying electronic signatures, but exclude wills, court orders, and specified family-law documents.

How the audit trail records signing
The audit trail separates the borrower’s signing evidence from the form’s substantive certifications and authorization language.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Inspect history:
Export evidence:
Recordkeeping practices for this form
Use the executed authorization, audit evidence, access controls, and lender retention policy together when managing the completed loan record.
Export the signed form and audit trail
Apply the lender’s retention schedule
Limit access to authorized staff
Review every executed authorization
Rules and document exclusions
Lender instructions
Notarization
Wills
Real-estate deeds
Key performance indicators that demonstrate SignNow's proven track record.
Borrower authorization troubleshooting
Resolve field, signer, plan, legal-effect, authentication, and record-storage questions before relying on the completed authorization.
Upload the PDF, then correct detected fields before sending. signNow’s Business plan includes templates and audit trails, so confirm the borrower, lender, and any date fields are assigned correctly before delivery.
Business is listed at $8 per user per month with annual billing. It includes 100 signature invites per user per year; subscription overage fees may apply, so review current plan terms before high-volume use.
Business Premium is listed at $15 per user per month with annual billing and includes bulk send. Use it only when the same borrower authorization must be sent repeatedly to separate recipients.
signNow states that ESIGN and UETA compliance is supported. Legal effect still depends on intent, consent, attribution, and retention; consumer-facing transactions also require the disclosures described in 15 U.S.C. §7001(c).
Enable SMS OTP or another available authentication control when lender policy requires stronger identity evidence. The audit trail records signing activity, but authentication settings should match the loan file’s risk requirements.
Export the completed authorization and its audit evidence after signing, then store both with the loan record. Retention is governed by lender policy and applicable records rules, not by the form name alone.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.