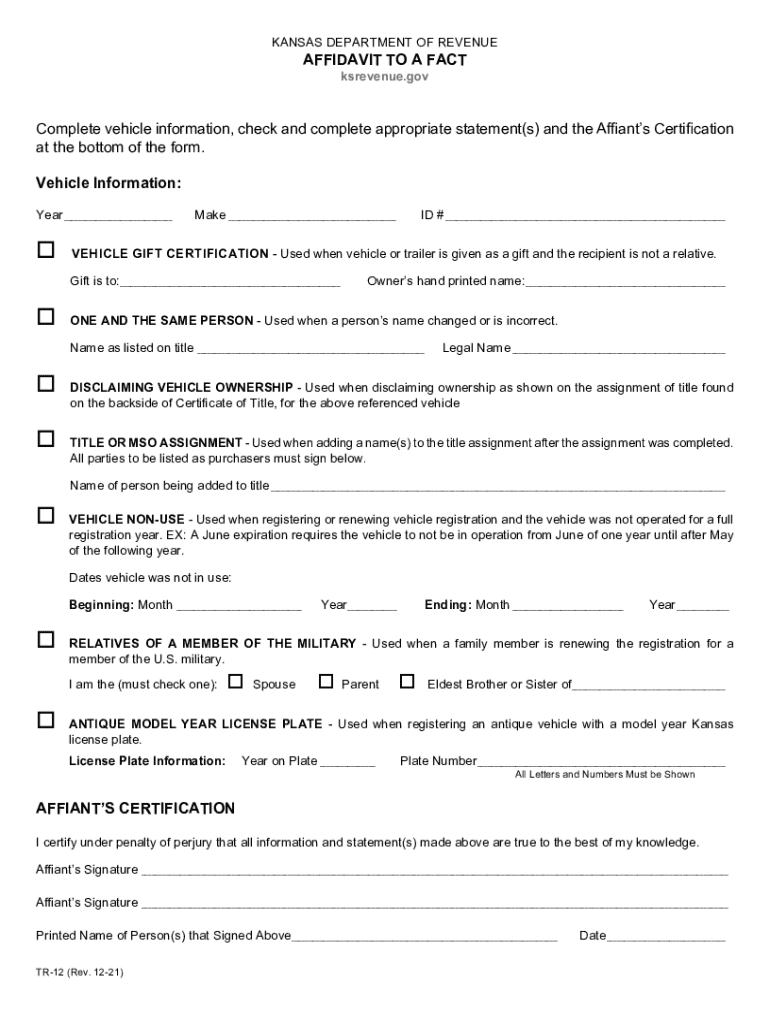
Tr 12 Affidavit To A Fact Rev 12 21 This Publication Will Address Whether Sales Or Compensating Use Tax Is Due On A Particular V
Use a TR 12 Affidavit To A Fact Rev 12 21 This Publication Will Address Whether Sales Or Compensating Use Tax Is Due On A Particular V 2022 template to make your document workflow more streamlined.
What the TR-12 affidavit does
The TR-12 Affidavit To A Fact Rev 12 21 is a tax-related statement used to address whether sales or compensating use tax is due on a particular transaction. It records the relevant facts, supporting documents, and signer affirmation rather than independently determining taxability. Complete the transaction description carefully, identify the parties and tax treatment, attach invoices or exemption evidence when appropriate, and route the form to an authorized signer. signNow can upload the document, detect or add fields, send it for signature, and preserve the completed record with an Audit Trail. Apply the governing state tax rule before relying on the affidavit.
Who uses the TR-12 affidavit
Tax and finance teams
Tax departments and accounts-payable teams use the TR-12 affidavit to document facts supporting a sales-tax or compensating-use-tax treatment. They can complete transaction details, attach invoices or exemption evidence, route the statement to an authorized signer, and retain the completed package for review.
Transaction stakeholders
Vendors, purchasers, and state-tax reviewers use the signed TR-12 record when a transaction requires a factual explanation of whether sales or compensating use tax is due. The workflow keeps the form, attachments, signer evidence, and Audit Trail together for controlled review.
Business types that use TR-12
The TR-12 affidavit is most useful where a transaction’s sales or compensating use tax treatment requires documented facts and accountable approval.
Tax departments can document transaction facts, attach invoices, and route the TR-12 affidavit to authorized reviewers while preserving an auditable completion record. Purchasing organizations can use the affidavit to record why sales or compensating use tax was assessed, exempted, or referred for review. State-tax consultants and legal teams can examine the signed statement, supporting evidence, and Audit Trail without relying on disconnected email attachments.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How to complete the TR-12 affidavit
Prepare the TR-12 affidavit in signNow by checking its tax facts, routing the signer, and preserving the completed evidence package.
Upload the form:
Upload the TR-12 affidavit and supporting tax documents. Check the fields:
Review detected fields and add missing signer fields. Send for signature:
Enter the authorized signer’s email and send securely. Store the record:
Download the signed affidavit and Audit Trail.
Recommended TR-12 workflow settings
Configure the TR-12 affidavit around verified signer identity, preserved evidence, restricted access, and the retention rule for the underlying tax transaction.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS verification |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Export after completion |
| Document retention | Apply IRC §6501(a) or state rule |
| Encryption | AES-256 at rest and TLS 1.2/1.3 |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Inside the TR-12 audit trail
The signNow Audit Trail connects the TR-12 signer, document, timestamps, and transaction history into an exportable completion record.
Authenticate signer:
Capture timestamps:
Hash document:
Seal evidence:
Check activity:
Export record:
Signer authentication and certificates
PKI signing:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Audit trail:
Find and fill out the correct tr 12 affidavit to a fact rev 12 21 this publication will address whether sales or compensating use tax is due on a particular
airSlate SignNow helps you fill in and sign documents in minutes, error-free. Choose the correct version of the editable PDF form from the list and get started filling it out.
| Versions | Form popularity | Fillable & printable |
|---|---|---|
| KS TR-12 2022 | 4.5 Satisfied (26 Votes) | |
| KS TR-12 2015 | 4.8 Satisfied (1323 Votes) |
Retention and record-keeping practices
Keep the affidavit, supporting tax evidence, and signNow completion record together under the retention rule applicable to the underlying transaction.
Apply the correct retention period
Export the audit trail
Secure the complete record
Preserve source and executed copies
TR-12 record retention schedule
The TR-12 affidavit has no supplied universal retention period; apply the rule governing the underlying tax record and preserve the signed evidence accordingly.
3 years from filing
6 years after filing
Indefinite for fraud
State rule may extend
Until dispute resolution
Risks of incomplete TR-12 records
Tax dispute
Evidentiary gap
Incomplete record
Review delay
Signer challenge
Enforceability concern
Privacy and disclosure pitfalls
Including taxpayer identification numbers or personal addresses in every shared copy increases exposure beyond the reviewers who need them. Sending the affidavit without documenting electronic consent can weaken evidence that the signer agreed to use an electronic record. Giving every team member download access can expose transaction details and supporting tax documents unnecessarily. Attaching invoices or exemption certificates without checking recipient scope can disclose unrelated customer or vendor information.
Platform requirements for TR-12 signing
Use signNow from Windows 10 or later or macOS with Chrome, Firefox, Safari, or Edge. The signNow mobile applications support iOS and Android devices for reviewing and signing the TR-12 affidavit. A stable internet connection is needed to upload, route, and retrieve the completed record.
Desktop systems Windows 10 or later and macOS support browser-based signing workflows. Supported browsers Chrome, Firefox, Safari, and Edge support signNow browser access. Mobile apps iOS and Android apps support mobile review and signing.
Organizations should manage access through signNow roles, approved devices, and controlled storage. Teams handling sensitive tax information can configure signer authentication, export Audit Trails, and connect storage or business systems through available signNow integrations. Confirm state tax and retention requirements separately before deployment.
TR-12 affidavit troubleshooting
Resolve document, signer, tax-classification, and electronic-record questions before treating the completed TR-12 affidavit as final evidence.
Upload the original TR-12 file again and check whether fields were flattened or scanned. signNow can detect fillable fields in supported documents, but a flattened PDF may require manual field placement before sending.
Confirm the recipient email address and resend the invitation from signNow. The Business plan includes templates and audit trails; the signer can often complete the affidavit without creating a signNow account.
Use SMS authentication or another available signer-verification method when the affidavit contains sensitive tax information. signNow supports authentication controls, while ESIGN and UETA require evidence of intent, attribution, and record retention.
The completed affidavit is not automatically a state tax determination. Review the transaction facts against the applicable state sales-tax statute or department guidance before relying on the signed statement.
Preserve the signed PDF and exported Audit Trail together. signNow Business includes audit trails, while ESIGN and UETA focus on intent, attribution, consent where required, and reliable reproduction of the electronic record.
If consumer-facing disclosure applies, provide the ESIGN disclosure before requesting an electronic signature and confirm access to electronic records. The disclosure should explain paper-record rights and consent withdrawal procedures under 15 U.S.C. §7001(c).
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.