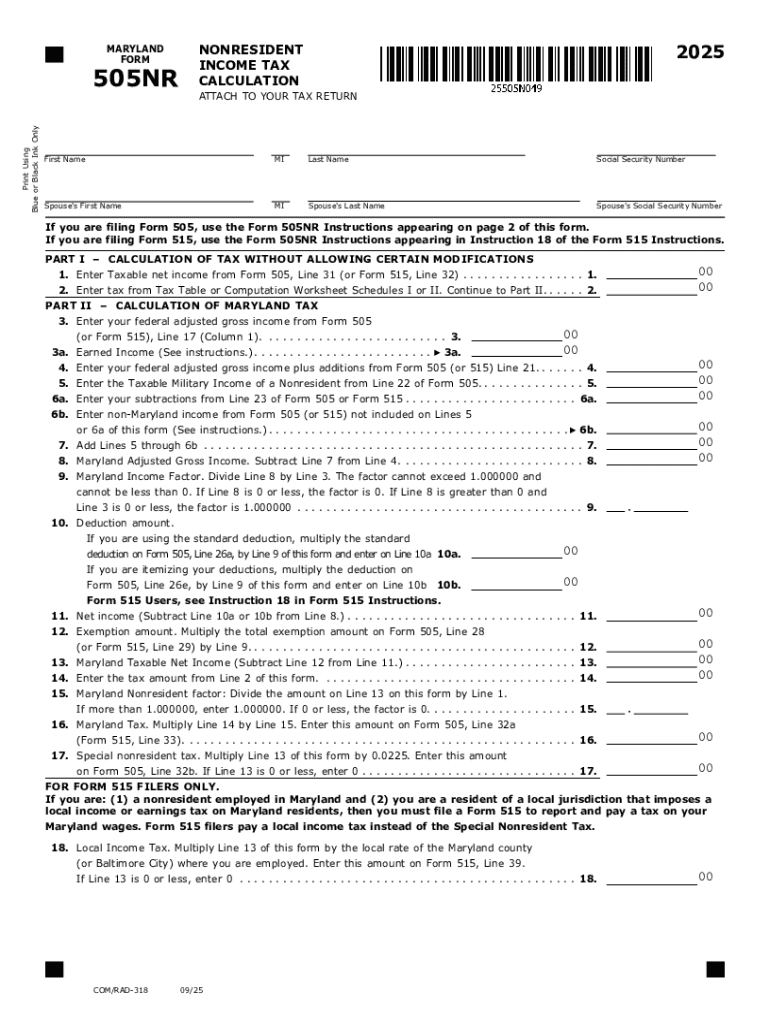
State & Local Tax Forms & Instructions
Use a State & Local Tax Forms & Instructions template to make your document workflow more streamlined.
What these tax forms do
State and Local Tax Forms and Instructions are U.S. tax documents used to collect, report, or explain taxpayer and state tax information. The exact form depends on the state, transaction, taxpayer status, and reporting obligation. A payer generally uses the completed information to support tax reporting and withholding decisions; a recipient reviews identifying details before signing or returning it. For federal records, IRC §6501(a) generally establishes a three-year assessment period, while state requirements may impose different retention rules.
Businesses that use these tax forms
The workflow fits payers, accounting teams, contractors, and enterprises that collect tax information before reporting or payment.
Solo accountants use reusable signNow templates to collect taxpayer details from independent contractors, then download completed records for client files and reporting preparation without rekeying every form manually. Financial-services operations teams route State and Local Tax Forms through delegated senders, role-based permissions, and audit trails when collecting vendor information across multiple business units. Enterprise tax departments connect signNow with NetSuite or Salesforce to associate completed taxpayer forms with vendor records, preserve signer evidence, and control access to sensitive identification information.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses these tax forms
Payers
Payers collect taxpayer identification information from contractors, vendors, and other recipients before preparing applicable information returns.
Recipients
Contractors and vendors review their identification details, provide required certifications, and retain a completed copy for their records.
How the tax form workflow works
A payer can prepare, route, complete, and retain State and Local Tax Forms through one documented digital workflow.
Upload the form: Upload the State and Local Tax Forms file into signNow. Map required fields: Review detected fields and add taxpayer, payer, and signature fields. Send for completion: Send the prepared form to the contractor or taxpayer securely. Archive the record: Store the signed form with its completion certificate and audit trail.
Complete State and Local Tax Forms
Use this sequence to prepare the form, collect the required information, and preserve evidence of completion in signNow.
Upload the form:
Upload the current State and Local Tax Forms PDF. Check fields:
Confirm detected fields and add missing taxpayer fields. Assign roles:
Assign payer and recipient signing responsibilities. Send securely:
Send the form through signNow for completion. Save evidence:
Download the signed record and audit trail.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Ways to send and sign tax forms
- Use the signNow web app when an accounting or tax team prepares a State and Local Tax Form from a desktop workflow and needs to review fields before sending.
- Use the signNow mobile app when a payer or authorized employee collects or reviews taxpayer information away from the office, subject to organizational security controls.
- Use kiosk mode for supervised, in-person completion when an organization controls the device and needs multiple recipients to complete the same tax form sequentially.
- Use a shareable signing link when a payer distributes the same prepared State and Local Tax Form to recipients through an approved vendor or contractor channel.
Tax form processing stages
Processing follows four controlled stages, while any statutory filing deadline must be confirmed for the specific state and tax form.
Document preparation
Delivery to signers
Signer turnaround
Completion and archival
Retention schedule for tax records
Retention depends on the tax record and reporting circumstances; federal rules provide the following periods, while state requirements require separate review.
Three years for federal tax records
Six years for substantial understatement
Indefinite period for fraud
State-specific period may exceed federal
Policy-controlled deletion after review
Privacy and disclosure pitfalls
Taxpayer identification numbers can appear in signed copies, creating unnecessary exposure when access permissions are broader than the finance team requires. A missing consent record can weaken evidence that a contractor agreed to receive or sign electronic State and Local Tax Forms. Emailing completed forms as unrestricted attachments can expose taxpayer information outside approved finance, accounting, or vendor-management systems. Using one shared account obscures who prepared, reviewed, or sent a State and Local Tax Form.
Risks when tax records are incomplete
Reporting mismatch
Incomplete certification
IRS filing penalty
Audit support gap
Legal standing for U.S. transactions
Electronic completion and signatures on State and Local Tax Forms can be enforceable when the signer intends to sign, consents to electronic records, can be identified, and the record remains reproducible under ESIGN, 15 U.S.C. ch. 96, and applicable UETA or New York ESRA rules. Wills, court filings, family law decrees, and other statutory exceptions remain outside that framework.

Recommended tax form workflow setup
Configure the workflow around taxpayer privacy, signer attribution, and the applicable federal retention period.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Completion certificate and action history |
| Document retention | Three years under IRC §6501(a) |
| Encryption and provisioning | AES-256 with role-based user access |
Security for taxpayer information
Transport encryption:
Storage encryption:
Security certification:
Management standard:
Electronic signatures:
Protected health data:


Record-keeping practices for tax forms
Preserve the completed form, signer evidence, and applicable retention authority together so tax reporting teams can retrieve a defensible record.
Apply the correct federal retention period
Export the audit trail with each form
Restrict access to taxpayer information
Document state-specific retention decisions
Key performance indicators that demonstrate SignNow's proven track record.
Tax form troubleshooting and questions
Use these answers to resolve field, signing, retention, and legal-validity questions for State and Local Tax Forms workflows.
Upload the correct PDF or template and inspect signNow’s detected fields before sending. Add taxpayer, payer, date, and certification fields manually when detection does not identify them. The Business plan includes templates and audit trails for repeat collection workflows.
A signer can open the request through the email link and complete authentication without creating a full signNow account when the workflow permits guest signing. If SMS verification is enabled, the signer must enter the one-time code sent to the configured phone number.
Use a shareable signing link only through an approved distribution channel, and avoid posting it publicly. For taxpayer identification information, restrict link distribution and preserve the resulting audit trail with the completed State and Local Tax Form.
Electronic signatures may support State and Local Tax Forms under ESIGN and applicable UETA or ESRA rules when intent, consent, attribution, and record reproducibility are demonstrated. Consumer-facing workflows may also require the ESIGN disclosure under 15 U.S.C. §7001(c).
The Business plan is listed at $8 per user per month with annual billing and includes 100 signature invites per user per year. Business Premium adds bulk send; subscription overage fees may apply when the included invite allocation is exceeded.
Keep the signed document, completion certificate, and audit trail together. For federal tax records, IRC §6501(a) provides a three-year assessment period, but state rules and specific reporting circumstances may require longer retention. Confirm the schedule with a tax professional.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.