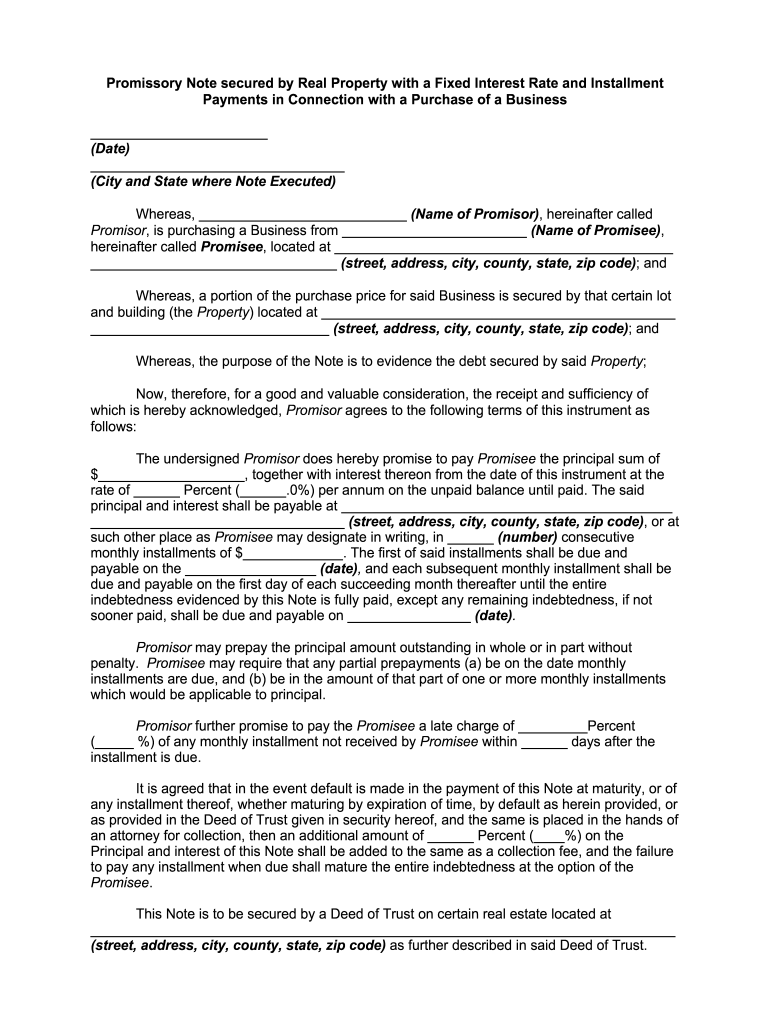
Promissory Note Secured By Real Property With A Fixed Interest Rate And Installment Form
Use a Promissory Note Secured By Real Property With A Fixed Interest Rate And Installment 0 template to make your document workflow more streamlined.
What this secured promissory note does
A Promissory Note Secured By Real Property With A Fixed Interest Rate And Installment Form records a borrower’s promise to repay a stated principal balance through scheduled installments at a fixed interest rate, while identifying real property as security for repayment. The form normally captures the parties, loan amount, interest rate, installment amount, payment dates, maturity date, default terms, and collateral description. The note is separate from a mortgage or deed of trust, which may require notarization and recording under applicable state law.
Who uses this secured note
Real-estate lenders
Real-estate lenders use this note to document a borrower’s promise to repay principal, fixed interest, and installments secured by identified property.
Borrowers and counsel
Borrowers, brokers, and attorneys review payment terms, collateral descriptions, maturity dates, and default provisions before signing and retaining the completed note.
Business types using secured notes
Property lenders, legal practices, and finance teams use this form when repayment is tied to identified real estate.
A solo real-estate attorney can prepare one borrower’s fixed-rate installment note, coordinate related security documents, and preserve the execution history in one transaction record. A regional private lender can use reusable templates for principal, interest, payment dates, maturity, and collateral fields across property-backed financing transactions. An enterprise lending team can connect signNow with NetSuite or Microsoft Dynamics 365 while administrators control templates, users, authentication, and archival access.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
How the secured note works
The form links a fixed-rate installment promise to specific real-property collateral.
Enter terms: State principal, fixed interest rate, payment schedule, maturity date, and borrower obligations. Describe collateral: Identify the real property securing repayment and confirm the legal description. Prepare document: Upload the completed form to signNow and place signer fields. Complete signing: Send the note, collect signatures, and retain the completed record.
Why teams look for DocuSign alternatives
Organizations seek alternatives when they need different pricing models, stronger native automation, simpler bulk affidavit workflows, or more flexible identity-verification options than those available in a legacy envelope-based vendor.

 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Complete the secured note online
Prepare the payment and collateral terms before using signNow to route the document for electronic signature.
Upload:
Upload the completed note. Detect fields:
Let signNow detect fillable fields. Assign roles:
Assign lender and borrower roles. Send:
Send the note for signature. Archive:
Store the signed copy and Audit Trail.
Ways to send and sign the note
- Use the signNow web app when a lender or attorney is preparing the secured note, placing fields, reviewing collateral language, and sending it to identified signers.
- Use the signNow mobile app when borrowers or representatives need to review and sign the installment note from a supported mobile device.
- Use kiosk mode for supervised, in-person signing at a lender, title, or legal office when one device serves multiple signers.
- Generate a shareable signing link when distributing the same approved note workflow to an identified borrower or authorized signing group.
Recommended setup for this note
Configure the signing workflow around the note’s repayment terms, collateral description, signer identity, and required recordkeeping policy.
| Setting | Recommendation |
|---|---|
| Authentication method | Email verification with SMS OTP |
| Signature type | Intent-based electronic signature |
| Audit trail | Export with the completed note |
| Document retention | Apply the governing transaction rule |
| Encryption | TLS 1.2/1.3 and AES-256 |
Security for signed loan records
Encryption:
Security certification:
Information security:
Electronic signatures:
Execution records:
Signer authentication:



Recordkeeping practices for secured notes
Preserve the repayment terms, collateral information, signed copy, and execution evidence as one controlled transaction record.
Verify every repayment and collateral term
Preserve the signed note and Audit Trail
Apply the applicable retention rule
Separate note signing from lien recording
Retention periods for related records
The promissory note itself has no single federal retention period; apply the rule governing the transaction and any related record class.
Three years: federal tax records
Three years or later: Form I-9
Six years: HIPAA documentation
Six years: broker-dealer records
Thirty years: exposure records
Risks requiring careful execution
Lien may remain unrecorded
Security interest becomes unclear
Repayment dispute may result
Modified terms may be challenged
Challenges when completing this note
A fixed interest rate, installment amount, payment dates, and maturity date must agree across the note and related closing documents. The real property description must identify the collateral accurately enough for counsel, title professionals, and the recording authority to review. Borrower, lender, and witness fields can be misassigned when multiple parties sign the same installment note. A signed promissory note may be retained correctly while the separate mortgage or deed of trust remains unnotarized or unrecorded.
Troubleshooting secured-note signing
Resolve field assignment, authentication, electronic-consent, and real-estate recording questions before relying on the completed note.
Upload the original PDF again and check that each borrower, lender, witness, and date field has the correct recipient. signNow’s Business plan includes templates and audit trails for routing the corrected note.
A signNow electronic signature can support a secured note under ESIGN and UETA when intent, consent, attribution, and record retention are established. State recording or notarization rules for the security instrument remain separate.
Use the signNow Business Premium plan when multiple borrowers or transactions require bulk send. The verified plan price is $15/user/month with annual billing and includes bulk send.
Business is listed at $8/user/month with annual billing and includes legally binding eSignatures, templates, mobile apps, and audit trails. Advanced signer authentication is listed with Enterprise at $30/user/month annually.
If the note includes consumer-facing electronic records, provide the ESIGN disclosure, explain paper-record rights, confirm electronic access, and explain withdrawal procedures under 15 U.S.C. §7001(c).
A signed note does not replace a mortgage or deed of trust, title recording, or a required notarization. Confirm the state’s real-estate recording rules and execute related instruments separately.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.