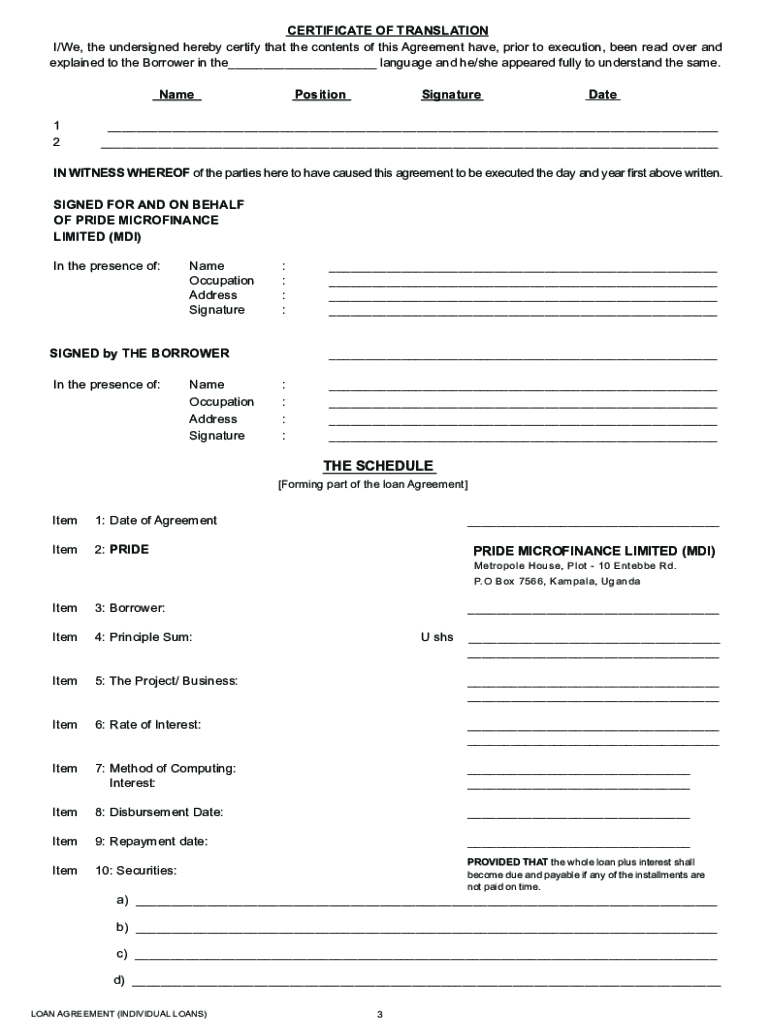
Family Loan Agreement Forms
Use a Family Loan Agreement Forms Sample 0 template to make your document workflow more streamlined.
What a family loan agreement form does
A Family Loan Agreement Form is a written contract that records money lent between relatives, including the principal amount, interest rate, payment schedule, maturity date, default terms, and signatures. The lender and borrower complete the specific financial terms before signing, then retain the executed copy with payment records. In the United States, electronic execution may be recognized under the ESIGN Act and applicable state law, including UETA, when intent, consent, attribution, and record reproducibility are established. Tax treatment and interest requirements can depend on the facts, so parties should consult a qualified adviser.
Who uses family loan agreement forms
Family borrowers
Parents, adult children, siblings, and other relatives use the form to document principal, interest, repayment dates, late-payment terms, and signatures before money changes hands. A written agreement separates personal relationships from financial obligations and gives every participant one consistent record of the transaction.
Family lenders
A family member providing funds can use the agreement to document disbursement, payment instructions, collateral language, and amendments. The signed record supports organized tax files and clarifies whether the arrangement is a loan rather than an informal gift.
How family loan agreements work in signNow
Complete the loan terms first, then use signNow to prepare, route, sign, and retain the agreement.
Upload form: Upload the blank or completed family loan agreement. Check fields: Review detected fields and add missing loan fields. Add signers: Enter lender and borrower delivery details. Complete signing: Collect signatures and preserve the completed record.
Quick steps for completing the form
Use these steps to turn agreed family-loan terms into one signed, traceable document.
Define terms:
State the principal, interest, payment dates, maturity date, and default terms. Prepare document:
Upload the agreement and verify every detected field. Assign signers:
Assign lender and borrower fields before sending. Retain copy:
Review the signed PDF and completion record.
Recommended family loan workflow setup
Configure the signing process around identity, evidence, controlled access, and the agreement’s tax-record requirements.
| Setting | Recommendation |
|---|---|
| Authentication method | Email delivery with SMS verification |
| Signature type | Electronic signature with recorded intent |
| Audit trail | Enable completion certificate and event history |
| Document retention | Retain through the applicable IRS period |
| Encryption | Use TLS 1.2/1.3 and AES-256 |
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
Security for signed loan records
Transport encryption:
Stored-data encryption:
Security reporting:
Information security:
Electronic signatures:
Signing evidence:
Privacy controls for family loan agreements
Borrower and lender addresses, account details, and Social Security numbers may remain exposed in broadly shared signed agreements. Missing electronic-consent language can weaken evidence that each family member agreed to receive and sign the agreement electronically. Unrestricted folder permissions can let unrelated staff view repayment terms, bank information, or signatures. Sending a draft with incomplete loan terms can create conflicting copies and disclose sensitive family financial information.
Risks of incomplete loan agreements
Unclear repayment terms
Missing interest evidence
No signed record
Conflicting copies
Record-keeping practices for family loans
Retain the executed agreement, payment evidence, amendments, and completion record according to the transaction’s tax and legal requirements.
Match retention to tax records
Export the audit trail
Archive signed records securely
Preserve amendment history
Retention periods for loan records
Retention depends on how the family loan affects tax reporting and applicable state requirements; preserve the signed agreement with payment evidence.
Three years after filing
Six years after filing
Indefinite for fraud
Indefinite without return
State period may exceed
Pricing for family loan workflows
signNow pricing and feature details are shown first; competitor values are marked Not verified where the supplied vendor data does not confirm them.
| Features | signNow | DocuSign | Adobe Sign | PandaDoc | Dropbox Sign |
|---|---|---|---|---|---|
| Starting annual price | $8/user/month Business plan | Not verified | Not verified | Not verified | Not verified |
| Free trial availability | 7 days, no credit card | Not verified | Not verified | Not verified | Not verified |
| Bulk send availability | Business Premium, $15/user/month | Not verified | Not verified | Not verified | Not verified |
| Audit trail availability | Business includes audit trails | Not verified | Not verified | Not verified | Not verified |
| HIPAA compliance | HIPAA compliant with BAA | Not verified | Not verified | Not verified | Not verified |
Businesses and families that use this form
The form is most useful when relatives need a written financial record for a personal loan, family-owned venture, or household purchase.
Parents lending down-payment funds can document principal, interest, installments, and default consequences before transferring money, reducing uncertainty while preserving a clear payment record for both households. Adult children borrowing education or housing funds can use one signed schedule to track installments, maturity, and amendments instead of relying on informal messages or changing verbal promises. Family-owned businesses can document relatives’ loans separately from ownership records, preserving lender, borrower, disbursement, repayment, and signature evidence for accounting and tax review.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Legal standing of family loan agreements
A signed family loan agreement can help establish intent, attribution, and the agreed repayment obligation. ESIGN and applicable state electronic-transactions law may recognize an electronic record when statutory requirements are met. Wills, codicils, testamentary trusts, certain court filings, and family-law decrees remain excluded from ESIGN.

Family loan agreement troubleshooting
Resolve field, delivery, authentication, legal-recognition, and retention questions before relying on the executed family loan agreement.
Upload the agreement again as a readable PDF, then review signNow’s detected fields before sending. Correct missing or misplaced lender and borrower fields manually so the principal, interest rate, payment schedule, and signatures attach to the intended clauses.
Open the recipient settings and confirm each lender or borrower email address. If identity evidence matters, add SMS verification or another available authentication control, then resend the signing invitation rather than forwarding an untracked copy.
The Business plan is listed at $8 per user monthly when billed annually and includes audit trails. Business Premium is $15 per user monthly annually and adds bulk send, which is useful for repeated agreements.
Electronic execution may satisfy ESIGN and applicable UETA requirements when intent, consent, attribution, and reproducibility are established. For a consumer-facing transaction, review the ESIGN disclosure requirements in 15 U.S.C. §7001(c).
Export the completed PDF and audit trail together after signing. Keep the original agreement, completion record, payment evidence, and amendments in controlled storage so the repayment history remains understandable and reproducible.
A Family Loan Agreement Form does not replace documents excluded from ESIGN, including wills, codicils, testamentary trusts, and certain family-law decrees or court filings. Obtain state-specific legal advice before adding collateral or real-estate interests.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.