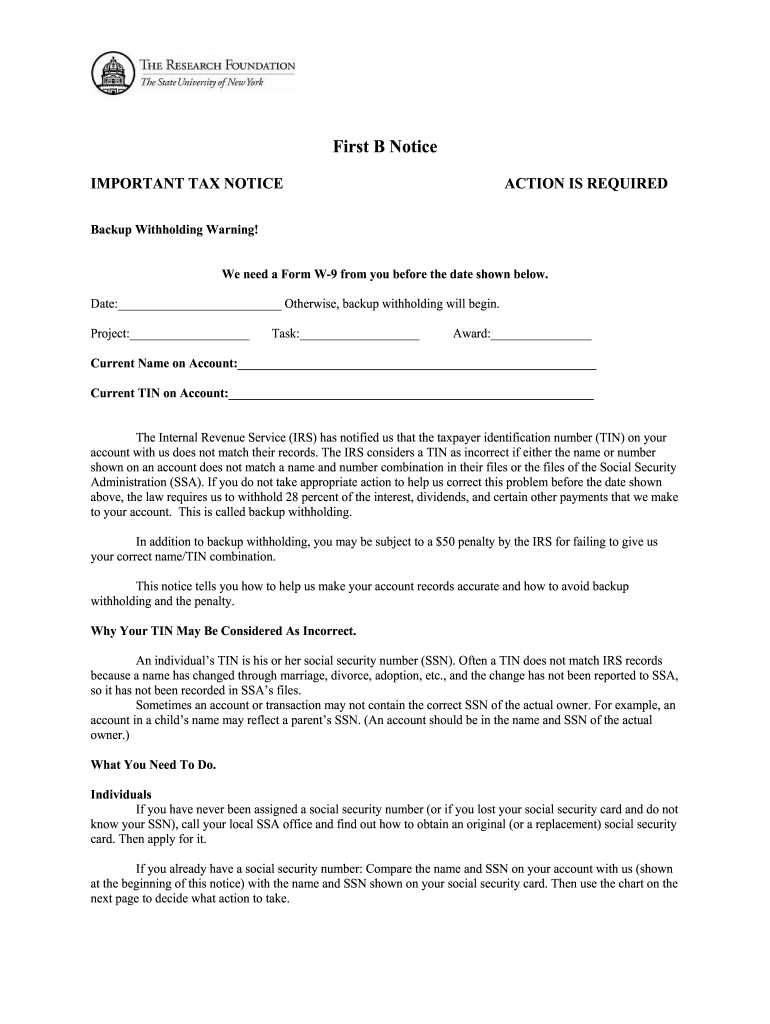
B Notice Form
Use a B Notice Template 0 template to make your document workflow more streamlined.
What the B Notice Form does
A B Notice Form is a payer’s written response to an IRS notice that a payee’s name and taxpayer identification number do not match IRS records. It tells the payee why the notice was issued, requests corrected taxpayer information, and explains the steps needed to prevent or address backup withholding. The payer records the notice, sends it to the payee, and retains the completed response with related W-9 information. For payments reaching the 2026 reporting threshold, backup withholding is 24% under IRC §3406, subject to applicable IRS procedures.
Who benefits from B Notice workflows
B Notice Form workflows serve payers that must communicate an IRS taxpayer-identification mismatch and document the resulting payee response.
Independent contractors and small businesses use B Notice workflows to document corrected taxpayer information after receiving an IRS name-and-TIN mismatch notice. Payroll and accounts-payable departments use controlled templates to send notices, collect updated W-9 information, and preserve evidence for federal tax reporting records. Enterprise finance teams use role-based access, audit trails, and integrations to coordinate high-volume payee corrections across subsidiaries and payment systems.
These tasks are executed by both individual contributors and centralized administrators depending on organizational policy and required controls.
Who uses a B Notice Form
Payers
Accounts-payable and payroll teams use B Notice Form to notify payees about IRS name-and-TIN mismatches, request corrected taxpayer information, and document delivery and response history. The workflow is suited to businesses handling contractor, vendor, or other reportable payments subject to federal information-reporting procedures.
Payees
Payees receiving an IRS-related mismatch notice use the response workflow to review their taxpayer details, provide corrected information, and sign the acknowledgment or correction record. Electronic delivery requires attention to ESIGN consumer-disclosure obligations when the payee is acting as a consumer.
How to process a B Notice
The signNow workflow keeps the IRS notice, payee response, and completion record together.
Upload documents: Upload the B Notice template and supporting payer records. Detect fields: Auto-detect fields for payee, TIN, notice date, and response details. Send notice: Send the notice and corrected-information request securely. Archive records: Store the signed response and audit trail for tax records.
 Best ROI. Our customers achieve an average 7x ROI within the first six months.
 Scales with your use cases. From SMBs to mid-market, airSlate SignNow delivers results for businesses of all sizes.
 Intuitive UI and API. Sign and send documents from your apps in minutes.
What the B Notice audit trail records
The audit trail documents the signing event and response history separately from the payer’s responsibility to verify taxpayer information.
Authenticate signer:
Capture timestamps:
Hash document:
Seal record:
Create certificate:
Export audit trail:
Recommended B Notice setup
Configure the workflow around IRS traceability, taxpayer-data protection, and controlled access.
| Setting | Recommendation |
|---|---|
| Authentication method | Email link with SMS OTP |
| Signature type | Typed or drawn electronic signature |
| Audit trail | Capture IP, timestamps, and action history |
| Document retention | Three years from filing (IRC §6501(a)) |
| Encryption | TLS 1.2/1.3 and AES-256 |
B Notice processing stages
No universal federal turnaround period is stated here; follow the IRS notice instructions and your payer’s documented tax procedures.
Document preparation
Delivery to payee
Payee turnaround
Completion and archival
Risks of mishandling a B Notice
Incorrect TIN
Missing notice
Incomplete response
Poor recordkeeping
Challenges when handling a B Notice
Matching the payee’s legal name and TIN exactly prevents a corrected W-9 from creating another IRS mismatch. Sending the notice to an outdated address can leave the payer unable to document delivery or obtain corrected information. Separating the B Notice from the related W-9 can make the response history difficult to reconstruct during an IRS review. Applying backup withholding without documenting the notice process can create disputes over payment calculations and payer records.
Best practices for B Notice records
Accurate matching, documented delivery, and controlled archival make the B Notice response easier to review.
Match names and TINs exactly
Preserve the complete response record
Export the audit trail
Apply the correct retention rule
Security for B Notice records
PKI signatures:
X.509 certificates:
Two-factor authentication:
SMS OTP:
ID verification:
Signing evidence:
Legal standing of a B Notice response
A completed B Notice response can be retained as an electronic business record when the payer demonstrates intent, consent where required, signer attribution, and reliable reproduction under ESIGN and applicable state law, including UETA or New York ESRA. The notice process does not replace IRS requirements for correcting name-and-TIN mismatches or applying backup withholding under IRC §3406.

B Notice Form troubleshooting
Resolve field, authentication, retention, plan, and electronic-delivery questions before sending taxpayer information.
Upload the IRS notice and B Notice template as separate documents, then use signNow’s field detection to identify payee, TIN, notice-date, and signature fields. Review every detected field before sending because automatic placement does not validate taxpayer information against IRS records.
A typed or drawn signature can document the payee’s response when the transaction permits electronic records. signNow Business includes legally binding eSignatures and audit trails; ESIGN and UETA establish electronic-signature validity, while the payer remains responsible for IRS process requirements.
signNow Business is listed at $8 per user per month with annual billing and includes audit trails, templates, and mobile apps. It includes 100 signature invites per user annually; additional invite charges may apply, so review volume before selecting a plan.
Use signNow authentication appropriate to the sensitivity of taxpayer information. SMS-based two-factor authentication can add signer attribution, but it does not replace the payer’s obligation to compare the corrected name and TIN with IRS documentation.
The B Notice workflow can store the completed notice, corrected information, and audit trail, but signNow does not determine the legally required retention period. For federal tax records, apply IRC §6501(a): three years from filing, six years for a 25% income understatement, or longer when fraud or no return applies.
If a consumer receives the notice electronically, review the ESIGN consumer-disclosure requirements in 15 U.S.C. §7001(c), including paper-record rights, electronic-access capability, and withdrawal procedures. signNow can capture consent and maintain an audit trail, but legal review may be necessary for the delivery model.
Key performance indicators that demonstrate SignNow's proven track record.
BE READY TO GET MORE
Get this form now!

If you believe that this page should be taken down, please follow our DMCA take-down process.